



 Chat with AI
Exam 14: Not-For-Profit Organizations Regulatory, taxation, and Performance Issues

Exam 1: Introduction to Accounting and Financial Reporting for Governmental and Not-For-Profit Entities48 Questions
Exam 2: Principles of Accounting and Financial Reporting for State and Local Governments50 Questions
Exam 3: Governmental Operating Statement Accounts; Budgetary Accounting67 Questions
Exam 4: Accounting for Governmental Operating Activitiesillustrative Transactions and Financial Statements85 Questions
Exam 5: Accounting for General Capital Assets and Capital Projects87 Questions
Exam 6: Accounting for General Long-Term Liabilities and Debt Service82 Questions
Exam 7: Accounting for the Business-Type Activities of State and Local Governments85 Questions
Exam 8: Accounting for Fiduciary Activities Agency and Trust Funds56 Questions
Exam 9: Financial Reporting of State and Local Governments50 Questions
Exam 10: Analysis of Governmental Financial Performance48 Questions
Exam 11: Auditing of Governmental and Not-For-Profit Organizations51 Questions
Exam 12: Budgeting and Performance Measurement58 Questions
Exam 13: Accounting for Not-For-Profit Organizations65 Questions
Exam 14: Not-For-Profit Organizations Regulatory, taxation, and Performance Issues56 Questions
Exam 15: Accounting for Colleges and Universities41 Questions
Exam 16: Accounting for Health Care Organizations46 Questions
Exam 17: Accounting and Reporting for the Federal Government52 Questions
Select questions type


The primary standards-setting body for a public museum that receives the majority of its funding from local property taxes is
(Multiple Choice)
4.9/5  (82)
(82) The following are key terms in Chapter 14 that relate to accounting for not-for-profit organizations:
A.Nonexchange transactions
B.Temporarily restricted net assets
C.Collections
D.Variance power
E.Exchange transactions
F.Board-designated net assets
G.Permanently restricted net assets
H.Promise to give
For each of the following definitions,indicate the key term from the list above that best matches by placing the appropriate letter in the blank space next to the definition. 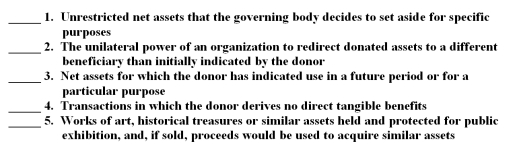
(Short Answer)
4.8/5 (83)
(83) Which of the following contributions would not have to be reported as an asset on the statement of financial position of a not-for-profit organization?
(Multiple Choice)
4.9/5 (71)
(71) A local philanthropist pledged to make a donation of $100,000 to an NPO to be paid in five equal installments of $20,000 beginning in the next fiscal year.Under FASB standards the pledge would be recognized as
(Multiple Choice)
4.7/5 (86)
(86) Which of the following is not a condition that must be met for contributed services to a not-for-profit organization (NPO)to be recorded as both a contribution and as an expense?
(Multiple Choice)
4.9/5 (97)
(97) When a not-for-profit (nongovernmental)organization spends money for the purpose for which an external donor intended,then the expense is reported as a
(Multiple Choice)
4.8/5 (87)
(87) Contributions received in a prior period and restricted by the donor for construction of a building were reported as increases to "temporarily restricted net assets" in the period received.When the building is constructed in a subsequent period an NPO would report "contributions" for the amount released from restrictions.
(True/False)
4.7/5 (69)
(69) Supporting services expenses include fund-raising and management and general expenses that are not directly attributable to specific programs.
(True/False)
4.9/5 (72)
(72) Explain the purpose of AICPA Statement of Position 98-2 as it relates to reporting fund-raising expenses of a not-for-profit organization.How is this statement applied?
(Essay)
4.8/5 (82)
(82) All not-for-profit organizations covered by the AICPA Audit and Accounting Guide Not-for-Profit Organizations are under the standards-setting jurisdiction of the FASB.
(True/False)
4.9/5 (84)
(84) Which of the following organizations would be covered by the AICPA Audit and Accounting Guide Not-for-Profit Organizations?
(Multiple Choice)
5.0/5 (73)
(73) Explain how SFAS No.136 provides for the recognition and reporting of funds received by one not-for-profit organization on behalf of another.
(Essay)
4.9/5 (82)
(82) A good reason for an NPO to adopt fund accounting even though FASB standards do not require it is that
(Multiple Choice)
4.8/5 (82)
(82) The statement of activities for an NPO must be prepared exactly as prescribed by the Financial Accounting Standards Board in SFAS No.117.
(True/False)
4.8/5 (82)
(82) Investments should be recorded at cost,or in the case of donated investments,at fair value as of the date of the gift.On subsequent balance sheets investments should be marked to and reported at market value with the valuation method disclosed and consistently followed.
(True/False)
4.8/5 (80)
(80) If the program services expenses category includes both directly related costs and indirect costs allocated to it,why is it necessary to have a separate category of "supporting services expenses"?
(Essay)
4.9/5 (77)
(77) A statement of functional expenses is not required of all voluntary health and welfare organizations.
(True/False)
4.9/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)