



 Chat with AI
Exam 6: Accounting for General Long-Term Liabilities and Debt Service

Exam 1: Introduction to Accounting and Financial Reporting for Governmental and Not-For-Profit Entities48 Questions
Exam 2: Principles of Accounting and Financial Reporting for State and Local Governments50 Questions
Exam 3: Governmental Operating Statement Accounts; Budgetary Accounting67 Questions
Exam 4: Accounting for Governmental Operating Activitiesillustrative Transactions and Financial Statements85 Questions
Exam 5: Accounting for General Capital Assets and Capital Projects87 Questions
Exam 6: Accounting for General Long-Term Liabilities and Debt Service82 Questions
Exam 7: Accounting for the Business-Type Activities of State and Local Governments85 Questions
Exam 8: Accounting for Fiduciary Activities Agency and Trust Funds56 Questions
Exam 9: Financial Reporting of State and Local Governments50 Questions
Exam 10: Analysis of Governmental Financial Performance48 Questions
Exam 11: Auditing of Governmental and Not-For-Profit Organizations51 Questions
Exam 12: Budgeting and Performance Measurement58 Questions
Exam 13: Accounting for Not-For-Profit Organizations65 Questions
Exam 14: Not-For-Profit Organizations Regulatory, taxation, and Performance Issues56 Questions
Exam 15: Accounting for Colleges and Universities41 Questions
Exam 16: Accounting for Health Care Organizations46 Questions
Exam 17: Accounting and Reporting for the Federal Government52 Questions
Select questions type


Installments of special assessments to be collected within one year are recorded as Assessments Receivable-Current; installments due in periods after one year are recorded as Assessments Receivable-Deferred.
(True/False)
4.9/5  (79)
(79) Bonds and other debt of enterprise funds may legally,at least contingently,have the status of tax-supported debt.In the event that enterprise fund resources are insufficient for debt service on such debt,why might the government as a whole find it necessary or desirable to assume responsibility for debt service? How would assumption of responsibility for such debt by the government as a whole be accounted for in the governmental activities accounts in the enterprise fund?
(Essay)
4.9/5 (76)
(76) Which of the following statements is not true for debt service funds?
(Multiple Choice)
4.9/5 (69)
(69) All long-term debt,including bonds,notes or warrants,and various other long-term obligations,intended to be repaid from tax levies or special assessments are accounted for in debt service funds.
(True/False)
4.8/5 (80)
(80) Capital lease payments should be recorded by a debt service fund rather than the fund using the leased asset.
(True/False)
4.7/5 (85)
(85) At year-end,budgetary and operating statement accounts of a debt service fund are closed in the same manner as are those of a General Fund or special revenue funds.
(True/False)
4.9/5 (80)
(80) Basic financial statements are often supplemented by schedules of securities held at the balance sheet date,and other schedules detailing securities transactions during the year.
(True/False)
4.9/5 (68)
(68) "Bonds to be retired by a debt service fund are recorded in that fund throughout their life." Do you agree or disagree? Why or why not?
(Essay)
4.7/5 (75)
(75) Special assessments levied for debt service of bonds issued for a special assessment capital project will be accounted for by a debt service fund under which of the following situations? 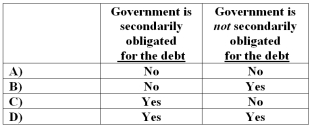
(Multiple Choice)
4.7/5 (75)
(75) Issuance of tax supported debt having a maturity of more than one year from date of issue results in a journal entry in only the governmental activities general journal.
(True/False)
4.8/5 (79)
(79) The city of Sparr's fiscal year ends on December 31.On July 1,2011,the city issued $1,000,000 of 6%,10-year term bonds with semi-annual interest payments due on July 1 and January 1 each year,beginning on January 1,2012.What amount of expenditures should the city recognize in its debt service fund for the years 2011 and 2012?
(Multiple Choice)
4.7/5 (82)
(82) On June 1,2012,Brooktown levied special assessments in the amount of $500,000,payable in 10 equal annual installments beginning on June 30,2012.The assessment installments are intended to pay principal and interest on special assessment bonds for which the town has pledged its full faith and credit should assessments be insufficient.Assuming no allowance for uncollectible receivables,the journal entry in the debt service fund on June 1,2012 would include:
(Multiple Choice)
4.9/5 (68)
(68) Modified accrual accounting is used for debt service funds in which of the following ways?
(Multiple Choice)
4.9/5 (76)
(76) From records available in various offices of Baraga County,you find the following information about changes in long-term liabilities of the county during the year ended June,2012:
1)At the end of the 2011 fiscal year,$500,000 was still outstanding on an issue of a 3 percent serial bond that matures at the rate of $250,000 per year.The payment during fiscal year 2012 has been made by the debt service fund.
2)Baraga County council decided to fund a General Fund deficit with an issue of four-year notes totaling $480,000.The notes were issued on July 1,2011,and were to be retired at the rate of $120,000 per year; the first payment was to be made on July 1,2012 by the debt service fund.
3)At the end of the 2011 fiscal year,$100,000 par value general obligation serial bonds were outstanding,from an original amount of $400,000.Annual maturities of $25,000 have been paid on December 31 of each year.
4)In FY 2011 an issue of 7 percent serial bonds was sold in the amount of $6,000,000.The issue matures at the rate of $300,000 per year.The first payment was made in FY 2012.
5)On June 30,2011 the county had outstanding $200,000 of 4 percent serial bonds that had been issued to finance a revenue-producing recreation facility.On June 1,2012 bonds in the amount of $50,000 were paid.The bonds are being paid from enterprise revenues; they carry a covenant that obligates the county to levy taxes to service the debt if enterprise revenues are insufficient.It is expected that enterprise revenues will be sufficient to retire the bonds on schedule.
6)During FY 2012 a $300,000 issue of 6 percent term bonds matured,with little provision having been made for their payment.The bonds were closely held,and arrangements were made with holders of all but $25,000 to accept 8 percent refunding serial bonds.Cash was paid to creditors who declined to accept refunding bonds.
Required: Prepare a schedule disclosing the changes in long-term liabilities for Baraga County for the year ended June 30,2012.
(Essay)
4.7/5 (67)
(67) Disclosures about long-term liabilities should be included in the notes to the financial statements to provide users with information about authorization of new debt issues,sale of previously authorized issues,and retirement and refunding of debt during the year.
(True/False)
4.8/5 (92)
(92) Typically,proceeds from general obligation bonds will be recorded in the
(Multiple Choice)
4.9/5 (84)
(84) Debt limit is a term used to denote the total amount of indebtedness of specified kinds that is allowed by law to be outstanding at any one time.
(True/False)
4.9/5 (76)
(76) If all financial resource inflows have been collected,and all debt interest and principal legally due has been paid,a regular serial bond debt service fund could have no assets,no liabilities,and no fund balance at year-end.
(True/False)
4.7/5 (86)
(86) Term bond debt service funds should always be accounted for on the assumption that they are operated on an actuarial basis.
(True/False)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)