



 Chat with AI
Exam 6: Merchandise Inventory

Exam 1: Accounting and the Business Environment143 Questions
Exam 2: Recording Business Transactions156 Questions
Exam 3: The Adjusting Process152 Questions
Exam 4: Completing the Accounting Cycle156 Questions
Exam 5: Merchandising Operations160 Questions
Exam 6: Merchandise Inventory155 Questions
Exam 7: Accounting Information Systems137 Questions
Exam 8: Internal Control and Cash160 Questions
Exam 9: Receivables138 Questions
Exam 10: Plant Assets, Natural Resources, and Intangibles151 Questions
Exam 11: Current Liabilities and Payroll162 Questions
Exam 12: Partnerships161 Questions
Exam 13: Corporations158 Questions
Exam 14: Long-Term Liabilities151 Questions
Exam 15: Investments135 Questions
Exam 16: The Statement of Cash Flows154 Questions
Exam 17: Financial Statement Analysis112 Questions
Exam 18: Introduction to Managerial Accounting179 Questions
Exam 19: Job Order Costing152 Questions
Exam 20: Process Costing144 Questions
Exam 21: Cost-Volume-Profit Analysis172 Questions
Exam 22: Master Budgets114 Questions
Exam 23: Flexible Budgets and Standard Cost Systems173 Questions
Exam 24: Cost Allocation and Responsibility Accounting129 Questions
Exam 25: Short-Term Business Decisions161 Questions
Exam 26: Capital Investment Decisions122 Questions
Select questions type


The gross profit method is a way to estimate inventory on the basis of the cost of goods sold model.
(True/False)
4.8/5  (82)
(82) Which of the following states that a company must perform strictly proper accounting only for items that are significant to the business's financial statements?
(Multiple Choice)
4.9/5 (87)
(87) Williams Company had the following balances and transactions during 2014. 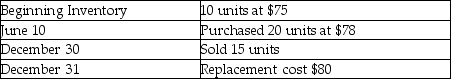 Williams maintains its records of inventory on a perpetual basis using the last-in, first-out method. Calculate the amount of ending Merchandise Inventory at December 31, 2014 using the lower-of-cost-or-market rule.
 (Multiple Choice)
4.8/5 (56)
(56) Henderson Sales sold 400 units of product to a customer on account. The selling price was $28 per unit, and the cost, according to the company's inventory records, was $14 per unit. Provide the journal entry to record cost of goods sold. (Assume a perpetual inventory system)
(Essay)
4.8/5 (72)
(72) Which of the following states that the business should use the same accounting methods from period to period?
(Multiple Choice)
4.9/5 (92)
(92) A company changes its inventory costing method each period in order to maximize net income. This is a violation of the consistency principle.
(True/False)
4.9/5 (80)
(80) Rubal Inc. earned revenue of $400,000 and incurred cost of goods sold of $320,000. Calculate the gross profit percent.
(Multiple Choice)
4.7/5 (79)
(79) Which of the following assets must be reported at the lower-of-cost-or-market value?
(Multiple Choice)
4.9/5 (89)
(89) Samson Company had the following balances and transactions during 2014: 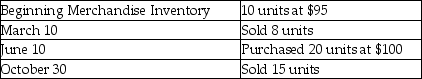 What is the amount of the company's Merchandise Inventory, as disclosed in the December 31, 2014 balance sheet as per the periodic first-in, first-out (FIFO)costing method?
 (Multiple Choice)
4.9/5 (85)
(85) The ending Merchandise Inventory for the current accounting period is understated by $2,700. What effect will this error have on Cost of Goods Sold and Net Income?
(Multiple Choice)
4.9/5 (85)
(85) A company that uses the perpetual inventory system sold goods to a customer for cash for $3,000. The cost of the goods sold was $1,000. Which of the following journal entries correctly records this transaction?
(Multiple Choice)
4.7/5 (83)
(83) A high rate of inventory turnover indicates ease in selling inventory.
(True/False)
4.9/5 (81)
(81) A lower days' sales in inventory for Company X when compared to other companies, indicates that Company X:
(Multiple Choice)
4.9/5 (86)
(86) Under GAAP, which of the following amounts would be reported as Merchandise Inventory on the balance sheet of a company if the cost of an item is $85 and the current replacement cost is $70?
(Multiple Choice)
4.8/5 (73)
(73) The beginning inventory of Soft Toys Company was $46,000. The purchases (excluding returns)and sales revenue for the year were $230,000 and $325,000, respectively. The purchase returns amounted to $30,000. The company's normal gross profit percent is 60%. What is the amount of estimated ending inventory?
(Multiple Choice)
4.8/5 (74)
(74) Perez Company purchased inventory on account for $6,500. Provide the journal entry to record the purchase of inventory on account. (Assume a perpetual inventory system)
(Essay)
4.8/5 (68)
(68) Using the first-in, first-out (FIFO)method of inventory valuation will always produce the same results whether a company uses perpetual or periodic inventory.
(True/False)
4.8/5 (70)
(70) Under the last-in, first-out method, the amount of cost of goods sold calculated using the perpetual inventory system will differ from the amount calculated using the periodic inventory system.
(True/False)
4.7/5 (86)
(86) Which of the following is the correct formula to calculate inventory turnover?
(Multiple Choice)
4.7/5 (77)
(77) A company purchased 100 units for $20 each on January 31. It purchased 100 units for $30 on February 28. It sold a total of 150 units for $45 each from March 1 through December 31. What is the amount of ending inventory on December 31, if the company uses the first-in, first-out (FIFO)inventory costing method? (Assume that the company uses a perpetual inventory system.)
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)