



 Chat with AI
Exam 14: Investments in Debt and Equity Securities

Exam 1: Financial Reporting89 Questions
Exam 2: A Review of the Accounting Cycle100 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements74 Questions
Exam 4: The Income Statement86 Questions
Exam 5: Statement of Cash Flows and Articulation83 Questions
Exam 6: Earnings Management47 Questions
Exam 7: The Revenuereceivablescash Cycle87 Questions
Exam 8: Revenue Recognition89 Questions
Exam 9: Inventory and Cost of Goods Sold134 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing111 Questions
Exam 13: Equity Financing97 Questions
Exam 14: Investments in Debt and Equity Securities88 Questions
Exam 15: Leases83 Questions
Exam 16: Income Taxes87 Questions
Exam 17: Employee Compensation-Payroll,pensions, Other Compissues83 Questions
Exam 18: Earnings Per Share86 Questions
Exam 19: Derivatives, contingencies, business Segments, and Interim Reports82 Questions
Exam 20: Accounting Changes and Error Corrections86 Questions
Exam 21: Statement of Cash Flows Revisited68 Questions
Exam 22: Accounting in a Global Market62 Questions
Exam 23: Analysis of Financial Statements65 Questions
Select questions type


The equity method of accounting should be applied by an investor to an investment in the voting stock of an investee of 20% or more of the voting stock of the investee.An investment of 20% or more of the voting stock of an investee should lead to the presumption (absent evidence to the contrary)that an investor has the ability to exercise significant influence over an investor.The presumption in applying the equity method is that an investor has significant influence over the operating and financial policies of an investee even though the investor holds 50% or less of the voting stock of the investee.
Required:
Identify events or circumstances that suggest that an investor has significant influence over an investee.
(Essay)
4.9/5  (83)
(83) Which of the following is true regarding the provisions of IAS 39?
(Multiple Choice)
5.0/5 (88)
(88) Elio Co.purchased the following portfolio of trading securities during 2014 and reported the following balances at December 31,2014.No sales occurred during 2014.All declines are considered to be temporary.
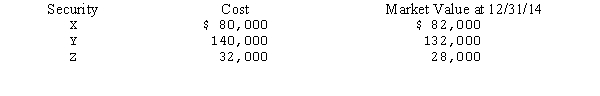 The carrying value of the portfolio at December 31,2014,on Elio Co.'s balance sheet would be
 (Multiple Choice)
4.8/5 (64)
(64) Investments in debt securities currently are permitted to be classified as held-to-maturity and accounted for at amortized cost if an enterprise has the positive intent and ability to hold these securities to maturity.The held-to-maturity classification is the most restrictive of the three classifications specified in accounting standards.Despite the restrictiveness of the held-to-maturity classification,certain changes in circumstances may occur that would necessitate transferring an investment in a debt security from the held-to-maturity classification without calling into question the investor's general intention to hold other similarly classified investments to maturity.
What types of circumstances would cause an investor in debt securities classified as held-to-maturity to change that classification without calling into question the intent of the investor to hold other similarly classified investments to maturity?
(Essay)
4.8/5 (78)
(78) Which of the following is true regarding the provisions of International Accounting Standard No.39,"Financial Instruments: Recognition and Measurement (amended 2005)?
(Multiple Choice)
4.9/5 (91)
(91) If an investment in stock is reclassified from available-for-sale securities to trading securities,the stock should be recorded on the date it is reclassified at the
(Multiple Choice)
4.7/5 (68)
(68) When an investor uses the cost method to account for investments in common stock,cash dividends received by the investor from the investee should normally be recorded as
(Multiple Choice)
4.7/5 (87)
(87) The only significant difference between the provisions of international accounting standards as promulgated by IAS 39 and U.S.accounting standards under FASB ASC Topic 860 (Transfers and Servicing is
(Multiple Choice)
4.9/5 (93)
(93) On January 1,2014,Kimba Co.paid $500,000 for 20,000 shares of Flathead Co.'s common stock and classified these shares as trading securities.Kimba does not have the ability to exercise significant influence over Flathead.Flathead declared and paid a dividend of $.50 a share to its stockholders during 2014.Flathead reported net income of $260,000 for the year ended December 31,2014.The fair value of Flathead Co.'s stock at December 31,2014,is $27 per share.What is the net asset amount (which includes both investments and any related market adjustments)attributable to the investment in Flathead that will be included on Kimba's balance sheet at December 31,2014?
(Multiple Choice)
4.8/5 (81)
(81) The equity method of accounting should be applied by an investor to an investment in the voting stock of an investee of 20% or more of the voting stock of the investee.An investment of 20% or more of the voting stock of an investee should lead to the presumption (absent evidence to the contrary)that an investor has the ability to exercise significant influence over an investor.The presumption in applying the equity method is that an investor has significant influence over the operating and financial policies of an investee even though the investor holds 50% or less of the voting stock of the investee.
Required:
Identify events or circumstances that suggest that an investor may be unable to exercise significant influence over an investee.
(Essay)
4.9/5 (92)
(92) If the combined market value of trading securities at the end of the year is less than the market value of the same portfolio of trading securities at the beginning of the year,the difference should be accounted for by
(Multiple Choice)
4.9/5 (78)
(78) A firm purchased bonds to be classified as an investment in securities available-for-sale.The bonds were purchased at a premium.Assume the market price of the bond is volatile.Given these facts,which of the following is correct?
(Multiple Choice)
4.9/5 (74)
(74) On August 1,2013,Abruzzo Corp.acquired 10,000 of the outstanding shares of Tuscany Co.On January 2,2014,Abruzzo acquired an additional 20,000 shares of Tuscany Co.,which brought the total ownership to 30,000 shares.Using the normal guidelines for percentages of ownership and assuming that Tuscany Co.had 100,000 shares outstanding during 2013 and 2014,Abruzzo Corp.should account for the investment in Tuscany Co.by using the
(Multiple Choice)
4.9/5 (87)
(87) Consolidated financial statements are typically prepared when one company has
(Multiple Choice)
4.9/5 (74)
(74) Changes in fair value of securities are reported in the income statement for which type of securities?
(Multiple Choice)
4.9/5 (88)
(88) Sanders Company began business in February of 2013.During the year,Sanders purchased the three trading securities listed below.On its December 31,2013,balance sheet,Sanders appropriately reported a $4,000 credit balance in its Market Adjustment--Trading Securities account.There was no change during 2014 in the composition of Sanders' portfolio of trading securities.Pertinent data are as follows:
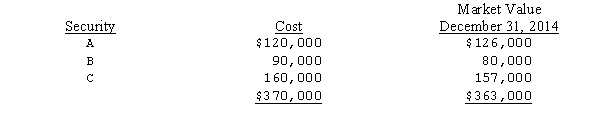 What amount of loss on these securities should be included in Sanders' income statement for the year ended December 31,2014?
 (Multiple Choice)
4.7/5 (88)
(88) Anson Company began operations in 2013.The company's trading securities portfolio,which did not change in composition during 2014,is as follows:
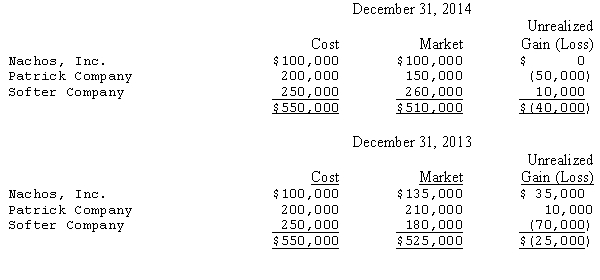 Ignoring income taxes,what amount should be reported as an unrealized loss on trading securities in Anson's 2014 income statement?
 (Multiple Choice)
4.8/5 (91)
(91) Aronson,Inc.began business on January 1,2014,and at December 31,2014,Aronson had the following investment portfolios of equity securities:
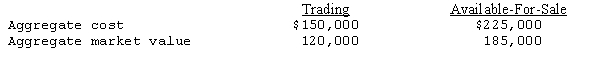 None of the declines is judged to be other than temporary.Unrealized losses at December 31,2014,should be recorded with corresponding charges against
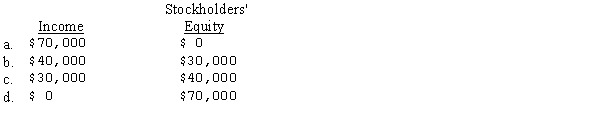
None of the declines is judged to be other than temporary.Unrealized losses at December 31,2014,should be recorded with corresponding charges against
(Short Answer)
4.9/5 (77)
(77) The following information is available for an enterprise's security investments as of December 31, 2014:
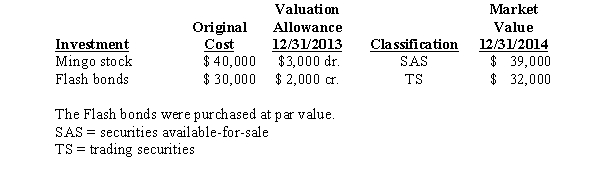 -In June 2015,the enterprise decided to reclassify the Mingo stock as trading securities.The stock had a market value of $41,000 at the time of the reclassification.
What amount of holding gain or loss is immediately recognized in 2015 earnings?
-In June 2015,the enterprise decided to reclassify the Mingo stock as trading securities.The stock had a market value of $41,000 at the time of the reclassification.
What amount of holding gain or loss is immediately recognized in 2015 earnings? (Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)