



 Chat with AI
Exam 8: Revenue Recognition

Exam 1: Financial Reporting89 Questions
Exam 2: A Review of the Accounting Cycle100 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements74 Questions
Exam 4: The Income Statement86 Questions
Exam 5: Statement of Cash Flows and Articulation83 Questions
Exam 6: Earnings Management47 Questions
Exam 7: The Revenuereceivablescash Cycle87 Questions
Exam 8: Revenue Recognition89 Questions
Exam 9: Inventory and Cost of Goods Sold134 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing111 Questions
Exam 13: Equity Financing97 Questions
Exam 14: Investments in Debt and Equity Securities88 Questions
Exam 15: Leases83 Questions
Exam 16: Income Taxes87 Questions
Exam 17: Employee Compensation-Payroll,pensions, Other Compissues83 Questions
Exam 18: Earnings Per Share86 Questions
Exam 19: Derivatives, contingencies, business Segments, and Interim Reports82 Questions
Exam 20: Accounting Changes and Error Corrections86 Questions
Exam 21: Statement of Cash Flows Revisited68 Questions
Exam 22: Accounting in a Global Market62 Questions
Exam 23: Analysis of Financial Statements65 Questions
Select questions type


Which of the following types of service transactions is most likely to require the proportional performance method of revenue recognition based on the seller's direct costs to perform each act?
(Multiple Choice)
4.8/5  (77)
(77) Stone Company,a publicly traded company,delivers twenty truckloads of Stone to Mortar Company prior to December 31,2014,the end of Stone's fiscal year.Stone normally enters into a written sales agreement with customers similar to Mortar Company.The written sales agreement must be signed by both companies in order to be binding.Although the purchasing department of Mortar has orally agreed to the sale,Mortar management cannot sign the agreement until it is approved by the legal department of Mortar.Personnel of the legal department of Mortar will be on vacation until January 5,2015.
Can Stone recognize on its income statement for the year ending December 31,2014,the revenue related to the twenty truckloads delivered to Mortar? Explain.
(Essay)
4.8/5 (77)
(77) Revenue is measured in terms of the value of the products or services exchanged in an "arms-length" transaction.This value represents either the net cash equivalent or the present discounted value of the money received or to be received in exchange for the products or services that an enterprise transfers to its customer.
Required:
Explain how this concept of the measurement of revenue might be used to determine the proper treatment of sales discounts and bad debt losses.
(Essay)
4.9/5 (75)
(75) Carson Distributing,which began operating on January 1,appropriately uses the installment method of accounting.The following information pertains to Carson's operations for the first year:
 The balance in the deferred gross profit account at December 31 should be
 (Multiple Choice)
4.9/5 (82)
(82) Builder Construction Company's projects extend over several years and collection of receivables is reasonably certain.Each project has a contract that specifies a price and the rights and obligations of all parties.Both the contractor and the customer are expected to fulfill their contractual obligations on each project.Reliable estimates can be made of the extent of progress and cost to complete each project.The method that the company should use to account for construction revenue is
(Multiple Choice)
4.8/5 (68)
(68) When Progress Billings are made by a contractor on a long-term contract,what account is credited?
(Multiple Choice)
4.9/5 (72)
(72) ProAudio manufactures and sells audio and video conferencing equipment.The company sells its products through a nationwide network of distributors complemented by a direct sales force.The distributors had a written agreement with ProAudio requiring the distributors to pay ProAudio within 90 days of receiving ProAudio products.The agreement also required distributors to take title to ProAudio products at the time the products left ProAudio's warehouse.
Through early 2014,ProAudio experienced robust growth and increased product sales every quarter.In early 2014,it became apparent to ProAudio's CEO,Linda Masters,that the company would not meet its sales and revenue projections for the quarter ended March 31,2014.At the end of March 2014,Masters instructed Seth Nein,ProAudio's Director of Manufacturing,to assemble enough products to ship to distributors in order to meet ProAudio's sales projections.Masters entered into an agreement with one of ProAudio's distributors,Astro Marketing,to accept these products.The management of Astro Marketing was assured that the transaction posed no risk to them.Masters also informed Astro management that Astro would not be required to pay for the merchandise until it was sold.Meanwhile,ProAudio recorded an account receivable and revenue for this sale.These same procedures were followed at the end of each quarter for which ProAudio anticipated falling short of its sales projections,including the recognition of revenue by ProAudio.
During this same time period,ProAudio,whose stock was publicly traded,was planning a private placement of additional shares of stock totaling $25.5 million.Accordingly,the stock price needed to remain high in order for the private placement to be attractive to investors.
Required:
Does the plan effected by Masters conform with Generally Accepted Accounting Principles (GAAP)?
(Essay)
4.9/5 (89)
(89) A construction company uses the percentage-of-completion method for long-term construction contracts.A particular job was begun in 2014 and completed in 2015.During 2014,it appeared that the project would cost 25 percent more than originally expected.Data at the end of each year are given below:
 The contract price was $700,000.Assuming the company properly recorded income in 2013,how much income should be recorded in 2014?
 (Multiple Choice)
4.9/5 (79)
(79) D.C.System Services provides its customers with computer-based services over an extended period.Customers are required to prepay the entire fee for the extended service.D.C.performs initial setup activities to enter a customer into its system.The initial setup allows the customer to receive automated services from D.C.from that point forward in the service agreement.
The management of D.C.plans to recognize the revenue over the life of the service contract,but plans to recognize a disproportionate amount of revenue at the beginning of the contract as a result of the completion of the setup activities and the cost incurred in connection with the completion of the setup activities.
Required:
Do you agree with the proposal by the management of D.C.regarding revenue recognition related to the setup activities? How should revenue be recognized for an agreement such as this?
(Essay)
4.9/5 (93)
(93) Assume the percentage-of-completion method of revenue recognition is used on a long-term construction contract.Under this method,revenues that are earned but unbilled at the balance sheet date should be disclosed
(Multiple Choice)
4.9/5 (72)
(72) The percentage-of-completion method is used to recognize revenue and gross profit for construction and other types of projects that extend beyond one accounting period.A problem similar to long-term construction projects exists in accounting for service revenue that is earned for more than one performance act where such activity extends beyond one accounting period.
Provide examples of service activities that might extend beyond one accounting period and propose means of recognizing revenues for such activities.
(Essay)
4.8/5 (94)
(94) Soborne Construction,Inc.,is constructing a building for another company.Construction on the building began in 2014 and is expected to be complete in 2015.The fixed contract price was $1,500,000.During 2014,the company made the following entries:
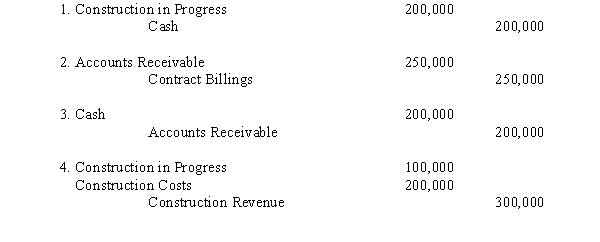 Required:
Briefly explain the 2014 entries and why they occurred.Show the calculations and include in your explanations the nature of and the reporting of the Contract Billings account.
Required:
Briefly explain the 2014 entries and why they occurred.Show the calculations and include in your explanations the nature of and the reporting of the Contract Billings account. (Essay)
4.8/5 (72)
(72) If the percentage-of-completion method is used,what is the basis for determining the gross profit to be recognized in the second year of a three-year contract?
(Multiple Choice)
4.7/5 (86)
(86) Which of the following best describes the condition(s)that must be present for the recognition of revenue?
(Multiple Choice)
4.9/5 (77)
(77) A company providing maintenance services on equipment for a fixed periodic fee would recognize
(Multiple Choice)
4.9/5 (84)
(84) Sonny's Dry Cleaners,Inc.charges an initial franchise fee of $195,000.When the agreement is signed,a payment of $75,000 is due,followed by four annual payments of $30,000 at the end of each period.Sonny's normal borrowing rate is 12%.Prepare the entries to record the initial franchise fee on the books of Sonny's under each of the following circumstances.
(1)The franchiser has substantial services to perform and the collection of the note is extremely uncertain.
(2)The down payment is nonrefundable,collection of the note is reasonably assured,and the franchiser has performed substantially all of the services required by the initial fee.
(3)The down payment is nonrefundable,collection of the note is reasonably assured,the franchiser has performed services equivalent to the down payment,but substantial services remain to be performed.
(Essay)
5.0/5 (91)
(91) The completed-contract method of accounting for long-term construction-type contracts is preferable when
(Multiple Choice)
4.7/5 (78)
(78) The Albert Corporation sells merchandise on the installment basis,and the uncertainties of cash collection make the use of the installment sales method of accounting acceptable.The following data relate to two years of operations.
 Record the transactions related to installment sales for 2014 and 2015.
 (Essay)
4.8/5 (76)
(76) Kona Medical Center uses the cost recovery method of accounting for recognizing revenue.The following information is available:
 Determine the amount of gross profit to be recognized for 2014,2015,and 2016.
 (Essay)
4.9/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)