



 Chat with AI
Exam 8: Accounting for Joint Arrangements

Exam 1: Text Objectives and Introduction to Consolidation28 Questions
Exam 2: Principles of Consolidation42 Questions
Exam 3: Fair Value Adjustments and Tax Effects34 Questions
Exam 4: Intra-Group Transactions36 Questions
Exam 5: Non-Controlling Interest37 Questions
Exam 6: Partly-Owned Subsidiaries: Indirect Non-Controlling Interest27 Questions
Exam 7: Consolidated Cash Flow Statements25 Questions
Exam 8: Accounting for Joint Arrangements44 Questions
Exam 9: Accounting for Associates and Joint Ventures: the Equity Method37 Questions
Exam 10: Translation and Consolidation of Foreign Currency Financial Statements31 Questions
Exam 11: Segment Reporting by Diversified Entities27 Questions
Select questions type


The following statements of shareholders' equity were prepared for Harnham Hill Ltd,a 20% owned associate of the parent entity Delville Wood Ltd,at June 30 (amounts in thousands): 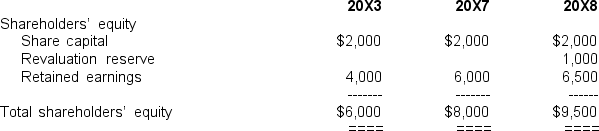 Other information:
I.Delville Wood Ltd acquired its 20% investment on July 1 20X3 for a cash outlay of $2,000,000.
II.During the year ended June 30 20X8,Harnham Hill Ltd earned a profit of $1,400,000 before tax (income tax expense $400,000)and paid a dividend of $500,000.
III.At June 30 20X7,Delville Wood Ltd held inventories which had been supplied by Harnham Hill Ltd at a mark-up of $100,000.
IV.At June 30 20X8,a subsidiary of Delville Wood Ltd held inventories that had been supplied by Harnham Hill Ltd at a mark-up of $50,000.
V.During the year ended June 30 20X8,Delville Wood Ltd charged Harnham Hill Ltd with a management fee of $100,000 for administration services.
VI.In the income statement of Harnham Hill Ltd was interest revenue of $50,000 which had been earned on a loan made to a subsidiary of Delville Wood Ltd.
VII.The income tax rate was 30%.
VIII.Any goodwill element in the cost of the investment had not been impaired in the investment period.
In preparing the consolidated financial statements for the year ended June 30 20X8,the journal adjustment to recognise the equity of Delville Wood Ltd in its associate would be:
Other information:
I.Delville Wood Ltd acquired its 20% investment on July 1 20X3 for a cash outlay of $2,000,000.
II.During the year ended June 30 20X8,Harnham Hill Ltd earned a profit of $1,400,000 before tax (income tax expense $400,000)and paid a dividend of $500,000.
III.At June 30 20X7,Delville Wood Ltd held inventories which had been supplied by Harnham Hill Ltd at a mark-up of $100,000.
IV.At June 30 20X8,a subsidiary of Delville Wood Ltd held inventories that had been supplied by Harnham Hill Ltd at a mark-up of $50,000.
V.During the year ended June 30 20X8,Delville Wood Ltd charged Harnham Hill Ltd with a management fee of $100,000 for administration services.
VI.In the income statement of Harnham Hill Ltd was interest revenue of $50,000 which had been earned on a loan made to a subsidiary of Delville Wood Ltd.
VII.The income tax rate was 30%.
VIII.Any goodwill element in the cost of the investment had not been impaired in the investment period.
In preparing the consolidated financial statements for the year ended June 30 20X8,the journal adjustment to recognise the equity of Delville Wood Ltd in its associate would be: (Multiple Choice)
4.9/5  (71)
(71) Where an associate makes profits subsequent to the investor's acquisition of the equity investment,a deferred tax liability will be required to be recognised.
(True/False)
4.9/5 (72)
(72) Which of the following is not an indication that an investor has the power to exert significant influence over an investee company?
(Multiple Choice)
4.8/5 (75)
(75) If an investment in an associate entity were to be accounted for using the cost method,the investment is initially recognised at its cost of acquisition and:
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)