



 Chat with AI
Exam 7: Consolidated Cash Flow Statements

Exam 1: Text Objectives and Introduction to Consolidation28 Questions
Exam 2: Principles of Consolidation42 Questions
Exam 3: Fair Value Adjustments and Tax Effects34 Questions
Exam 4: Intra-Group Transactions36 Questions
Exam 5: Non-Controlling Interest37 Questions
Exam 6: Partly-Owned Subsidiaries: Indirect Non-Controlling Interest27 Questions
Exam 7: Consolidated Cash Flow Statements25 Questions
Exam 8: Accounting for Joint Arrangements44 Questions
Exam 9: Accounting for Associates and Joint Ventures: the Equity Method37 Questions
Exam 10: Translation and Consolidation of Foreign Currency Financial Statements31 Questions
Exam 11: Segment Reporting by Diversified Entities27 Questions
Select questions type


A reconciliation of profit and cash flows is required using either the direct or indirect method of disclosing cash flows from operations
(True/False)
4.7/5  (80)
(80) A company calculates its cash flows from operating activities as profit +/- accruals.This is:
(Multiple Choice)
4.8/5 (84)
(84) Discuss the basis of classifying cash flows arising from interest paid.
(Essay)
4.9/5 (86)
(86) A company records a net profit of $220 for the year.Other information for the year: 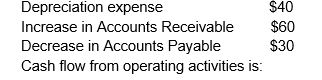
(Multiple Choice)
5.0/5 (84)
(84) The carrying amount of property plant and equipment is $1,000 at the start of the year and $1,400 at the end of the year.During the year the following occurred: Sale of equipment - carrying amount $40
Acquisition of equipment - financed by share issue $200
Depreciation expense for year $120.
Investing cash flow is:
(Multiple Choice)
5.0/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)