



 Chat with AI
Exam 5: Non-Controlling Interest

Exam 1: Text Objectives and Introduction to Consolidation28 Questions
Exam 2: Principles of Consolidation42 Questions
Exam 3: Fair Value Adjustments and Tax Effects34 Questions
Exam 4: Intra-Group Transactions36 Questions
Exam 5: Non-Controlling Interest37 Questions
Exam 6: Partly-Owned Subsidiaries: Indirect Non-Controlling Interest27 Questions
Exam 7: Consolidated Cash Flow Statements25 Questions
Exam 8: Accounting for Joint Arrangements44 Questions
Exam 9: Accounting for Associates and Joint Ventures: the Equity Method37 Questions
Exam 10: Translation and Consolidation of Foreign Currency Financial Statements31 Questions
Exam 11: Segment Reporting by Diversified Entities27 Questions
Select questions type


Preference shares of a subsidiary not owned by the parent company will be included as part of the NCI.
(True/False)
4.8/5  (91)
(91) The effect of all intra group transactions must be adjusted in calculating the NCI share of subsidiary profits.
(True/False)
4.7/5 (72)
(72) A subsidiary's recorded profits and retained earnings must be adjusted for unrealised profits prior to calculation of NCI allocation.The adjustments apply to:
(Multiple Choice)
4.7/5 (88)
(88) If A owns 80% of B and B owns 75% of C,A's ownership interest in B and C is characterised as direct.
(True/False)
4.9/5 (64)
(64) Discuss the effect of intra group transactions on the calculation of the NCI share of subsidiary profits and retained earnings
(Essay)
4.8/5 (75)
(75) The fair value method of measuring NCI includes an amount representing the non controlling shareholder's interest in goodwill.
(True/False)
4.8/5 (71)
(71) The ownership interests in a group which includes partly owned subsidiaries consist of:
(Multiple Choice)
4.8/5 (86)
(86) P Ltd purchased 80% of the issued ordinary shares of S Ltd.S Ltd capital structure is: Ordinary shares 200,000 fully paid shares x $1
Preference shares 50,000 fully paid shares x $1
Preference shares have the same rights as ordinary shares
The NCI in S Ltd is:
(Multiple Choice)
4.9/5 (80)
(80) Accounting Standard AASB3 Business combinations allows the choice of measuring NCI using either the fair value method or the proportionate interest method.
(True/False)
4.8/5 (68)
(68) Unrealised intra-group profit in opening inventory of a parent company is:
(Multiple Choice)
4.9/5 (83)
(83) The disclosure of non controlling interest proportion of each equity balance in the consolidated financial statements provides useful information on:
(Multiple Choice)
4.8/5 (92)
(92) Is the proprietary concept of consolidation is consistent with the proportional consolidation method?
(Essay)
4.9/5 (69)
(69) 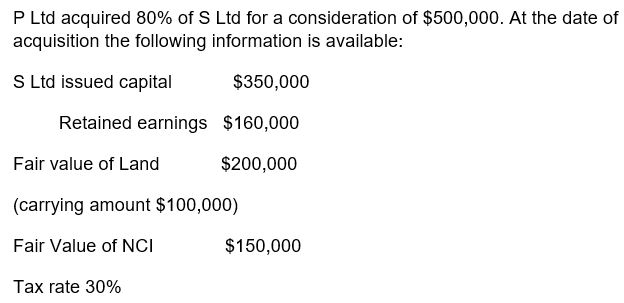 -Using the proportionate interest goodwill method,goodwill on acquisition is:
 (Multiple Choice)
4.9/5 (66)
(66) The measurement of the NCI allocation will be based on the subsidiary company's equity account balances.
(True/False)
4.8/5 (80)
(80) When an investment in a subsidiary is impaired,any impairment losses will be:
(Multiple Choice)
4.9/5 (85)
(85) Company A owns 40% of Company B and this ownership is deemed to represent control.The non controlling interest in B is:
(Multiple Choice)
4.9/5 (86)
(86) In preparing a consolidated financial report,the parent entity consolidates:
(Multiple Choice)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)