



 Chat with AI
Exam 18: Activity-Based Costing and Other Cost Management Tools

Exam 12: Corporations: Paid-In Capital and the Balance Sheet167 Questions
Exam 13: Corporations: Effects on Retained Earnings and the Income Statement164 Questions
Exam 14: The Statement of Cash Flows157 Questions
Exam 15: Financial Statement Analysis161 Questions
Exam 16: Introduction to Management Accounting161 Questions
Exam 17: Job Order and Process Costing168 Questions
Exam 18: Activity-Based Costing and Other Cost Management Tools160 Questions
Exam 19: Cost-Volume-Profit Analysis163 Questions
Exam 20: Short-Term Business Decisions164 Questions
Exam 21: Capital Investment Decisions and the Time Value of Money152 Questions
Exam 22: The Master Budget and Responsibility Accounting155 Questions
Exam 23: Flexible Budgets and Standard Costs165 Questions
Exam 24: Performance Evaluation and the Balanced Scorecard166 Questions
Select questions type


In a just-in-time costing system, any remaining balance in the conversion costs account at the end of an accounting period is usually cleared to which account?
(Multiple Choice)
4.9/5  (90)
(90) Internal failure costs occur when poor-quality goods or services are not detected until after delivery to customers.
(True/False)
4.8/5 (72)
(72) Sleep Tight Company manufactures pillows using an activity-based costing system. The following information is provided for the month of June:
Estimated Indirect Estimated Quantity of Activity Activity Costs Allocation Base Allocation Base Materials handling \ 3,150 Number of parts 4,200 parts Assembling \ 13,860 Number of parts 4,200 parts Packaging \ 2,730 Number of pillows 1,050 pillows
Each pillow consists of 4 parts, and the total direct materials cost per pillow is $3.50.
-
What is the total cost of packaging per pillow?
(Multiple Choice)
4.9/5 (75)
(75) Costs spent to avoid poor quality goods are considered internal failure costs.
(True/False)
4.9/5 (81)
(81) Pollenti Company has just merged with another industrial firm whose business had been failing. Pollenti immediately conducted a thorough study of the new company's work processes, and produced a report including the data shown below:
• A new inspection process is recommended to minimize defective raw materials. It would cost $12,000 to implement.
• Shoddy business practices are resulting in excessive warranty costs $15,000 more than normal due mainly to material failure.
• Reengineering of the assembly line will increase productivity. It would cost $18,000 to implement.
• Inefficient workplace design is costing $5,000 in unnecessary rework costs.
• Estimated amount of lost profits due to dissatisfied customers who turn to the competition is $80,000.
-
Based on the above, what is the amount of external failure costs, if any, included here?
(Multiple Choice)
4.8/5 (78)
(78) Kenney Company uses activity-based costing to account for its manufacturing process. Kenney Company produces tires, and each tire has $.50 of direct materials, includes 20 parts and requires 2 hours of machine time. There is no direct labor. Additional information follows:
Activity Allocation Base Cost Allocation Rate Materials handling Number of parts \ .16 Machining Machine hours \ 14.40 Assembling Number of parts \ .70 Packaging Number of finished units \ 5.40
-
What is the cost of assembling per tire?
(Multiple Choice)
4.9/5 (79)
(79) An activity-based costing system would be of less value to a business making a single product than it would be for a company with multiple products.
(True/False)
4.9/5 (78)
(78) Just-in-time production systems are organized into independent work cells that have all the resources needed to complete the manufacturing process.
(True/False)
4.9/5 (80)
(80) Johnson Production Company uses just-in-time production and accounting methods. On June 1, Johnson sold 200 units of product for $12.00 per unit. Each unit included $8.00 of direct materials cost and $2.00 of conversion costs. Johnson recorded the revenues of $2,400 in one entry, and then recorded the cost of goods sold in a second entry. Which of the following correctly records the cost of goods sold?
(Multiple Choice)
4.9/5 (81)
(81) Costs spent to detect poor-quality goods are considered appraisal costs.
(True/False)
4.9/5 (77)
(77) Clark Manufacturing makes blank CDs; it is a very competitive market and the company follows a target pricing strategy. Currently the market price for a unit of product (one unit equals a package of 100 CDs) is $18.00. Clark's production costs are shown below:
Direct materials $5.00 per unit
Direct labor $2.90 per unit
Indirect production costs $6.42 per unit
Non-manufacturing costs $3.20 per unit
Clark uses activity-based costing for its indirect production costs and provides the following information about this particular product: 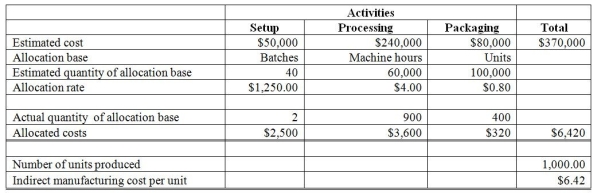 -
The company's objective is to earn 5% profit on the sales price of the product. Clark carried out a value engineering study and decided that they could make the processing activity more efficient and save costs. They have determined that if they can reduce the activity rate for the processing activity down low enough, they can hit their profit objective. What activity rate would be needed to achieve the 5% objective they seek? (Please round to nearest cent.)
-
The company's objective is to earn 5% profit on the sales price of the product. Clark carried out a value engineering study and decided that they could make the processing activity more efficient and save costs. They have determined that if they can reduce the activity rate for the processing activity down low enough, they can hit their profit objective. What activity rate would be needed to achieve the 5% objective they seek? (Please round to nearest cent.) (Multiple Choice)
4.9/5 (75)
(75) Clark Manufacturing makes blank CDs; it is a very competitive market and the company follows a target pricing strategy. Currently the market price for a unit of product (one unit equals a package of 100 CDs) is $18.00. Clark's production costs are shown below:
Direct materials $5.00 per unit
Direct labor $2.90 per unit
Indirect production costs $6.42 per unit
Non-manufacturing costs $3.20 per unit
Clark uses activity-based costing for its indirect production costs and provides the following information about this particular product: 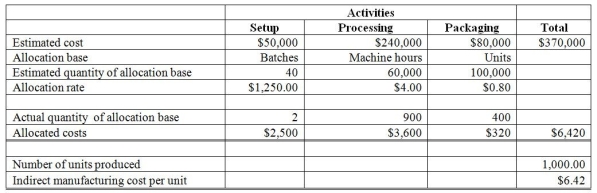 -
The company's objective is to earn 5% profit on the sales price of the product. Based on the above data, what is the company's target cost per unit?
-
The company's objective is to earn 5% profit on the sales price of the product. Based on the above data, what is the company's target cost per unit? (Multiple Choice)
4.7/5 (71)
(71) With increased competition, managers need more accurate estimates of product costs to set prices and to identify the most profitable products.
(True/False)
4.7/5 (83)
(83) Formosa Steel Products makes steel building materials for export, and uses an activity-based costing system to account for the indirect manufacturing costs of its various products. Indirect costs for the whole factory are broken down into three activities-casting, materials handling, and milling. The cost driver for casting is machine hours; the cost driver for material handling is kilograms, and the cost driver for milling is direct labor hours. Activity costs and volumes for the year were estimated as follows:
Activity Cost Volume Casting \ 2,000,000 800,000.00 Machine hours Material Handling \ 400,000 500,000.00 Kilograms Milling \ 1,120,000 140,000.00 Direct labor hours
One product is steel reinforcement rods, sold by the metric ton. Engineering reports show that one metric ton of steel reinforcement rods requires $100 of direct materials cost plus $50 of direct labor cost. Producing one metric ton of steel rods also requires 24 machine hours for casting, weighs 1,000 kilograms, and requires 15 direct labor hours.
-
What is the activity rate for the material handling activity?
(Multiple Choice)
4.8/5 (73)
(73) Just-in-time production gains economic advantage by purchasing inventory in large batches in order to get volume discounts and achieve lower manufacturing costs.
(True/False)
4.8/5 (67)
(67) Martin Manufacturers produces 3 models of industrial hammers. Martin uses the target pricing approach. The company's objective is to achieve gross profit equal to 40% of selling price. Other data are shown below:
Current production cost \ 42.50 per unit Current market price \ 60.00 per unit
What must the company do to achieve their profit goal? (Please round all amounts to the nearest cent.)
(Multiple Choice)
4.8/5 (83)
(83) Full-product cost includes all manufacturing costs plus selling expenses, but does not include administrative expenses.
(True/False)
4.8/5 (79)
(79) Sleep Tight Company manufactures pillows using an activity-based costing system. The following information is provided for the month of June:
Estimated Indirect Estimated Quantity of Activity Activity Costs Allocation Base Allocation Base Materials handling \ 3,150 Number of parts 4,200 parts Assembling \ 13,860 Number of parts 4,200 parts Packaging \ 2,730 Number of pillows 1,050 pillows
Each pillow consists of 4 parts and the total direct materials cost per pillow is $3.50.
- There is no direct labor. What is the total manufacturing cost per pillow?
(Multiple Choice)
4.7/5 (68)
(68) Sleep Tight Company manufactures pillows using an activity-based costing system. The following information is provided for the month of June:
Estimated Indirect Estimated Quantity of Activity Activity Costs Allocation Base Allocation Base Materials handling \ 3,150 Number of parts 4,200 parts Assembling \ 13,860 Number of parts 4,200 parts Packaging \ 2,730 Number of pillows 1,050 pillows
Each pillow consists of 4 parts, and the total direct materials cost per pillow is $3.50.
-
What is the total cost of materials handling and assembling for each pillow?
(Multiple Choice)
4.8/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)