



 Chat with AI
Exam 18: Intercompany Bond Holdings

Exam 1: Setting the Stage40 Questions
Exam 2: Intercorporate Equity Investments: an Introduction42 Questions
Exam 3: Business Combinations40 Questions
Exam 4: Wholly-Owned Subsidiaries: Reporting Subsequent to Acquisition37 Questions
Exam 5: Consolidation of Non-Wholly Owned Subsidiaries36 Questions
Exam 6: Subsequent-Year Consolidations: General Approach36 Questions
Exam 7: Segmented and Interim Reporting41 Questions
Exam 8: Foreign Currency Transactions and Hedges49 Questions
Exam 9: Reporting Foreign Operations43 Questions
Exam 10: Financial Reporting for Not-For-Profit Organizations46 Questions
Exam 11: Public Sector Financial Reporting41 Questions
Exam 12: Income Tax Allocation4 Questions
Exam 13: Income Tax Allocation Subsequent to Acquisition4 Questions
Exam 14: Good will Impairment Test6 Questions
Exam 15: Step Purchases6 Questions
Exam 16: Decreases in Ownership Interest4 Questions
Exam 17: Preferred and Restricted Shares of Investee Corporation5 Questions
Exam 18: Intercompany Bond Holdings6 Questions
Exam 19: Fund Accounting5 Questions
Select questions type


Soft Limited owns 70% of the shares of Hard Co.On January 1,20X5,Hard Co.issued $1,000,000 bonds payable at 6%,due in December 31,20X10.The bonds were issued for $907,542,representing a yield of 8%.The interest is paid annually on December 31.On January 1,20X6,Soft purchased $300,000 face value of the Hard bonds for $287,700 when the bonds were yielding 7%.
Required:
Both companies use the effective interest rate to amortize the bonds.Prepare the journal eliminating journal entries relating to the bonds as they would appear on the consolidated worksheet.The agency method is used.Calculate the consolidated bonds payable account at December 31,20X6,assuming there are no other bonds outstanding.

Free
(Essay)
4.9/5  (88)
(88) Correct Answer: Verified
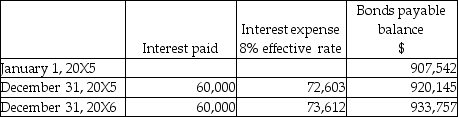
Determine bonds payable balance on Hard's books at January 1,20X6 and December 31,20X6,using the effective interest rate method.
 Balance at January 1,20X6 of $300,000 face value bonds is:
300/1,000 × $920,145 = $276,044
Balance at December 31,20X6 of $300,000 face value bonds is:
300/1000 × $933,757 = $280,127
Interest expense on $300,000 face value bonds in 20X6
300/1000 × $73,612= $22,083
Balance remaining for the $700,000 face value bonds:
700/1000 × 933,757 = $653,630
Bonds receivable balance on Soft's books,using the effective interest rate method to amortize:
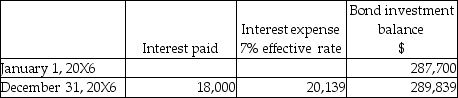 20X6: Gain on redemption of bonds at time of purchase by Soft:

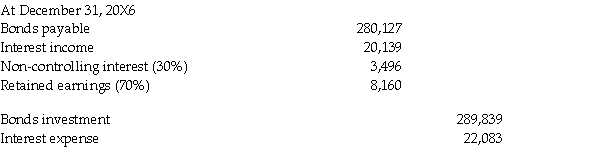 Balance in the bonds payable would be:

Basaraba Ltd.owns 75% of the outstanding common shares of Gill Ltd.Gill purchased all of Basaraba's outstanding bond issue on the open market at a discount.The bonds have an unamortized premium attached.This transaction,in effect,retires the bond and results in a gain.Under the par-value approach to dealing with a gain on elimination of intercompany bond holdings,which of the following statements is true?
Free
(Multiple Choice)
4.7/5 (63)
(63) Correct Answer:Verified
VerifiedC
A subsidiary has purchased some bonds from its parent company.Under the par-value method,the non-controlling interest is allocated its share of the difference between ________.
Free
(Multiple Choice)
4.9/5 (82)
(82) Correct Answer:Verified
VerifiedB
Gill Ltd.is the wholly-owned subsidiary of Basaraba Ltd.Gill purchased all of Basaraba's outstanding bond issue on the open market at a discount.The bonds have an unamortized premium attached.This transaction,in effect,retires the bond and results in a gain.How should the gain be shown?
(Multiple Choice)
4.8/5 (68)
(68) For gains on intercompany bond holdings,which method of allocating the gain emphasizes substance over form?
(Multiple Choice)
4.7/5 (84)
(84) Basaraba Ltd.owns 75% of the outstanding common shares of Gill Ltd.Gill purchased all of Basaraba's outstanding bond issue on the open market at a discount.The bonds have an unamortized premium attached.This transaction,in effect,retires the bond and results in a gain.Under the par-value approach to dealing with a gain on elimination of intercompany bond holdings,which of the following statements is true?
(Multiple Choice)
4.7/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)