



 Chat with AI
Exam 14: Income Taxation of Trusts and Estates

Exam 1: Tax Research114 Questions
Exam 2: Corporate Formations and Capital Structure123 Questions
Exam 3: The Corporate Income Tax127 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies103 Questions
Exam 6: Corporate Liquidating Distributions103 Questions
Exam 7: Corporate Acquisitions and Reorganizations100 Questions
Exam 8: Consolidated Tax Returns99 Questions
Exam 9: Partnership Formation and Operation115 Questions
Exam 10: Special Partnership Issues107 Questions
Exam 11: US Corporations103 Questions
Exam 12: The Gift Tax105 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates105 Questions
Exam 15: Administrative Procedures104 Questions
Exam 16: Us Taxation of Foreign-Related Transactions97 Questions
Select questions type


Outline the classification of principal and income under the Revised Uniform Principal and Income Act.
(Essay)
4.8/5  (81)
(81) A trust must distribute all of its income annually.Capital gains are allocated to principal.The trust has dividend income of $12,000,capital gains of $6,000,and no expenses.Calculate the trust's taxable income.
(Essay)
4.9/5 (80)
(80) A trust distributes 30% of its income to Mark and 20% to Nancy.The remaining 50% is accumulated.The trust's depreciation is $1,000.The trust instrument is silent regarding the depreciation deduction.State law requires the depreciation be charged to principal.What part of the depreciation deduction will be allocated to Mark?
(Multiple Choice)
4.9/5 (76)
(76) Describe the double taxation of income in respect of a decedent and how it can be reduced.
(Essay)
4.9/5 (78)
(78) A trust has the following results:
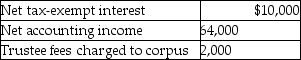 The Uniform Act is followed.The trust document requires one-fifth of the income to be distributed annually to David and the remainder of the income to Patty.What is distributable net income?
 (Multiple Choice)
4.8/5 (98)
(98) The $3,000 limitation on deducting net capital losses does not apply to a trust.
(True/False)
4.8/5 (87)
(87) An example of income in respect to a decedent (IRD)for a cash method of accounting taxpayer is
(Multiple Choice)
4.9/5 (79)
(79) Which of the following is not an addition to trust taxable income when computing distributable net income (DNI)?
(Multiple Choice)
4.8/5 (92)
(92) Texas Trust receives $10,000 interest on U.S.Treasury bonds and $15,000 interest on State of New York bonds.All $25,000 is distributed to the trust beneficiary,Gary.Which of the following statements is correct?
(Multiple Choice)
4.8/5 (80)
(80) A trust document does not mention the treatment for depreciation.The state has adopted the Uniform Act.The trust document states that depreciation is a charge against corpus.The trust results are the following: 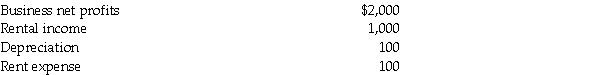 Calculate net accounting income.
 (Essay)
4.8/5 (79)
(79) A tax entity,often called a fiduciary,includes all of the following except
(Multiple Choice)
4.7/5 (81)
(81) A trust has net accounting income of $15,000.In addition,the trust has a $10,000 capital gain,which is not included in net accounting income.The trust is required to distribute the trust income to the beneficiary.The beneficiary will receive
(Multiple Choice)
4.8/5 (85)
(85) Martha died and by her will,specifically bequeathed,and the executor distributed,$20,000 cash and a $70,000 house to Harold.The distributions were made in a year in which the estate had $65,000 of DNI,all from taxable sources.The maximum Harold will be required to report as gross income as a result of these distributions is
(Multiple Choice)
4.7/5 (87)
(87) Little Trust,whose trust instrument is silent with respect to depreciation,collects rental income of $20,000 and pays property taxes of $1,000.Depreciation expense is $5,000.
Little Trust is in a state where all depreciation is charged to principal.What is the trust's net accounting income?
(Essay)
4.9/5 (60)
(60) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)