



 Chat with AI
Exam 8: Property, Plant, and Equipment

Exam 1: Fundamentals of Financial Accounting Theory33 Questions
Exam 2: Conceptual Frameworks for Financial Reporting60 Questions
Exam 3: Accrual Accounting159 Questions
Exam 4: Revenue Recognition110 Questions
Exam 5: Cash and Receivables120 Questions
Exam 6: Inventories156 Questions
Exam 7: Financial Assets141 Questions
Exam 8: Property, Plant, and Equipment127 Questions
Exam 9: Intangible Assets, Goodwill, Mineral Resources, and Government Grants81 Questions
Exam 10: Applications of Fair Value to Non-Current Assets120 Questions
Select questions type


Base-Forward owns a machine that it purchased on Jan 1, 2010 for $600,000. The machine had an estimated useful life of 5 years and an estimated residual value of $100,000. The company uses the declining balance method with a rate of 20%. The machine was sold on December 31, 2012 for $140,000. What was the depreciation expense for 2012?
(Multiple Choice)
4.8/5  (78)
(78) Grape Company (GC)had been renting an office building for several years. On January 1, 2013, GC decided to have a new office building constructed. On that date, it acquired land with an abandoned warehouse on it for $350,000. Other costs included the following:
 Required:
a. Calculate at what amount GC should record the (i)land and (ii)building.
b. Assume that the building was completed and occupied on December 31, 2013. It has an estimated useful life of 40 years, with residual value of $140,000. Calculate depreciation for 2014 using (i)the straight-line method and (ii)the double declining balance method.
c. Assume that management decided to use straight-line depreciation for the building. By 2017 GC had
grown considerably and needed to relocate for more space; it sold the land and building to Macaw Company on July 1, 2017 for $1,350,000. Assume depreciation expense has already been recorded for the first six months of the year (Jan. 1, 2017 to June 30, 2017). Prepare all journal entries required relating to the land and building accounts on July 1, 2017.
Required:
a. Calculate at what amount GC should record the (i)land and (ii)building.
b. Assume that the building was completed and occupied on December 31, 2013. It has an estimated useful life of 40 years, with residual value of $140,000. Calculate depreciation for 2014 using (i)the straight-line method and (ii)the double declining balance method.
c. Assume that management decided to use straight-line depreciation for the building. By 2017 GC had
grown considerably and needed to relocate for more space; it sold the land and building to Macaw Company on July 1, 2017 for $1,350,000. Assume depreciation expense has already been recorded for the first six months of the year (Jan. 1, 2017 to June 30, 2017). Prepare all journal entries required relating to the land and building accounts on July 1, 2017. (Essay)
4.8/5 (82)
(82) What does a "gain on disposal of property, plant and equipment" mean? Does a gain suggest good or excellent management and a loss on disposal indicate poor management? Explain your conclusion.
(Essay)
4.8/5 (81)
(81) Francisco purchased a machine on Jan 1, 2010 for $750,000. The machine had an estimated useful life of 5 years and an estimated residual value of $50,000. The company uses straight-line depreciation and records monthly depreciation. The machine was sold on December 31, 2013 for $140,000. What was the gain/loss on disposal of the machine?
(Multiple Choice)
4.8/5 (88)
(88) When is property, plant, and equipment (PPE)not derecognized?
(Multiple Choice)
4.8/5 (70)
(70) Zach Co. Ltd. was incorporated on January 2, 2012, but was unable to begin their manufacturing operations immediately. The new factory facilities became available for use on July 1, 2012. During the start-up period, the company provisionally used a "Land and Factory Building" account to record the following transactions, in chronological order:
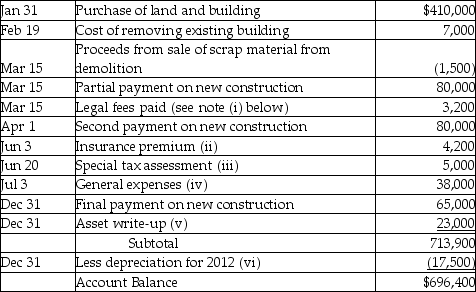 Additional info
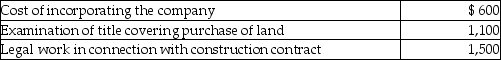
i. Legal fees of $3,200 covered the following:
 ii. Insurance covered the building for a one-year term beginning April 1, 2012.
iii. The special tax assessment covered repaving the street in front of the building.
iv. General expenses covered the following for the period January 2, 2012 to June 30, 2012.
 v. The board of directors increased the value of the building by $23,000, believing that such an increase was justified to reflect the current market at the time the building was completed; Retained Earnings was credited for this amount.
vi. Engineers estimate the useful life of the building to be 40 years. The company believes that the declining balance method at a 5% rate is appropriate. The company's policy for new PPE is to depreciate the assets according to the time available for use in the fiscal year, rounded to the closest month.
Required:
Prepare entries to reflect correct land, factory building, and accumulated depreciation accounts at December 31, 2012. Round values to the nearest dollar, if necessary.
Additional info
i. Legal fees of $3,200 covered the following:
ii. Insurance covered the building for a one-year term beginning April 1, 2012.
iii. The special tax assessment covered repaving the street in front of the building.
iv. General expenses covered the following for the period January 2, 2012 to June 30, 2012.
v. The board of directors increased the value of the building by $23,000, believing that such an increase was justified to reflect the current market at the time the building was completed; Retained Earnings was credited for this amount.
vi. Engineers estimate the useful life of the building to be 40 years. The company believes that the declining balance method at a 5% rate is appropriate. The company's policy for new PPE is to depreciate the assets according to the time available for use in the fiscal year, rounded to the closest month.
Required:
Prepare entries to reflect correct land, factory building, and accumulated depreciation accounts at December 31, 2012. Round values to the nearest dollar, if necessary. (Essay)
4.9/5 (84)
(84) Which question arises at the time property, plant, and equipment is derecognized?
(Multiple Choice)
4.9/5 (80)
(80) Ceila Manufacturing purchased equipment on January 1, 2012 for $275,000. It was estimated that the equipment would have a residual value of $25,000 at the end of its useful life. The asset's useful life was estimated at 5 years or 10,000 units of output. The company has a December 31 year end. Assuming the company uses the double-declining-balance depreciation method, what is the depreciation expense for 2012?
(Multiple Choice)
4.9/5 (88)
(88) The following entry was recorded by Williams Inc.:  What is the effect of this entry on the financial statements?
 (Multiple Choice)
4.9/5 (72)
(72) A car rental company has a fleet of 32,000 cars. Every three months all the cars are given scheduled oil changes, rotation, and replacement of small components. The cost per car is $210, ($70 in parts and $140 for the wages of the in-house mechanics), $6,720,000 in total. As well, for half of the cars a satellite radio receiver was installed at a cost of $150 each (total $2,400,000). The gadget allows the car to receive satellite radio. The company will provide this service free and promote it heavily to increase rentals. This advertising campaign will cost $1,500,000. After the original free use of the satellite feature, the company will charge later users a fee for the use of satellite radio.
Prepare the necessary journal entry to record the above transactions. Provide a short justification for your chosen treatment.
(Essay)
4.8/5 (86)
(86) Coffee-Bean Company built two similar buildings. Each building took one year to build and required $25 million in construction costs. Given the Company's limited internal financial resources, only Building Hazel could be internally financed; Building Cinnamon was financed by a $20 million loan evenly over the year (i.e., zero at the beginning and increasing to $20 million by the end of the year). The interest rate on the loan is 8%.
Both projects were finished on December 31, 2013 and were ready for occupancy immediately. The Hazel building will have an estimated useful life of 30 years while the Cinnamon building will have an expected useful life of 40 years. Neither value will have a residual value. The Company uses the straight-line method for depreciation.
Required:
a. How much interest cost can be capitalized on Building Cinnamon?
b. What will be the annual depreciation expense for each of the two buildings?
c. ASPE allows interest capitalization while IFRS recommends capitalization of interest on construction-specific loans. Ignoring the complexities of how to determine how much interest to capitalize, which treatment of interest costs is conceptually more correct? Explain your conclusion.
d. Why can interest costs not continue to be capitalized after the self-construction period is completed?
(Essay)
4.9/5 (76)
(76) Fantasy Limited purchased equipment on January 1, 2009 for $275,000. The asset's useful life was estimated at 5 years or 10,000 units of output, with no residual value. The company has a December 31 year end. Additional Information
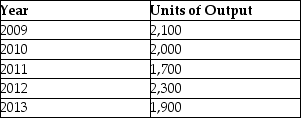 Assuming the company uses the units-of-production depreciation method, what is the depreciation expense for 2009?
 (Multiple Choice)
4.8/5 (63)
(63) ReelGood Corp. purchased equipment on January 1, 2012 for $275,000. It was estimated that the equipment would have a residual value of $25,000 at the end of its useful life. The asset's useful life was estimated at 5 years or 10,000 units of output. The company has a December 31 year end. Assuming the double-declining-balance depreciation method is used, what is the net book value (carrying value)of the asset on December 31, 2012?
(Multiple Choice)
4.8/5 (80)
(80) Seall-Test Ltd. owns a machine that it purchased on Jan 1, 2010 for $600,000. The machine had an estimated useful life of 10 years and an estimated residual value of $100,000. The company uses the declining balance method with a rate of 20%. The machine was sold on December 31, 2012 for $140,000. What was the depreciation expense for 2011?
(Multiple Choice)
4.8/5 (83)
(83) On January 1, 2012, Pheta Company purchased a machine for $114,000. It has an estimated four-year life and a residual value of $45,000. The machine is expected to be used for a total of 4,600 hours over the four years. During 2012, it was used for 1,900 hours.
Required:
How much is the depreciation expense for 2012 under the units-of-production method?
(Essay)
4.9/5 (77)
(77) On March 31, 2013, a machine costing $3,000,000 was acquired. The company estimates that the asset will have an estimated useful life of five years and a residual value of $450,000. On April 1, 2018, the asset is sold for $550,000. The company uses the declining balance method at a rate of 40%. The company has a December 31 year-end. The company records partial depreciation in the year of acquisition or disposal based on the number of months the asset is available for use in the year.
Prepare the entries to record depreciation expense for 2013 and 2014, and all entries required for 2018 as they relate to this asset.
(Essay)
4.9/5 (83)
(83) Polar Sky Railway (PSR), a transportation company, has substantial investments in property, plant, and equipment. In 2011, the company exchanged some of these assets with other companies. [Note: any depreciation expense prior to the following transaction has already been properly recorded.] PSR is trying to expand its business in transportation beyond rail, so the company traded some railcars in return for several trucks. On PSR's books, the railcars had a cost of $12 million, accumulated depreciation of $9 million, and fair value of $6 million. The trucks had a fair value of $5.9 million and were recorded on the seller's books at a cost of $4 million and accumulated depreciation of $1 million. No cash was involved in this exchange.
Required:
Record the journal entry for the above transaction on PSR's books. State your reason(s)for the chosen accounting method.
(Essay)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)