



 Chat with AI
Exam 10: Accounting Changes

Exam 1: Current Liabilities and Contingencies101 Questions
Exam 2: Non-Current Financial Liabilities109 Questions
Exam 3: Equities106 Questions
Exam 4: Complex Financial Instruments111 Questions
Exam 5: Earnings Per Share113 Questions
Exam 6: Accounting for Income Taxes118 Questions
Exam 7: Pensions and Other Employee Future Benefits98 Questions
Exam 8: Accounting for Leases124 Questions
Exam 9: Statement of Cash Flows87 Questions
Exam 10: Accounting Changes66 Questions
Select questions type


What is the essential characteristic that distinguishes a change in accounting policy from either an error correction or a change in estimate?
(Essay)
4.8/5  (77)
(77) Which statement is correct about a correction of an error from prior periods?
(Multiple Choice)
4.7/5 (88)
(88) Canlan Inc.is a subsidiary of a Canadian publicly traded manufacturer of construction materials.The company uses the first-in,first-out (FIFO)cost flow assumption.
a.An invoice for $55,000 of material received and used in production arrived after the year-end.Neither the purchase nor the accounts payable was recorded until year two.However,the amount of raw materials in ending inventory was correct based on the inventory count.
b.One of Canlan's products became obsolete and worthless during Year 1,but the inventory writedown did not occur until Year 2.The cost of this inventory was $225,000.
c.In the Year 1 closing inventory count,employees improperly included 2,000 units of finished goods that had already been sold to customers.These units had a cost of $20,000 under FIFO.
Required:
For each of the above independent scenarios (a)through (c),indicate in the following table the effect of the accounting errors on the books of Canlan Inc.Specifically,identify the amount and direction of over- or understatement of inventory and income for Year 1 and Year 2.If an account requires no adjustment,indicate that the account is "correct."
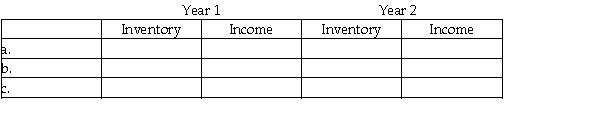
(Essay)
4.8/5 (74)
(74) Victory Welding Company overhauled a printing press for Helman's Printing Ltd.For the services completed on March 31,2018,Victory received a promissory note for $350,000 due and payable on March 31,2019.Helman's paid the amount as scheduled.Victory staff recorded the full amount as revenue on March 31,2018.
It is now May 20,2019.The accounting staff at Victory just realized that the note was improperly recorded,and that no interest income had been recognized.The controller believes that an interest rate of 10% would be appropriate.
Required:
Record any journal entries necessary to correct Victory's accounts in relation to the note receivable from Helman's.
(Essay)
4.8/5 (84)
(84) Why is the prospective treatment conceptually appropriate for changes in estimates?
(Essay)
4.9/5 (86)
(86) CBC Biomedical undertook a research and development project in 2016.As of March 1 of that year,management concluded that the project had met the requirements for the capitalization of development costs.For the remainder of 2016 and 2017,the company capitalized $4.3 million of development costs for the project.Capitalizing these costs helped CBC Biomedical to remain profitable; had these costs been expensed,the company would report losses.In 2018,CBC Biomedical began amortizing the development cost over the estimated useful life of 10 years,beginning with a full year of amortization in 2018.
In 2021,in preparation for an initial public offering (IPO),the company engaged a public accounting firm to conduct an external audit of its financial statements.The auditors concluded that the development cost did not meet the criteria for capitalization.Specifically,it is their opinion that CBC Biomedical,at the time,did not demonstrate that the company had sufficient financial resources to complete the development project due to the recurring operating losses incurred.After some heated debate,CBC Biomedical management agreed with the auditors' position in order to obtain an unqualified audit opinion.The company had not yet recorded any amortization for 2021 when it agreed to correct the error.The company's tax rate is 30%.
Required:
Record the journal entries necessary to correct CBC's accounts.Include the effect of income taxes.
(Essay)
4.8/5 (72)
(72) What types of accounting changes are treated retrospectively and why?
(Essay)
4.7/5 (71)
(71) Albacore Sailboats manufactures small sailing dinghies.In 2019,the company's accountant recorded the following costs into the inventory account:
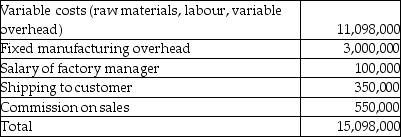 The company had no work in process at the end of both 2018 and 2019.Finished goods at the end of 2018 amounted to 6,000 sailboats at $300/boat.Production was 50,000 sailboats and 4,000 boats remained in inventory at December 31,2019.The company uses a periodic inventory system and the FIFO cost flow assumption.
Required:
a.Of the $15,098,000,how much should have been capitalized into inventories?
b.Compute the ending value of inventory and the cost of goods sold for 2019.
c.If the error in inventory costing had not been corrected as per part (a),by how much would inventory be overstated at the end of 2019?
d.Record the journal entry to correct the error in inventory costing.
The company had no work in process at the end of both 2018 and 2019.Finished goods at the end of 2018 amounted to 6,000 sailboats at $300/boat.Production was 50,000 sailboats and 4,000 boats remained in inventory at December 31,2019.The company uses a periodic inventory system and the FIFO cost flow assumption.
Required:
a.Of the $15,098,000,how much should have been capitalized into inventories?
b.Compute the ending value of inventory and the cost of goods sold for 2019.
c.If the error in inventory costing had not been corrected as per part (a),by how much would inventory be overstated at the end of 2019?
d.Record the journal entry to correct the error in inventory costing. (Essay)
4.8/5 (84)
(84) During the audit of Keats Island Brewery for the fiscal year-ended June 30,2018,the auditors identified the following issues:
For each of the three issues described below,using the following table,identify both the direction (increase or decrease)and the amount of the effect relative to the amount without the accounting change.
a.The company sells beer for $1 each plus $0.10 deposit on each bottle.The deposit collected is payable to the provincial recycling agency.During 2017,the company had recorded $12,000 of deposits as revenue.The auditors believe this amount should have been recorded as a liability.
b.The company had been using the first-in,first-out cost flow assumption for its inventories.In fiscal 2018,management decided to switch to the weighted-average method.This change reduced inventory by $25,000 at June 30,2017,and $40,000 at June 30,2018.
c.The company has equipment costing $6,000,000 that it has been depreciating over 10 years on a straight-line basis.The depreciation for fiscal 2017 was $600,000 and accumulated depreciation on
June 30,2017,was $1,200,000.During 2018,management revises the estimate of useful life to 12 years,reducing the amount of depreciation to $480,000 per year.
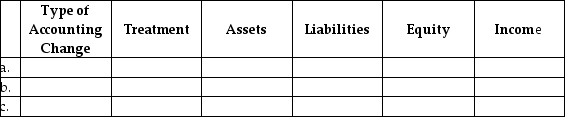
(Essay)
4.9/5 (71)
(71) Anfield Corp.is analyzing its accounts receivable for purposes of preparing its second- quarter financial report for June 30,2017.For interim reporting,the company uses the percentage-of-sales method to estimate bad debts.During this analysis,Anfield identified an account for $42,000 that should have been written off in the first quarter ended March 31,2017 but was actually written off in May 2017.
The following table provides information relating to Anfield accounts receivables after recording the provision for bad debts for the quarter but prior to the discovery of the $42,000 error:
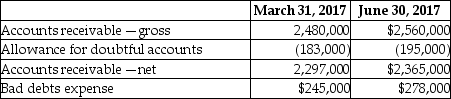 Required:
Record any adjusting journal entries necessary to correct the error in Anfield's accounts receivable.
Required:
Record any adjusting journal entries necessary to correct the error in Anfield's accounts receivable. (Essay)
4.8/5 (80)
(80) Give an example of a change in accounting policy which does not require retrospective treatment and explain why.
(Essay)
4.9/5 (74)
(74) What is the essential characteristic that distinguishes an error correction from a change in estimate?
(Essay)
4.8/5 (81)
(81) Why are retrospective adjustments to past years' income and expenses recorded directly in retained earnings?
(Essay)
4.9/5 (93)
(93) Star Company Ltd.,is a private company that started on January 1,2017.During an external audit that was conducted at the end of the second year of the company's operation (2018),the following information was presented:
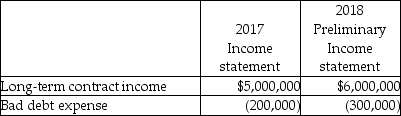 The company used the completed contract method for revenue recognition in 2017.Management now believes that the percentage of completion method would be better.If the percentage of completion method had been used,the incomes for 2017 and 2018 would have been $5,500,000 and $5,700,000 respectively.
The accounts receivable on December 31,2017 included a $50,000 account that was not provided for but subsequently was written off during 2018 as the customer went bankrupt after the issuance of the financial statements.Star Company would like to adjust 2017 for this oversight as it sees this as an error.
Required:
a.As the auditor on this engagement,what is your recommended treatment for each of these matters in terms of whether they are errors,changes in accounting policy,changes in estimate? Explain your conclusion.
b.Assume that management of Star Company agrees with your recommendations.How would the balances above be presented in the corrected income statements for 2017 and 2018?
The company used the completed contract method for revenue recognition in 2017.Management now believes that the percentage of completion method would be better.If the percentage of completion method had been used,the incomes for 2017 and 2018 would have been $5,500,000 and $5,700,000 respectively.
The accounts receivable on December 31,2017 included a $50,000 account that was not provided for but subsequently was written off during 2018 as the customer went bankrupt after the issuance of the financial statements.Star Company would like to adjust 2017 for this oversight as it sees this as an error.
Required:
a.As the auditor on this engagement,what is your recommended treatment for each of these matters in terms of whether they are errors,changes in accounting policy,changes in estimate? Explain your conclusion.
b.Assume that management of Star Company agrees with your recommendations.How would the balances above be presented in the corrected income statements for 2017 and 2018? (Essay)
4.9/5 (82)
(82) For each of the following independent scenarios,indicate the effect of the error (if any)on:
i.2017 net income
ii.2018 net income
iii.2018 closing retained earnings
The company uses the periodic system of inventory and its fiscal year-end is
December 31.Ignore income tax effects.
a)Invoices in the amount of $42,000 for inventory received in December 2017 were not entered on the books in 2017.They were recorded as purchases in January 2018 when they were paid.The goods were counted in the 2017 inventory count and included in ending inventory on the 2017 financial statements.
b)Goods received on consignment amounting to $73,000 were included in the physical count of goods at the end of 2018 and included in ending inventory on the 2018 financial statements.
c)Your analysis of inventory indicates that inventory at the end of 2017 was overstated by $152,000 due to an inventory count error.Inventory at the end of 2018 was correctly stated.
d)Provide the journal entry in 2018 to correct the error for (a)to (c).
(Essay)
4.9/5 (86)
(86) Stretton Company Limited,a private company,was started on January 1,2018.For the first year,the chief accountant prepared the financial statements and a local accountant completed the necessary review of these statements.However,for the year ended December 31,2019,an external auditor was appointed.The income statement for 2018 and the preliminary amounts for 2019 are as follows:
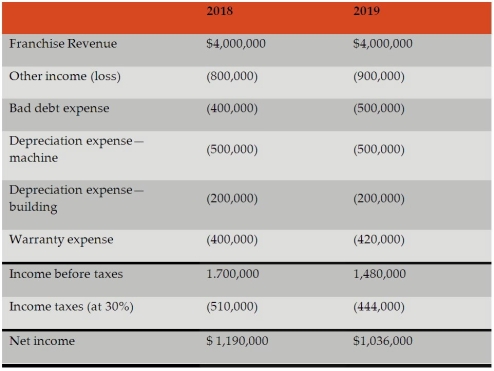 In the process of examining the accounting records the auditor noted the following issues:
Franchise Revenue: The Stretton Company signed a franchise agreement to allow a franchisee to operate in a specific area for 10 years.The agreement required the franchisee to pay $4,000,000 initially with a royalty of 2% of sales revenue thereafter.In 2018,the 2% of sales revenue was recorded correctly by Stretton Company.However,management recorded the entire $4,000,000 as having been earned in 2018.In 2019,management realized that 40% of the $4,000,000 pertained to ongoing services to be provided over the next ten years.
Accounts receivable: The Stretton Company uses the aging method to estimate bad debts.During 2019,it was discovered that staff had written off a $103,000 account in 2019,even though the company had received information about the bankruptcy of the client in late 2018.
Machine impairment: Stretton Company has one machine that cost $5,000,000 with a useful life of 10 years and has been depreciated on a straight-line basis for 4 years,including 2019.Stretton carries this asset under the revaluation model and its auditors find that the machine should have been written down for impairments by $450,000 in 2018.No impairment has been recorded by Stretton in 2018 or 2019.
Building depreciation: The company's building (cost $4,000,000,estimated salvage value $0,useful life 20 years)was depreciated last year using the straight line method.The company and the auditor now agree that 10% declining-balance method would be a more appropriate method to use.A depreciation provision of $200,000 has been made for 2018.
Inventories: The accountant failed to apply the lower of cost and net realizable value test to ending inventory in 2018.Upon review,the inventory balance for 2019 should have been reduced by $200,000.The closing inventory allowance balance for 2019 should be $400,000.No entry has been made for this matter.
Warranties: Stretton Company does not accrue for warranties; rather,it records the warranty expense when amounts are paid.Stretton provides a one-year warranty for defective goods.Payments to satisfy warranty claims in 2018 were $400,000,and $420,000 in 2019.Out of the $420,000 paid in 2019,$250,000 related to 2018 sales.A reasonable estimate of warranties payable at the end of 2019 is $375,000.There is nothing relating to 2018 warranty claims left owing at the end of 2019.
Required:
a.As the audit senior on this engagement,what is your recommended treatment for each of these matters in terms of whether they are errors,changes in accounting policy,or changes in estimate? Explain your conclusion.
b.Assume that management of Stretton Company agrees with your recommendations.Prepare the corrected statements of comprehensive income for 2018 and 2019.
In the process of examining the accounting records the auditor noted the following issues:
Franchise Revenue: The Stretton Company signed a franchise agreement to allow a franchisee to operate in a specific area for 10 years.The agreement required the franchisee to pay $4,000,000 initially with a royalty of 2% of sales revenue thereafter.In 2018,the 2% of sales revenue was recorded correctly by Stretton Company.However,management recorded the entire $4,000,000 as having been earned in 2018.In 2019,management realized that 40% of the $4,000,000 pertained to ongoing services to be provided over the next ten years.
Accounts receivable: The Stretton Company uses the aging method to estimate bad debts.During 2019,it was discovered that staff had written off a $103,000 account in 2019,even though the company had received information about the bankruptcy of the client in late 2018.
Machine impairment: Stretton Company has one machine that cost $5,000,000 with a useful life of 10 years and has been depreciated on a straight-line basis for 4 years,including 2019.Stretton carries this asset under the revaluation model and its auditors find that the machine should have been written down for impairments by $450,000 in 2018.No impairment has been recorded by Stretton in 2018 or 2019.
Building depreciation: The company's building (cost $4,000,000,estimated salvage value $0,useful life 20 years)was depreciated last year using the straight line method.The company and the auditor now agree that 10% declining-balance method would be a more appropriate method to use.A depreciation provision of $200,000 has been made for 2018.
Inventories: The accountant failed to apply the lower of cost and net realizable value test to ending inventory in 2018.Upon review,the inventory balance for 2019 should have been reduced by $200,000.The closing inventory allowance balance for 2019 should be $400,000.No entry has been made for this matter.
Warranties: Stretton Company does not accrue for warranties; rather,it records the warranty expense when amounts are paid.Stretton provides a one-year warranty for defective goods.Payments to satisfy warranty claims in 2018 were $400,000,and $420,000 in 2019.Out of the $420,000 paid in 2019,$250,000 related to 2018 sales.A reasonable estimate of warranties payable at the end of 2019 is $375,000.There is nothing relating to 2018 warranty claims left owing at the end of 2019.
Required:
a.As the audit senior on this engagement,what is your recommended treatment for each of these matters in terms of whether they are errors,changes in accounting policy,or changes in estimate? Explain your conclusion.
b.Assume that management of Stretton Company agrees with your recommendations.Prepare the corrected statements of comprehensive income for 2018 and 2019. (Essay)
4.9/5 (87)
(87) Sampson Jet Skis manufactures state-of-the-art jet skis.In 2015,the company's accountant recorded the following costs into the inventory account:
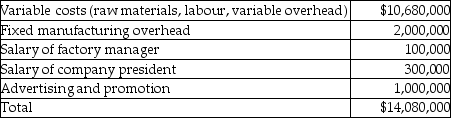 The company had no work in process at the end of both 2014 and 2015.Finished goods at the end of 2014 amounted to 8,000 jet skis at $900/jet ski.Production was 13,453 jet skis and 4,000 jet skis remained in inventory at December 31,2015.The company uses a periodic inventory system and the FIFO cost flow assumption.
Required:
a.Of the $14,080,000,how much should have been capitalized into inventories?
b.Compute the ending value of inventory and the cost of goods sold for 2015.
c.If the error in inventory costing had not been corrected as per part (a),by how much would inventory be overstated at the end of 2015?
d.Record the journal entry to correct the error in inventory costing.
e.If the company uses the weighted-average cost method,how much would be the ending value of inventory and cost of goods sold for 2015?
The company had no work in process at the end of both 2014 and 2015.Finished goods at the end of 2014 amounted to 8,000 jet skis at $900/jet ski.Production was 13,453 jet skis and 4,000 jet skis remained in inventory at December 31,2015.The company uses a periodic inventory system and the FIFO cost flow assumption.
Required:
a.Of the $14,080,000,how much should have been capitalized into inventories?
b.Compute the ending value of inventory and the cost of goods sold for 2015.
c.If the error in inventory costing had not been corrected as per part (a),by how much would inventory be overstated at the end of 2015?
d.Record the journal entry to correct the error in inventory costing.
e.If the company uses the weighted-average cost method,how much would be the ending value of inventory and cost of goods sold for 2015? (Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)