



 Chat with AI
Exam 3: An Introduction to Consolidated Financial Statements

Exam 1: Business Combinations36 Questions
Exam 2: Stock Investments Investor Accounting and Reporting40 Questions
Exam 3: An Introduction to Consolidated Financial Statements39 Questions
Exam 4: Consolidated Techniques and Procedures38 Questions
Exam 5: Intercompany Profit Transactions - Inventories40 Questions
Exam 6: Intercompany Profit Transactions - Plant Assets39 Questions
Exam 7: Intercompany Profit Transactions - Bonds39 Questions
Exam 8: Consolidations - Changes in Ownership Interests38 Questions
Exam 9: Indirect and Mutual Holdings37 Questions
Exam 10: Subsidiary Preferred Stock, consolidated Earnings Per Share, and Consolidated Income Taxation35 Questions
Exam 11: Consolidation Theories, push-Down Accounting, and Corporate Joint Ventures40 Questions
Exam 12: Derivatives and Foreign Currency: Concepts and Common Transactions40 Questions
Exam 13: Accounting for Derivatives and Hedging Activities40 Questions
Exam 14: Foreign Currency Financial Statements39 Questions
Exam 15: Segment and Interim Financial Reporting40 Questions
Exam 16: Partnerships - Formation,operations,and Changes in Ownership Interests39 Questions
Exam 17: Partnership Liquidation40 Questions
Exam 18: Corporate Liquidations and Reorganizations38 Questions
Exam 19: An Introduction to Accounting for State and Local Governmental Units38 Questions
Exam 20: Accounting for State and Local Governmental Units - Governmental Funds37 Questions
Exam 21: Accounting for State and Local Governmental Units - Proprietary and Fiduciary Funds39 Questions
Exam 22: Accounting for Not-For-Profit Organizations39 Questions
Exam 23: Estates and Trusts38 Questions
Select questions type


What method must be used if FASB Statement No.94 prohibits full consolidation of a 70% owned subsidiary?

Free
(Multiple Choice)
4.8/5  (76)
(76) Correct Answer: Verified
D
Passerby International purchased 80% of Standaround Company's outstanding common stock for $200,000 on January 2,2011.At that time,the fair value of Standaround's net assets were equal to the book values.The balance sheets of Passerby and Standaround at January 2,2011 are summarized as follows:
 Required: Determine the consolidated balances as of January 2,2011 for the following five balance sheet line items: Goodwill,Liabilities,Capital Stock,Retained Earnings,and Noncontrolling Interest.
Free
(Essay)
4.9/5 (81)
(81) Correct Answer:Verified
Verified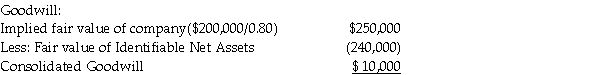
Liabilities:$840,000 + 230,000 = 1,070,000
Capital Stock:$360,000
Retained Earnings:$400,000
Noncontrolling interest:Implied fair value of Standaround at date of purchase (see Goodwill calculation)= $250,000 × 20% = $50,000
On June 1,2011,Puell Company acquired 100% of the stock of Sorrell Inc.On this date,Puell had Retained Earnings of $100,000 and Sorrell had Retained Earnings of $50,000.On December 31,2011,Puell had Retained Earnings of $120,000 and Sorrell had Retained Earnings of $60,000.The amount of Retained Earnings that appeared in the December 31,2011 consolidated balance sheet was
(Multiple Choice)
4.7/5 (82)
(82) Polaris Incorporated purchased 80% of The Solar Company on January 2,2011,when Solar's book value was $800,000.Polaris paid $700,000 for their acquisition,and the fair value of noncontrolling interest was $175,000.At the date of acquisition,the fair value and book value of Solar's identifiable assets and liabilities were equal.At the end of the year,the separate companies reported the following balances:
 Requirement 1: Calculate consolidated balances for each of the accounts as of December 31,2011.
Requirement 2: Assuming that Solar has paid no dividends during the year,what is the ending balance of the noncontrolling interest in the subsidiary?
Requirement 1: Calculate consolidated balances for each of the accounts as of December 31,2011.
Requirement 2: Assuming that Solar has paid no dividends during the year,what is the ending balance of the noncontrolling interest in the subsidiary? (Essay)
4.8/5 (78)
(78) Subsequent to an acquisition,the parent company and consolidated financial statement amounts would not be the same for
(Multiple Choice)
4.8/5 (70)
(70) Pool Industries paid $540,000 to purchase 75% of the outstanding stock of Swimmin Corporation,on December 31,2011.Any excess fair value over the identified assets and liabilities is attributed to goodwill.The following year-end information was available just before the purchase:
 Required:
1.Prepare Pool's consolidated balance sheet on December 31,2011.
Required:
1.Prepare Pool's consolidated balance sheet on December 31,2011. (Essay)
4.9/5 (69)
(69) Petra Corporation paid $500,000 for 80% of the outstanding voting common stock of Sizable Corporation on January 2,2011 when the book value of Sizable's net assets was $460,000.The fair values of Sizable's identifiable net assets were equal to their book values except as indicated below.
 Sizable reported net income of $75,000 during 2011;dividends of $35,000 were declared and paid during the year.
Required:
1.Prepare a schedule to allocate the fair value/book value differential to the specific identifiable assets and liabilities.
2.Determine Petra's income from Sizable for 2011.
3.Determine the correct balance in the Investment in Sizable account as of December 31,2011.
Sizable reported net income of $75,000 during 2011;dividends of $35,000 were declared and paid during the year.
Required:
1.Prepare a schedule to allocate the fair value/book value differential to the specific identifiable assets and liabilities.
2.Determine Petra's income from Sizable for 2011.
3.Determine the correct balance in the Investment in Sizable account as of December 31,2011. (Essay)
4.9/5 (88)
(88) The consolidated balance sheet of Pasker Corporation and Shishobee Farm,its 80% owned subsidiary,as of December 31,2011,contains the following accounts and balances:
 Pasker Corporation acquired its interest in Shishobee Farm on January 1,2011,when Shishobee Farm had $450,000 of Capital Stock and $210,000 of Retained Earnings.Shishobee Farm's net assets had fair values equal to their book values when Pasker acquired its interest.No changes have occurred in the amount of outstanding stock since the date of the business combination.Pasker uses the equity method of accounting for its investment.
Required: Determine the following amounts:
1.The balance of Pasker's Capital Stock and Retained Earnings accounts at December 31,2011.
2.Cost of Pasker's purchase of Shishobee Farm on January 1,2011.
Pasker Corporation acquired its interest in Shishobee Farm on January 1,2011,when Shishobee Farm had $450,000 of Capital Stock and $210,000 of Retained Earnings.Shishobee Farm's net assets had fair values equal to their book values when Pasker acquired its interest.No changes have occurred in the amount of outstanding stock since the date of the business combination.Pasker uses the equity method of accounting for its investment.
Required: Determine the following amounts:
1.The balance of Pasker's Capital Stock and Retained Earnings accounts at December 31,2011.
2.Cost of Pasker's purchase of Shishobee Farm on January 1,2011. (Essay)
4.9/5 (95)
(95) On January 2,2011,Power Incorporated paid $630,000 for a 90% interest in Smallsen Company.Smallsen's equity at that time amounted to $600,000,and their book values for assets and liabilities recorded approximated their fair values.Smallsen did not issue any additional stock in 2011.At December 31,2011,the two companies' balance sheets are summarized as follows:
Power Incorporated and Subsidiary
Consolidated Balance Sheet Working Papers
at December 31,2011

 Required: Complete the consolidation worksheet for Power Incorporated and Subsidiary at December 31,2011.
 (Essay)
4.7/5 (82)
(82) Parrot Inc.acquired an 85% interest in Sparrow Corporation on January 2,2011 for $42,500 cash when Sparrow had Capital Stock of $15,000 and Retained Earnings of $25,000.Sparrow's assets and liabilities had book values equal to their fair values except for inventory that was undervalued by $2,000.Balance sheets for Parrot and Sparrow on January 2,2011,immediately after the business combination,are presented in the first two columns of the consolidated balance sheet working papers.

 Required:
Complete the consolidation balance sheet working papers for Parrot and subsidiary at January 1,2011.
Required:
Complete the consolidation balance sheet working papers for Parrot and subsidiary at January 1,2011. (Essay)
5.0/5 (85)
(85) Patterson Company acquired 90% of Starr Corporation on January 1,2011 for $2,250,000.Starr had net assets at that time with a fair value of $2,500,000.At the time of the acquisition,Patterson computed the annual excess fair-value amortization to be $20,000,based on the difference between Starr's net book value and net fair value.Assume the fair value exceeds the book value,and $20,000 pertains to the whole company.Separate from any earnings from Starr,Patterson reported net income in 2011 and 2012 of $550,000 and $575,000,respectively.Starr reported the following net income and dividend payments:
 Required: Calculate the following:
• Investment in Starr shown on Patterson's ledger at December 31,2011 and 2012.
• Investment in Starr shown on the consolidated statements at December 31,2011 and 2012.
• Consolidated net income for 2011 and 2012.
• Noncontrolling interest balance on Patterson's ledger at December 31,2011 and 2012.
• Noncontrolling interest balance on the consolidated statements at December 31,2011 and 2012.
Required: Calculate the following:
• Investment in Starr shown on Patterson's ledger at December 31,2011 and 2012.
• Investment in Starr shown on the consolidated statements at December 31,2011 and 2012.
• Consolidated net income for 2011 and 2012.
• Noncontrolling interest balance on Patterson's ledger at December 31,2011 and 2012.
• Noncontrolling interest balance on the consolidated statements at December 31,2011 and 2012. (Essay)
4.7/5 (78)
(78) On January 1,2011,Parry Incorporated paid $72,000 cash for 80% of Samuel Company's common stock.At that time Samuel had $40,000 capital stock and $30,000 retained earnings.The book values of Samuel's assets and liabilities were equal to fair values,and any excess amount is allocated to goodwill.Samuel reported net income of $18,000 during 2011 and declared $5,000 of dividends on December 31,2011.At the time the dividends were declared,Parry recorded a receivable for the amount they expected to receive the following month.A summary of the balance sheets of Parry and Samuel are shown below.

 Required:
Complete the consolidated balance sheet working papers for Parry Corporation and Subsidiary at December 31,2011.
Required:
Complete the consolidated balance sheet working papers for Parry Corporation and Subsidiary at December 31,2011. (Essay)
4.9/5 (86)
(86) On January 1,2005,Myna Corporation issued 10,000 shares of its own $10 par value common stock for 9,000 shares of the outstanding stock of Berry Corporation in an acquisition.Myna common stock at January 1,2005 was selling at $70 per share.Just before the business combination,balance sheet information of the two corporations was as follows:
 Required:
1.Prepare the journal entry on Myna Corporation's books to account for the investment in Berry Company.
2.Prepare a consolidated balance sheet for Myna Corporation and Subsidiary immediately after the business combination.
Required:
1.Prepare the journal entry on Myna Corporation's books to account for the investment in Berry Company.
2.Prepare a consolidated balance sheet for Myna Corporation and Subsidiary immediately after the business combination. (Essay)
4.9/5 (83)
(83) Perth Corporation acquired a 100% interest in Sansone Company for $1,600,000 when Sansone had no liabilities.The book values and fair values of Sansone's assets were  Immediately following the acquisition,equipment will be included on the consolidated balance sheet at
 (Multiple Choice)
4.9/5 (90)
(90) Pregler Inc.has 70% ownership of Sach Company,but should exclude Sach from its consolidated financial statements if
(Multiple Choice)
4.8/5 (93)
(93) Pardo Corporation paid $140,000 for a 70% interest in Spedeal Inc.on January 1,2011,when Spedeal had Capital Stock of $50,000 and Retained Earnings of $100,000.Fair values of identifiable net assets were the same as recorded book values.During 2011,Spedeal had income of $40,000,declared dividends of $15,000,and paid $10,000 of dividends.On December 31,2011,the consolidated financial statements will show
(Multiple Choice)
4.8/5 (84)
(84) On January 1,2012,Packaging International purchased 90% of Shipaway Corporation's outstanding shares for $135,000 when the fair value of Shipaway's net assets were equal to the book values.The balance sheets of Packaging and Shipaway Corporations at year-end 2011 are summarized as follows:  If a consolidated balance sheet was prepared immediately after the business combination,the noncontrolling interest would be
 (Multiple Choice)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)