



 Chat with AI
Exam 8: Perfect Competition

Exam 1: The Economic Problem157 Questions
Exam 2: Demand and Supply: An Introduction185 Questions
Exam 3: Demand and Supply: An Elaboration139 Questions
Exam 4: Elasticity195 Questions
Exam 5: Consumer Choice144 Questions
Exam 6: A Firms Production Decisions and Costs in the Short Run179 Questions
Exam 7: Costs in the Long Run132 Questions
Exam 8: Perfect Competition172 Questions
Exam 9: An Evaluation of Competitive Markets149 Questions
Exam 10: Monopoly179 Questions
Exam 11: Imperfect Competition145 Questions
Exam 12: The Factors of Production151 Questions
Exam 13: International Trade166 Questions
Select questions type


The following are different market structures:
1. Monopoly
2. Perfect Competitions
3. Monopolistic Competition
4. Undifferentiated Oligopoly
5. Differentiated Oligopoly
-Refer to the above information to answer this question.What is the name of the market in which there are numerous sellers who sell an identical product?
(Multiple Choice)
4.9/5  (78)
(78) The following graph shows the total variable costs and the total costs for a competitive producer:
 -Refer to the above graph to answer this question.If the price of the product is $30,what are the break-even output(s)?
 (Multiple Choice)
4.7/5 (77)
(77) All of the following,except one,are reasons why the stock market is not a good example of a perfectly competitive market.Which is the exception?
(Multiple Choice)
4.8/5 (92)
(92) Suppose that at an output of 10,a firm's MC = AVC,and at an output of 30 its MR = AVC.This means that its profit-maximizing output must be between 10 and 30 units.Evaluate this statement.
(Essay)
4.8/5 (86)
(86) The firm needs to make certain decisions in regards to price and output.Different cost curves are used in making these decisions.
a)How is the AVC curve used?
b)How is the MC curve used?
c)How is the AC curve used?
(Essay)
4.7/5 (79)
(79) If MR = MC = AVC for a perfectly competitive firm,will the firm operate or shut down? Explain.
(Essay)
4.9/5 (76)
(76) Which of the following is true for a perfectly competitive firm?
(Multiple Choice)
4.9/5 (76)
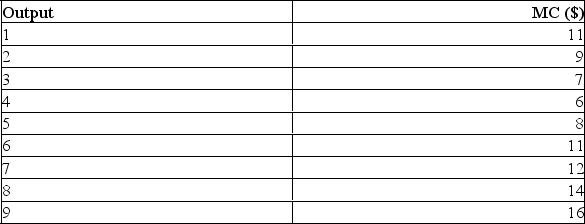
(76) You are given the following information for Clarke's Cookies which produces in a perfectly competitive market.
TFC = $10 Market price = $11
The marginal cost of production appears in the table below:
(Essay)
4.9/5 (82)
(82) Graph A shows the market demand and supply in a perfectly competitive market.Graph B shows the cost curves of a representative profit-maximizing firm in that industry.
 -Refer to the above graph to answer this question.Suppose that the industry demand were to increase by 3,000 units.At the new equilibrium,what quantity will the firm produce?
 (Multiple Choice)
4.9/5 (80)
(80) You are given the following cost and revenue information for Cindy's Candles,a perfectly competitive firm at its current level of output.
AFC = 4
ATC = 10
TVC = 600
MC = 10
TR = 1,200
a)What is the amount of profit or loss?
b)Is the firm producing at its optimal level? If not,should it increase or decrease output?
a)Economic profit = $200
(Essay)
4.8/5 (72)
(72) The following graph (A)represents the cost curves for a representative firm in a perfectly competitive market.The market demand is shown in graph (B):
 -Refer to the above graph to answer this question.Suppose that there are a total of 100 firms in this industry all with identical costs.What will be the equilibrium market price and quantity?
 (Multiple Choice)
4.8/5 (81)
(81) The following graph (A)represents the cost curves for a representative firm in a perfectly competitive market.The market demand is shown in graph (B):
-Refer to the graph above to answer this question.Which of the following represents the firm's supply schedule? 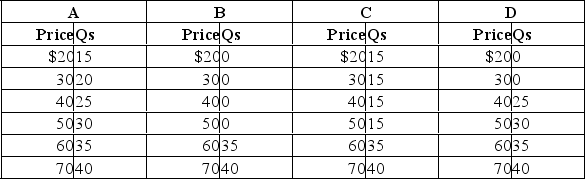
-Refer to the graph above to answer this question.Which of the following represents the firm's supply schedule? (Multiple Choice)
4.7/5 (76)
(76) Explain why average and marginal revenues are the same for the perfectly competitive producer.
(Essay)
4.7/5 (78)
(78) Suppose that the total fixed cost for a guitar manufacturer is $90.The marginal cost of the first guitar produced is $80 and decreases by $10 for the next three guitars produced.Thereafter,the marginal cost increases by $10 for each successive guitar.
-Refer to the information above to answer this question.If the manufacturer can sell her guitars for $100,what will be her profit or loss at the optimal output?
(Multiple Choice)
4.9/5 (80)
(80) Assume that the following data is for a profit-maximizing manufacturer:
 -Refer to the above information to answer this question.If the total fixed costs were to increase by $50 what would be the new break-even price?
 (Multiple Choice)
4.8/5 (75)
(75) Table 8.8 refers to a perfectly competitive firm.
 -Refer to Table 8.8 to answer this question.What is the profit-maximizing output if the price is $10?
 (Multiple Choice)
4.8/5 (81)
(81) What is the term for the price at which the firm makes zero economic profits?
(Multiple Choice)
4.9/5 (70)
(70) The following table shows a profit-maximizing producer's marginal costs.The firm is operating in a perfectly competitive market and has fixed costs of $500.
 -Refer to the above information to answer this question.If the price is $120,what is the optimal output and what is the profit or loss?
 (Multiple Choice)
4.8/5 (67)
(67) The following graph shows the total variable costs and the total costs for a competitive producer:
-Refer to the above graph to answer this question.What is the value of the break-even price?
-Refer to the above graph to answer this question.What is the value of the break-even price? (Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)