



 Chat with AI
Exam 16: Investment and Personal Financial Planning

Exam 1: Taxes and Taxing Jurisdictions85 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research82 Questions
Exam 6: Taxable Income From Business Operations116 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions116 Questions
Exam 8: Property Dispositions122 Questions
Exam 9: Nontaxable Exchanges107 Questions
Exam 10: Sole Proprietorships, Partnerships, Llcs, and S Corporations97 Questions
Exam 11: The Corporate Taxpayer103 Questions
Exam 12: The Choice of Business Entity102 Questions
Exam 13: Jurisdictional Issues in Business Taxation107 Questions
Exam 14: The Individual Tax Formula113 Questions
Exam 15: Compensation and Retirement Planning107 Questions
Exam 16: Investment and Personal Financial Planning109 Questions
Exam 17: Tax Consequences of Personal Activities93 Questions
Exam 18: The Tax Compliance Process86 Questions
Select questions type


The kiddie tax limits the tax savings from a transfer of income-producing property to a minor child by taxing a portion of such income at the parent's marginal tax rate.
(True/False)
4.9/5  (88)
(88) Which of the following statements about investment interest expense is true?
(Multiple Choice)
4.8/5 (87)
(87) Mr. Quinn recognized a $900 net short-term capital gain and a $1,380 long-term capital gain this year. Which of the following statements is false?
(Multiple Choice)
4.9/5 (72)
(72) Fifteen years ago, Lenny purchased an insurance policy on his own life. The policy provides a $3 million death benefit. Lenny has paid $682,000 of premiums, and the cash surrender value of the policy is $725,000. He plans to liquidate the policy to generate cash for his business. If Lenny's marginal tax rate is 35%, how much after-tax cash will the liquidation generate?
(Multiple Choice)
5.0/5 (65)
(65) Mr. Lee made the following transfers this year. Which of the transfers are treated as gifts for federal tax purposes?
(Multiple Choice)
4.9/5 (78)
(78) Which of the following statements about investment property is false?
(Multiple Choice)
4.8/5 (69)
(69) Mr. and Mrs. Nelson operate a small business as a sole proprietorship. This year, they have the following tax information. 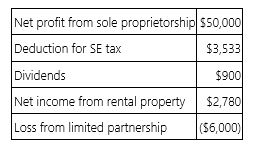 Compute Mr. and Mrs. Nelson's AGI.
 (Multiple Choice)
4.9/5 (86)
(86) Mr. Vernon owns stock in two S corporations, Able Corporation and Benson Inc. This year, Mr. Vernon had the following income and loss items. 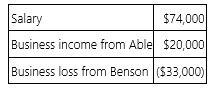 If Vernon materially participates in Able's business but not in Benson's business, compute his AGI.
 (Multiple Choice)
4.8/5 (82)
(82) Investment expenses are a miscellaneous itemized deduction subject to the 2% AGI limitation.
(True/False)
4.8/5 (86)
(86) This year, Mr. and Mrs. Lebold paid $3,100 investment interest expense. They earned $4,750 investment income consisting of $1,900 interest and $2,850 qualified dividends, and they incurred no investment expenses. Which of the following statements is true?
(Multiple Choice)
5.0/5 (77)
(77) Ruth Darma is a shareholder who is not involved in the day-to-day activities of an S corporation. Her interest in the business is a passive activity.
(True/False)
4.8/5 (64)
(64) Up to $100,000 of loss recognized on the sale of Section 1244 stock by a married individual filing a joint return is characterized as ordinary loss.
(True/False)
4.9/5 (86)
(86) The tax rate on capital gains is determined solely by reference to the capital asset's holding period.
(True/False)
4.9/5 (60)
(60) Mrs. Heyer inherited real estate from her mother. The mother's basis in the real estate was $382,000, and the fair market value at the date of the mother's death was $900,000. The mother's taxable estate was only $2.4 million, so the estate did not owe any federal estate tax. This year, Mrs. Heyer sold the real estate for $875,000. Compute her gain or loss recognized on sale.
(Multiple Choice)
4.7/5 (82)
(82) Mr. and Mrs. Holt made no taxable gifts during their lifetimes. Mrs. Holt died two years ago. Her estate tax return shows that she owed no estate tax and had an $800,000 unused lifetime exclusion. Mr. Hold died in 2015. The lifetime transfer tax exclusion available to his estate is $6,230,000.
(True/False)
4.9/5 (78)
(78) In 2015, Mr. Ames, an unmarried individual, made a gift of real estate to his nephew. Compute the amount subject to the federal gift tax in each of the following situations.
a. FMV of the real estate was $1,800,000, and the transfer was Mr. Ames' first taxable gift.
b. FMV of the real estate was $7,250,000, and the transfer was Mr. Ames' first taxable gift.
c. FMV of the real estate was $2,300,000. Two years ago, Mr. Ames made his first taxable gift of marketable securities with a $3,920,000 FMV in excess of the annual exclusion.
(Essay)
4.8/5 (80)
(80) Mrs. Lindt exchanged 212 shares of Nipher common stock for 773 shares of Newland common stock. Her basis in the Nipher stock was $49,200, and the fair market value of the Newland stock was $138,000. Which of the following statements about the exchange is true?
(Multiple Choice)
4.8/5 (80)
(80) Ms. Lopez paid $7,260 interest on a mortgage on undeveloped land that she holds as an investment. Ms. Lopez's AGI is $112,200, which includes $4,900 interest income from a certificate of deposit. Which of the following statements is true?
(Multiple Choice)
4.9/5 (80)
(80) Mr. and Mrs. Bolt's joint return reports $267,500 AGI, which includes $13,300 net investment income. Compute the couple's unearned income Medicare contribution tax.
(Multiple Choice)
4.9/5 (89)
(89) Ms. Regga, a physician, earned $375,000 from her medical practice and $20,500 interest and qualified dividends from her investment portfolio. She was allocated a $67,000 loss from a passive activity. Compute Ms. Regga's AGI.
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)