



 Chat with AI
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk

Exam 1: Why Are Financial Institutions Special97 Questions
Exam 2: Financial Services: Depository Institutions116 Questions
Exam 3: Financial Services: Finance Companies75 Questions
Exam 4: Financial Services: Securities Brokerage and Investment Banking111 Questions
Exam 5: Financial Services: Mutual Funds and Hedge Funds112 Questions
Exam 6: Financial Services: Insurance100 Questions
Exam 7: Risks of Financial Institutions111 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II98 Questions
Exam 10: Credit Risk: Individual Loan Risk112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk59 Questions
Exam 12: Liquidity Risk100 Questions
Exam 13: Foreign Exchange Risk100 Questions
Exam 14: Sovereign Risk90 Questions
Exam 15: Market Risk97 Questions
Exam 16: Off-Balance-Sheet Risk107 Questions
Exam 17: Technology and Other Operational Risks108 Questions
Exam 18: Liability and Liquidity Management131 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees105 Questions
Exam 20: Capital Adequacy148 Questions
Exam 21: Product and Geographic Expansion156 Questions
Exam 22: Futures and Forwards127 Questions
Exam 23: Options, Caps, Floors, and Collars114 Questions
Exam 24: Swaps97 Questions
Exam 25: Loan Sales92 Questions
Exam 26: Securitization114 Questions
Select questions type


Kansas Bank has a policy of limiting their loans to any single customer so that the maximum loss as a percent of capital will not exceed 20 percent for both secured and unsecured loans. The limit has been adopted under the assumption that if the unsecured loan is defaulted, there will be no recovery of interest or principal payments. For loans that are secured (collateralized), it is expected that 40 percent of interest and principal will be collected.
-What is the concentration limit (as a percent of capital) for unsecured loans made by Kansas Bank?
(Multiple Choice)
4.7/5  (80)
(80) Which of the following is a measure of the sensitivity of loan losses in a particular business sector relative to the losses in an FI's loan portfolio?
(Multiple Choice)
4.8/5 (82)
(82) In the Moody's Analytics portfolio model, the expected return on a loan is the
(Multiple Choice)
4.9/5 (72)
(72) In the Moody's Analytics portfolio model, the expected loss on a loan is
(Multiple Choice)
4.8/5 (76)
(76) National Benchmark Bank A Bank B Consumer Loans 50 percent 65 percent 35 percent Commercial Loans 50 percent 35 percent 65 percent
-Estimate the standard deviation of Bank B's asset allocation proportions relative to the national benchmark.
(Multiple Choice)
4.9/5 (76)
(76) Comparing the loan mix of an individual FI to a national benchmark loan mix is useful in determining the extent that the individual FI may differ from an efficient portfolio composition.
(True/False)
4.7/5 (86)
(86) Matrix Bank has compiled the following migration matrix on consumer loans. Which of the following statements accurately summarizes this data? 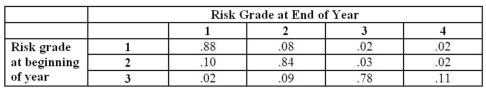
(Multiple Choice)
4.8/5 (81)
(81) A Hypothetical Rating Migration, or Transition Matrix, reflects all of the following EXCEPT
(Multiple Choice)
4.8/5 (78)
(78) The simple model of migration analysis tracks the credit ratings of companies that have borrowed from the FI.
(True/False)
4.9/5 (57)
(57) National Benchmark Bank A Bank B Consumer Loans 50 percent 65 percent 35 percent Commercial Loans 50 percent 35 percent 65 percent
-Using standard deviations, which bank is in a better position if the average earnings on the assets of Bank A is 11 percent and Bank B is 12 percent (ignore all other factors)?
(Multiple Choice)
4.8/5 (77)
(77) In 1994, The Federal Reserve Board ruled against a proposal to use quantitative models to assess credit concentration risk because
(Multiple Choice)
4.8/5 (84)
(84) National Banks Bank A Bank B Real Estate Loans 60 percent 30 percent 56 percent Consumer Loans 20 percent 30 percent 28 percent Commercial Loans 20 percent 10 percent 16 percent
-If Bank A's average return on its loan portfolio is lower than that of Bank B's,
(Multiple Choice)
4.8/5 (76)
(76) Included in the Moody's Analytics model are recovery rates on defaulted loans.
(True/False)
4.9/5 (91)
(91) In the past, data availability limited the use of sophisticated portfolio models to set concentration limits.
(True/False)
4.9/5 (81)
(81) On loans fully secured by physical, non-real estate loans, the Basel Committee has set a loss given defaults (LGD) rate of
(Multiple Choice)
4.8/5 (82)
(82) Most portfolio managers will accept some level of risk above the minimum risk portfolio if they expect to receive higher returns.
(True/False)
4.8/5 (85)
(85) Banks whose loan portfolio composition deviates from the national benchmark should immediately implement policies to move toward benchmark alignment.
(True/False)
4.7/5 (86)
(86) In the Moody's Analytics portfolio model, the risk of a loan measures
(Multiple Choice)
5.0/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)