



 Chat with AI
Exam 11: College and University Accounting Private Institutions

Exam 1: Introduction to Accounting and Financial Reporting for Governmental and Not-For-Profit Organizations111 Questions
Exam 2: Overview of Financial Reporting for State and Local Governments95 Questions
Exam 3: Modified Accrual Accounting: Including the Role of Fund Balances and Budgetary Authority89 Questions
Exam 4: Accounting for the General and Special Revenue Funds123 Questions
Exam 5: Accounting for Other Governmental Fund Types: Capital Projects, Debt Service, and Permanent130 Questions
Exam 6: Proprietary Funds123 Questions
Exam 7: Fiduciary Trust Funds139 Questions
Exam 8: Government-Wide Statements, Capital Assets, Long-Term Debt142 Questions
Exam 9: Accounting for Special-Purpose Entities, Including Public Colleges and Universities87 Questions
Exam 10: Accounting for Private Not-For-Profit Organizations133 Questions
Exam 11: College and University Accounting Private Institutions106 Questions
Exam 12: Accounting for Hospitals and Other Health Care Providers91 Questions
Exam 13: Auditing, Tax-Exempt Organizations, and Evaluating Performance128 Questions
Select questions type


Union Seminary uses the fund basis of accounting for internal record keeping. Presented below is the fully adjusted 12/31/09 balance sheet for Union, prepared using funds and account groups. The following are fund descriptions:
• Operating Fund - the fund used for transactions not falling within the definition of other funds. There are no restrictions on these resources.
• Memorial Fund - Used to account for resources donated from outside parties for specific capital additions
• Endowment Fund - Assets received from an outside donor for permanent investment, only the earnings may be expended.
• Scholarship Fund - Cash set aside by the Seminary's governing board for use as scholarships and student aid.
• Fixed Assets Account Group - A record of the Seminary's fixed assets and long-term debt.
Required: Prepare a Statement of Financial Position following the guidelines provided in FASB Statements 116 and 117 for private not-for-profits and assuming Union does not classify plant assets as temporarily restricted.

Free
(Essay)
4.9/5  (75)
(75) Correct Answer: Verified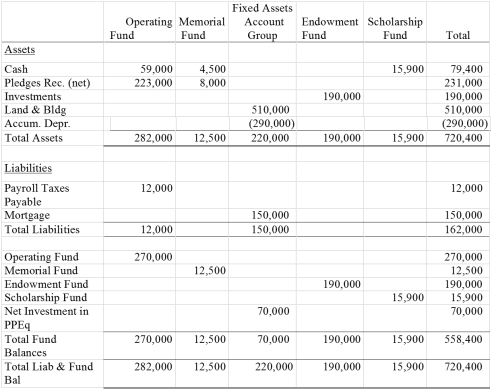
Under FASB standards, true endowments are classified as Permanently Restricted Net Assets.
Free
(True/False)
5.0/5 (82)
(82) Correct Answer:Verified
VerifiedTrue
Which of the following is true regarding accounting and financial reporting for private colleges and universities?
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedB
Plant acquired with either unrestricted or restricted resources may be (1) recorded initially as unrestricted OR (2) recorded initially as temporarily restricted and then classified in accordance with the depreciation schedule.
(True/False)
4.8/5 (91)
(91) Academic or athletic scholarships that do not require service to the college or university are treated as:
(Multiple Choice)
4.8/5 (81)
(81) If Jimmy commits to pledging $10,000 to Greystone College in 2008 and then pays in 2009, how much revenue will Greystone College recognize in 2008?.
(Multiple Choice)
5.0/5 (91)
(91) Private, Not-for-Profit Colleges and Universities must have Statement of Financial Position, Statement of Activities, Statement of Cash Flows and Notes to the Financial Statements included in their financial report.
(True/False)
4.9/5 (92)
(92) A donor made a gift of cash to a private college or university in 2009 with an expressed purpose restriction. All of the funds were expended in 2009. The private college or university must:
(Multiple Choice)
4.9/5 (80)
(80) Which of the following is an example of a temporarily restricted inflow?
(Multiple Choice)
4.8/5 (81)
(81) Distinguish between (a) right endowments, (b) term endowments and (c) quasi-endowments. Explain how the net assets of each is classified by a private college or university.
(Essay)
4.8/5 (74)
(74) Universities treat athletic scholarships as a charge to the athletic department who must pay for the scholarship out of its net revenues.
(True/False)
4.8/5 (89)
(89) With respect to private colleges and universities, why are quasi-endowments not classified as permanently restricted net assets while true endowments are?
(Essay)
4.8/5 (68)
(68) An acceptable alternative to the Statement of Activities for a private college or university is to present a Statement of Unrestricted Revenues, Expenses and Other Changes in Unrestricted Net Assets and a Statement of Changes in Net Assets.
(True/False)
4.9/5 (88)
(88) Investment income on Endowments held by private colleges and classified as permanently restricted net assets should be recorded as an increase in:
(Multiple Choice)
4.7/5 (85)
(85) Under NACUBO guidelines, the current period provision for uncollectible accounts should be reported as:
(Multiple Choice)
4.7/5 (77)
(77) A donor gave a gift of $50,000 cash to a private college in 2008 with instructions that the funds be expended for psychology research. The funds were expended in 2009. The private college would recognize the $50,000 as:
(Multiple Choice)
4.9/5 (70)
(70) As of December 31, 2009, the contribution revenue would be classified as:
(Multiple Choice)
4.9/5 (74)
(74) Private colleges and universities are governed by which of the following?
(Multiple Choice)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)