



 Chat with AI
Exam 14: Futures Contracts

Exam 1: A Brief History of Risk and Return100 Questions
Exam 2: The Investment Process98 Questions
Exam 3: Overview of Security Types94 Questions
Exam 4: Mutual Funds and Other Investment Companies101 Questions
Exam 5: The Stock Market104 Questions
Exam 6: Common Stock Valuation102 Questions
Exam 7: Stock Price Behavior and Market Efficiency82 Questions
Exam 8: Behavioral Finance and the Psychology of Investing84 Questions
Exam 9: Interest Rates100 Questions
Exam 10: Bond Prices and Yields95 Questions
Exam 11: Diversification and Risky Asset Allocation84 Questions
Exam 12: Return, Risk, and the Security Market Line84 Questions
Exam 13: Performance Evaluation and Risk Management91 Questions
Exam 14: Futures Contracts97 Questions
Exam 15: Stock Options100 Questions
Exam 16: Option Valuation72 Questions
Exam 17: Projecting Cash Flow and Earnings100 Questions
Exam 18: Corporate and Government Bonds107 Questions
Exam 19: Global Economic Activity and Industry Analysis70 Questions
Exam 20: Mortgage-Backed Securities92 Questions
Select questions type


The 4-month futures price on a non-dividend-paying stock is $23.60.The risk-free rate is 2.25 percent and the market rate is 10.45 percent.What is the spot rate for this stock if spot-futures parity exists?
(Multiple Choice)
4.9/5  (87)
(87) Which of the following are reasons why commodities may have a negative basis?
I.storage costs
II.seasonal price fluctuations
III.transportation costs
IV.interest costs
(Multiple Choice)
4.9/5 (64)
(64) You own six November crude oil futures contracts.What is the settlement value of those contracts at the end of this trading day? 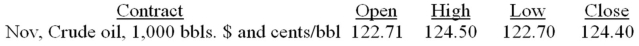
(Multiple Choice)
4.8/5 (87)
(87) You purchased two futures contracts on soybeans at a price quote of 1344′0.The initial margin requirement is $4,750 per contract and the maintenance margin is $3,500 per contract.The contract quantity is 5,000 bushels and the price quote is in cents per bushel.What is the lowest the price quote can go before you receive a margin call?
(Multiple Choice)
4.8/5 (75)
(75) Corn is currently selling for $6.15 a bushel while the 3-month futures price is $6.20.Carlos believes that corn will actually sell for $6.45 a bushel 3 months from now.Which one of the following positions in corn should he take today,given this belief?
(Multiple Choice)
4.7/5 (79)
(79) Which one of the following is a contract managed by an organized exchange that allows a buyer and seller to agree on a price today for an exchange of goods that will occur sometime in the future?
(Multiple Choice)
4.9/5 (85)
(85) By how much did one September futures contract on wheat vary during today's trading? 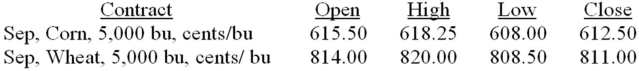
(Multiple Choice)
4.8/5 (86)
(86) A stock is currently selling for $38.50 a share and has a dividend yield of 1.75 percent.The risk-free rate is 3.5 percent.What is the 2-month futures price on this stock?
(Multiple Choice)
4.7/5 (86)
(86) Explain why some futures contracts are settled in cash while others are not.Provide an example of each.
(Essay)
4.8/5 (85)
(85) You own 450,000 bushels of wheat.If you decide to add a short futures position in wheat you will be taking which one of the following positions?
(Multiple Choice)
4.9/5 (79)
(79) Your broker requires an initial margin of $1,500 and a maintenance margin of $1,000 on Treasury note futures.Treasury note futures contracts are based on a $100,000 par value and quoted in points and one-half of 1/32 of a point.You own one Treasury futures contract that had a closing settlement quote of 113′245 yesterday.Today,the settlement quote is 112′265.Your margin balance at yesterday's close was $1,150.All margin calls restore margin levels to their initial level.Will you receive a margin call based on today's settlement quote and if so,for what amount?
(Multiple Choice)
5.0/5 (83)
(83) The duration of an interest rate futures contract is equal to the summation of which of the following?
I.duration of the instrument most likely to be used as a cross-hedge
II.duration of the underlying instrument
III.initial length of time of the futures contract
IV.time remaining on the futures contract
(Multiple Choice)
4.9/5 (84)
(84) Jackie manages a $620 million bond portfolio which has a duration of 4.05 years.She wants to hedge the portfolio with Treasury note futures that have a duration of 4.53 years and a futures price of 112.U.S.Treasury notes futures contracts are based on a par value of $100,000 and quoted as a percentage of par.How many contracts does she need to sell to complete this hedge?
(Multiple Choice)
4.8/5 (80)
(80) A stock is currently selling for $28 a share and has a dividend yield of 3.2 percent.The risk-free rate is 2.5 percent.What is the 6-month futures price on this stock?
(Multiple Choice)
4.9/5 (76)
(76) Which one of the following terms applies to the amount of money required when a futures position is first bought or sold?
(Multiple Choice)
4.9/5 (76)
(76) You purchased five September wheat futures contracts at the open today and sold those contracts at the close.What is your total profit or loss on these contracts? 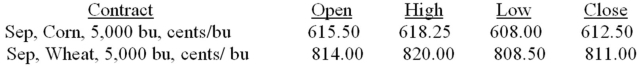
(Multiple Choice)
4.7/5 (83)
(83) You are the chief financial officer (CFO)of a major textile importer.Identify one of the key risks your company faces and explain how you can hedge this risk using futures.
(Essay)
4.9/5 (81)
(81) You are trying to value a 3-month futures contract on a stock.The market rate of return is 11.2 percent,the risk-free rate is 3.8 percent,and the dividend yield on the stock is 2.6 percent.The stock is currently selling for $33 a share.What is the value of "T" as used in the formula for computing the future stock price (FT = S(1 - r)^T)?
(Multiple Choice)
4.7/5 (77)
(77) What is the absolute price difference on a $100,000,5-year Treasury note futures contract between the high and low prices?
Treasury note,$100,000,pts and one-quarter of 1/32 of a point 
(Multiple Choice)
4.8/5 (81)
(81) Which one of the following is a notification to a futures contract holder that additional margin funds are needed?
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)