



 Chat with AI
Exam 8: Corporate Formation, Neorganization, and Liquidation

Exam 1: Business Income,Deductions,and Accounting Methods99 Questions
Exam 2: Property Acquisition and Cost Recovery107 Questions
Exam 3: Property Dispositions110 Questions
Exam 4: Entities Overview70 Questions
Exam 5: Corporate Operations140 Questions
Exam 6: Accounting for Income Taxes100 Questions
Exam 7: Corporate Taxation: Nonliquidating Distributions100 Questions
Exam 8: Corporate Formation, Neorganization, and Liquidation100 Questions
Exam 9: Forming and Operating Partnerships106 Questions
Exam 10: Dispositions of Partnership Interests and Partnership Distributions100 Questions
Exam 11: S Corporations134 Questions
Exam 12: State and Local Taxes117 Questions
Exam 13: The Ustaxation of Multinational Transactions100 Questions
Exam 14: Transfer Taxes and Wealth Planning123 Questions
Select questions type


The requirements for tax deferral in a forward triangular merger and a reverse triangular merger are the same.
(True/False)
4.9/5  (74)
(74) Which of the following requirements do not have to be met in a section 351 transaction?
(Multiple Choice)
4.9/5 (76)
(76) In December 2017,Zeb incurred a $100,000 loss on the sale of Pike Corporation stock that he purchased in 2010.The stock satisfied all of the §1244 stock requirements at the time of issue.In addition,Zeb reported a long-term capital gain of $40,000 in 2017.Zeb is single.How much of the loss can Zeb deduct in 2017,and what is the character of the loss?
(Essay)
4.8/5 (87)
(87) Packard Corporation transferred its 100 percent interest to State Company as part of a complete liquidation of the company.In the exchange,Packard received land with a fair market value of $300,000.Packard's basis in the State stock was $600,000.The land had a basis to State Company of $500,000.What amount of loss does State recognize in the exchange and what is Packard's basis in the land it receives?
(Multiple Choice)
4.8/5 (97)
(97) Sybil transfers property with a tax basis of $5,000 and a fair market value of $6,000 to a corporation in exchange for stock with a fair market value of $3,000 and $2,000 in cash in a transaction that qualifies for deferral under section 351.The corporation assumed a liability of $1,000 on the property transferred.What is Sybil's tax basis in the stock received in the exchange?
(Multiple Choice)
4.8/5 (66)
(66) The shareholders in the target corporation always receive a tax basis in the stock received from the acquirer equal to the stock's fair market value.
(True/False)
4.9/5 (88)
(88) Rich and Rita propose to have their corporation,Big Blue,acquire another corporation,Green Company,in a stock-for-stock Type B acquisition.The sole shareholder of Green,Mark Dee,will receive $500,000 of Big Blue voting stock in the transaction.Mark's tax basis in his Green stock is $100,000.What is Mark's tax basis in the Big Blue stock he receives in the exchange and what is Big Blue's basis in the Green stock it receives in return?
(Essay)
4.8/5 (71)
(71) Which of the following statements best describes the tax benefits that arise from the sale of section 1244 stock?
(Multiple Choice)
4.9/5 (81)
(81) Sue transferred 100 percent of her stock in Oakland Company to Applegate Corporation in a Type A merger.In exchange she received stock in Applegate with a fair market value of $800,000 plus $400,000 in cash.Sue's tax basis in the Oakland stock was $1,500,000.What amount of gain or loss does Sue recognize in the exchange and what is her basis in the Applegate stock she receives?
(Essay)
4.9/5 (72)
(72) Rachelle transfers property with a tax basis of $800 and a fair market value of $900 to a corporation in exchange for stock with a fair market value of $750 and $50 in cash in a transaction that qualifies for deferral under section 351.The corporation assumed a liability of $100 on the property transferred.What is Rachelle's tax basis in the stock received in the exchange?
(Multiple Choice)
4.7/5 (87)
(87) Which of the following statements best describes the requirement that must be met in a tax-deferred Type B stock-for-stock reorganization?
(Multiple Choice)
4.9/5 (93)
(93) Gary and Laura decided to liquidate their jointly owned corporation,Amelia,Inc.After liquidating its remaining inventory and paying off its remaining liabilities,Amelia had the following tax accounting balance sheet.
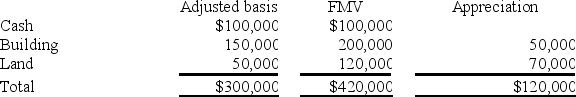 Under the terms of the agreement,Gary will receive the $100,000 cash in exchange for his interest in Amelia.Gary's tax basis in his Amelia stock is $30,000.Laura will receive the building and land in exchange for her interest in Amelia.Laura's tax basis in her Amelia stock is $60,000.
What amount of gain or loss does Amelia recognize in the complete liquidation?
Under the terms of the agreement,Gary will receive the $100,000 cash in exchange for his interest in Amelia.Gary's tax basis in his Amelia stock is $30,000.Laura will receive the building and land in exchange for her interest in Amelia.Laura's tax basis in her Amelia stock is $60,000.
What amount of gain or loss does Amelia recognize in the complete liquidation? (Essay)
4.7/5 (78)
(78) A liquidated corporation will always recognize loss in a complete liquidation where none of the shareholders is a corporation.
(True/False)
4.8/5 (67)
(67) Juan transferred 100 percent of his stock in Rosa Company to Azul Corporation in a Type B stock-for stock exchange.In exchange,he received stock in Azul with a fair market value of $1,000,000.Juan's tax basis in the Rosa stock was $400,000.What amount of gain does Juan recognize in the exchange and what is his basis in the Azul stock he receives?
(Multiple Choice)
4.8/5 (74)
(74) The City of Boston made a capital contribution of land to Fenway Company as an inducement to the company to build a manufacturing plant in the city.Boston paid $600,000 for the land several years ago and it currently has a fair market value of $1,000,000.What is the tax basis of the land to Fenway Company?
(Short Answer)
4.7/5 (82)
(82) Inez transfers property with a tax basis of $200 and a fair market value of $300 to a corporation in exchange for stock with a fair market value of $250 in a transaction that qualifies for deferral under section 351.The corporation assumed a liability of $50 on the property transferred.What is the corporation's tax basis in the property received in the exchange?
(Multiple Choice)
4.8/5 (62)
(62) Han transferred land to his corporation in a section 351 transaction.Han had held the land for two years prior to the transfer.The corporation will tack Han's holding period for the land.
(True/False)
4.9/5 (81)
(81) Which of the following statements best describes the impact of receiving boot in a section 351 transaction?
(Multiple Choice)
4.9/5 (85)
(85) Zhao incorporated her sole proprietorship by transferring inventory,a building,and land to the corporation in return for 100 percent of the corporation's stock.The property transferred to the corporation had the following fair market values and tax-adjusted bases.
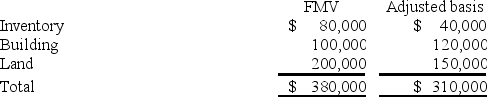 The corporation also assumed a mortgage of $50,000 attached to the building and land.The fair market value of the corporation's stock received in the exchange was $330,000.The transaction met the requirements to be tax-deferred under §351.
a.What amount of gain or loss does Zhao realize on the transfer of the property to her corporation?
b.What amount of gain or loss does Zhao recognize on the transfer of the property to her corporation?
c.What is the corporation's adjusted basis in each of the assets received in the exchange?
The corporation also assumed a mortgage of $50,000 attached to the building and land.The fair market value of the corporation's stock received in the exchange was $330,000.The transaction met the requirements to be tax-deferred under §351.
a.What amount of gain or loss does Zhao realize on the transfer of the property to her corporation?
b.What amount of gain or loss does Zhao recognize on the transfer of the property to her corporation?
c.What is the corporation's adjusted basis in each of the assets received in the exchange? (Essay)
4.8/5 (81)
(81) Which of the following class of stock is not allowed to be used in a section 351 transaction?
(Multiple Choice)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)