



 Chat with AI
Exam 11: Credit Risk II: Loan Portfolio and Concentration Risk

Exam 1: Why Are Financial Institutions Special67 Questions
Exam 2: The Financial Services Industry: Depository Institutions66 Questions
Exam 3: The Financial Services Industry: Other Financial Institutions56 Questions
Exam 4: Risk of Financial Institutions67 Questions
Exam 5: Interest Rate Risk Measurement: The Repricing Model69 Questions
Exam 6: Interest Rate Risk Measurement: the Duration Model65 Questions
Exam 7: Managing Interest Rate Risk Using Off Balance Sheet Instruments62 Questions
Exam 8: Credit Risk I: Individual Loan Risk65 Questions
Exam 9: Market Risk55 Questions
Exam 10: Credit Risk I: Individual Loan Risk65 Questions
Exam 11: Credit Risk II: Loan Portfolio and Concentration Risk50 Questions
Exam 12: Sovereign Risk65 Questions
Exam 13: Foreign Exchange Risk64 Questions
Exam 14: Liquidity Risk64 Questions
Exam 15: Liability and Liquidity Management65 Questions
Exam 16: Off-Balance-Sheet Activities65 Questions
Exam 17: Technology and Other Operational Risk67 Questions
Exam 18: Capital Management and Adequacy66 Questions
Select questions type


The Basel Committee on Banking Supervision considers regulatory loan concentration limits to individual borrowers as an issue of granularity. Which of the following statements is true in this context?
(Multiple Choice)
4.9/5  (85)
(85) The most important swap contract in terms of quantity is the credit swap.
(True/False)
4.9/5 (91)
(91) Consider the following hypothetical transition matrix: 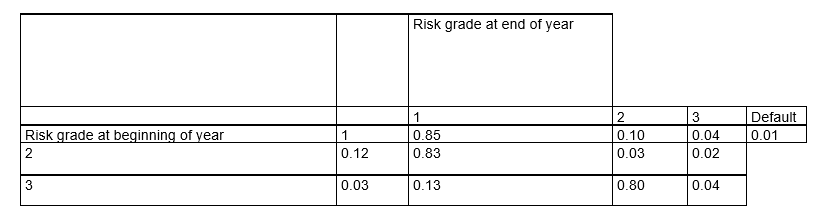 Which of the following statements is true?
 (Multiple Choice)
4.8/5 (75)
(75) Assume that the maximum loss as a percentage of capital is 9 per cent of an FI's capital to a particular sector and that the amount recovered per dollar of defaulted loans in this sector is 70 per cent. What is the concentration limit (round to two decimals)?
(Multiple Choice)
4.9/5 (86)
(86) Assume that an FI's concentration limit on a particular sector is 15 per cent and that the sector's loss rate is 25 per cent. What is the maximum loss as a percentage of the FI's capital (round to two decimals)?
(Multiple Choice)
4.8/5 (68)
(68) Which of the following is a major difference between a pure credit swap and a default option?
(Multiple Choice)
4.8/5 (70)
(70) Using the KMV Portfolio Manager Model, the return on a loan can be calculated as the annual all-in-spread minus the loss in the event of default.
(True/False)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)