



 Chat with AI
Exam 10: Accounting for Private Not-For-Profit Organizations

Exam 1: Introduction to Accounting and Financial Reporting for Governmental and Not-For-Profit Organizations132 Questions
Exam 2: Overview of Financial Reporting for State and Local Governments136 Questions
Exam 3: Modified Accrual Accounting: Including the Role of Fund Balances and Budgetary Authority141 Questions
Exam 4: Accounting for the General and Special Revenue Funds124 Questions
Exam 5: Accounting for Other Governmental Fund Types: Capital Projects, Debt Service, and Permanent149 Questions
Exam 6: Proprietary Funds130 Questions
Exam 7: Fiduciary Funds, Inter-fund Transactions141 Questions
Exam 8: Government-Wide Statements: Capital Assets; Long-Term Debt144 Questions
Exam 9: Accounting for Special-Purpose Entities Including Public Colleges and Universities104 Questions
Exam 10: Accounting for Private Not-For-Profit Organizations150 Questions
Exam 11: College and University Accounting Private Institutions125 Questions
Exam 12: Accounting for Hospitals and Other Health Care Providers100 Questions
Exam 13: Auditing, Tax-Exempt Organizations, and Evaluating Performance150 Questions
Exam 14: Financial Reporting by the Federal Government68 Questions
Select questions type


FASB Statement 124,Accounting for Certain Investments of Not-for-Profit Organizations:
(Multiple Choice)
4.7/5  (99)
(99) When preparing the Statement of Cash Flows for a private not-for-profit organization,the direct method or indirect method may be used.
(True/False)
4.8/5 (85)
(85) According to FASB Statement No.116,Appendix D,how are not-for-profit organizations distinguished from a business?
(Essay)
4.9/5 (80)
(80) Fixed assets may be recorded by a private not-for-profit as temporarily restricted or unrestricted,depending on the policy of the organization.
(True/False)
4.8/5 (78)
(78) Contributed services are recognized as revenue for a private not-for-profit when the service:
(Multiple Choice)
4.7/5 (87)
(87) FASB statement 116 requires contributions to be recorded as revenue when the contributed money is actually received.
(True/False)
4.8/5 (74)
(74) Contrast the reporting of mergers and acquisitions under the rules established by FASB Statement No.164,Not-for-Profit Entities:
Mergers and Acquisitions?
(Essay)
4.9/5 (83)
(83) A private not-for-profit reports expenses in either the unrestricted net asset class or restricted net asset class,depending which program the expense was supporting.
(True/False)
4.8/5 (81)
(81) Reclassifications from permanently restricted net assets to temporarily restricted net assets would occur only under which of the following circumstances?
(Multiple Choice)
4.9/5 (76)
(76) The financial statements of private not-for-profits are intended primarily for those who have a residual claim to the net assets of the organization.
(True/False)
4.8/5 (72)
(72) With respect to the Statement of Cash Flows for a private not-for-profit organization,the purchase of equipment would be considered an investing activity.
(True/False)
4.7/5 (81)
(81) Below are the complete set of published financial statements taken from the annual report of the Jamestown Museum. The statements do not comply with generally accepted accounting principles for private not-for-profits in a number of ways. Review these statements and describe instances in which the statements fail to comply with accepted accounting standards. You must be able to justify your assertions - for example you cannot say they failed to capitalize leases if there is no evidence they have a qualifying lease.
Example:
(1)The financial statements contain no note disclosures. The notes are an integral part of the financial statements and many individual disclosures are required under FASB standards.
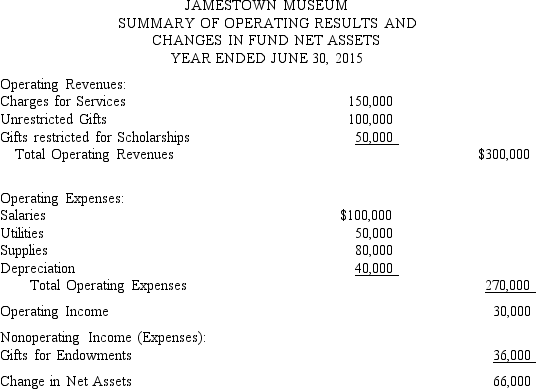
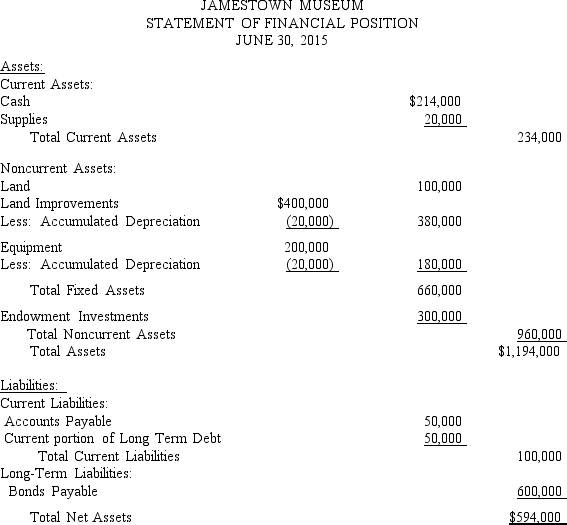
(Essay)
4.8/5 (66)
(66) Under which of the following conditions is it appropriate for a private not-for-profit to allocate the cost of mass mailings from fund raising to a program related activity,such as Public Education?
(Multiple Choice)
4.8/5 (77)
(77) Which of the following is not true regarding the Statement of Cash Flows for nongovernmental,not-for-profit organizations?
(Multiple Choice)
4.9/5 (75)
(75) A donor gave artwork to a nongovernmental,not-for-profit museum. The artwork qualified as a "collection," under FASB rules. The not-for-profit could:
(Multiple Choice)
4.8/5 (86)
(86) When might it be appropriate for a not-for-profit organization to report a surplus (increase in net assets)?
(Essay)
4.9/5 (86)
(86) Which of the following is part of the treatment of multi-year pledges as required by FASB Statement No.116?
(Multiple Choice)
4.8/5 (72)
(72) As of December 31,2014,The Halifax Fishing Museum had unrestricted cash of $52,000,building and land with a net book value of $145,000,and permanently restricted collections totaling $ 105,000. There were no liabilities. The Museum has two programs:
Operation of a Fishing Museum and Educational Programs. During the year ended December 31,2015 the Museum incurred the following transactions:
(1)Cash contributions to the Museum included (a)unrestricted $ 512,000,(b)restricted for educational programs $ 37,000 and (c)restricted by the donor for endowment purposes $100,000.
(2)Additional unrestricted cash receipts included $ 29,000 in fees from individuals and organizations using the Museum building as a meeting facility. Included in this is $ 3,000 for a meeting to be held in January 2014.
(3)Incurred cash expenses:
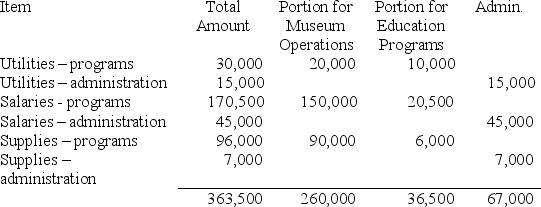 (4)Purchased land for future expansion to the adjoining lot in the amount of $ 35,000.
(5)Depreciation on the Museum building amounted to $ 55,000 and is allocated on the basis of square feet:
$ 40,000 to Museum operations,$ 5,000 to Education Programs,and $ 10,000 to administration.
(6)Outstanding purchase orders for administrative supplies at 12-31-2015 totaled $2,000.
Required:
Prepare a Statement of Activities and Changes in Net Assets for the Museum for the year ended 12-31-2015.
(4)Purchased land for future expansion to the adjoining lot in the amount of $ 35,000.
(5)Depreciation on the Museum building amounted to $ 55,000 and is allocated on the basis of square feet:
$ 40,000 to Museum operations,$ 5,000 to Education Programs,and $ 10,000 to administration.
(6)Outstanding purchase orders for administrative supplies at 12-31-2015 totaled $2,000.
Required:
Prepare a Statement of Activities and Changes in Net Assets for the Museum for the year ended 12-31-2015. (Essay)
4.9/5 (71)
(71) Which of the following organizations would not be subject to the (level b)accounting and reporting requirements of the AICPA's Audit and Accounting Guide: Not-for-Profit Organizations?
(Multiple Choice)
5.0/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)