



 Chat with AI
Exam 8: Government-Wide Statements: Capital Assets; Long-Term Debt

Exam 1: Introduction to Accounting and Financial Reporting for Governmental and Not-For-Profit Organizations132 Questions
Exam 2: Overview of Financial Reporting for State and Local Governments136 Questions
Exam 3: Modified Accrual Accounting: Including the Role of Fund Balances and Budgetary Authority141 Questions
Exam 4: Accounting for the General and Special Revenue Funds124 Questions
Exam 5: Accounting for Other Governmental Fund Types: Capital Projects, Debt Service, and Permanent149 Questions
Exam 6: Proprietary Funds130 Questions
Exam 7: Fiduciary Funds, Inter-fund Transactions141 Questions
Exam 8: Government-Wide Statements: Capital Assets; Long-Term Debt144 Questions
Exam 9: Accounting for Special-Purpose Entities Including Public Colleges and Universities104 Questions
Exam 10: Accounting for Private Not-For-Profit Organizations150 Questions
Exam 11: College and University Accounting Private Institutions125 Questions
Exam 12: Accounting for Hospitals and Other Health Care Providers100 Questions
Exam 13: Auditing, Tax-Exempt Organizations, and Evaluating Performance150 Questions
Exam 14: Financial Reporting by the Federal Government68 Questions
Select questions type


Internal Service Funds are most commonly included in the business-type activities category of the government-wide statements.
(True/False)
4.9/5  (85)
(85) Which of the following is false regarding government-wide financial statements?
(Multiple Choice)
4.8/5 (77)
(77) With regard to the government-wide statements,indicate the three categories of Net Position that should be reported and describe what would be put into each category.
(Essay)
4.9/5 (83)
(83) In its Statement of Net Position,a government reported:
•assets of $100 million,including $30 million in capital assets (net),and
•liabilities of $40 million,including long-term debt of $15 million,all related to capital asset acquisition.
The government also reported $10 million of net assets were restricted for payment of debt service.The government's Unrestricted Net Position would be reported as:
(Multiple Choice)
4.8/5 (76)
(76) GASB requires that infrastructure be depreciated on the government-wide statements unless the government chooses to use the modified approach which expenses amounts expended to increase the life of infrastructure.
(True/False)
4.9/5 (81)
(81) The City of Greystone maintains its books so as to prepare fund accounting statements and prepares worksheet adjustments in order to prepare government-wide statements. You are to prepare,in journal form,worksheet adjustments for each of the following situations:
A.The City levied property taxes for the current fiscal year in the amount of $8,000,000. At year-end,$720,000 of the taxes had not been collected. It was estimated that $330,000 of that amount would be collected during the 60 days after the end of the fiscal year and that $250,000 would be collected after that time and the balance would be uncollectible. The City had recognized the maximum of property taxes allowable under modified accrual accounting.
B.$179,000 of property taxes had been deferred at the end of the previous year and was recognized under modified accrual as revenue in the current year.
C.In addition to the expenditures allowed under modified accrual accounting,the city computed that an additional $72,000 should be accrued for compensated absences.
D.In the Statement of Revenues,Expenditures,and Changes in Fund Balances,General Fund transfers out included $400,000 to a debt service fund and $270,000 to a special revenue fund. General Fund transfers in included $1,000,000 from an enterprise fund.
(Essay)
4.8/5 (70)
(70) The difference between the amount of debt limit calculated as prescribed by law and the net amount of outstanding indebtedness subject to limitation,is known as:
(Multiple Choice)
4.8/5 (86)
(86) A government reported an "other financing source" in the amount of $750,000,related to the sale of land in its governmental funds Statement of Revenues,Expenditures,and Changes in Fund Balances.The land had a cost of $300,000.The adjustment in the reconciliation,when moving from the governmental Funds Statement of Revenues,Expenditures,and Changes in Fund Balances to the change in net position for governmental activities in the Statement of Activities would be a(an):
(Multiple Choice)
4.9/5 (85)
(85) Assume a government reported $300,000 in capital outlay expenditures in the governmental fund Statement of Revenues,Expenditures,and Changes in Fund Balances.Secondly,assume accumulated depreciation of capital assets amounted to $250,000,in the governmental activities column in the Statement of Activities.Those adjustments would cause a decrease of $50,000 when preparing the reconciliation between the change in governmental fund balances to the change in net position of governmental activities in the Statement of Activities.
(True/False)
4.9/5 (68)
(68) With regard to the government-wide statements,list the required statements.
(Essay)
4.7/5 (86)
(86) Which of the following would not be an adjustment for long-term debt when preparing government-wide financial statements?
(Multiple Choice)
4.7/5 (77)
(77) Fiduciary activities never appear in the government-wide statements.
(True/False)
4.8/5 (70)
(70) The City of Odessa maintains its books so as to prepare fund accounting statements and prepares worksheet adjustments in order to prepare government-wide statements. As such,the City's internal service fund,a print shop fund,is included in the proprietary funds statements. Required:
Prepare necessary adjustments in order to incorporate the internal service fund in the government-wide statements as a part of governmental activities:
A.Balance sheet accounts include:
Cash,$150,000; Inventories,$425,000; Capital Assets,$1,200,000; Accumulated Depreciation,$600,000; Accounts Payable,$150,000; and Bonds Payable,$500,000.
B.The only transaction in the internal service fund that is external to the government is interest expense in the amount of $15,000.
C.Exclusive of the interest expense,the internal service fund reported operating income of $40,000. An examination of the records indicates that services were provided as follows:
one half to general government,one fourth to public safety,one fourth to culture and recreation.
(Essay)
4.8/5 (85)
(85) Which of the following would not need to be addressed/adjusted in compiling the government-wide statements?
(Multiple Choice)
4.9/5 (73)
(73) In addition to a Statement of Net Position,which of the following are government-wide statements?
(Multiple Choice)
4.9/5 (80)
(80) The City of Thomasville maintains its books so as to prepare fund accounting statements and prepares worksheet adjustments in order to prepare government-wide financial statements. Required:
You are to prepare,in journal form,worksheet adjustments for each of the following situations.
A.General fixed assets,as of the beginning of the year,which had not been recorded,were as follows:
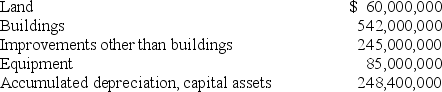 B.During the year,expenditures for capital outlays amounted to $14,250,000.Of that amount,$11,900,000 was for buildings; $1,950,000 was for improvements other than buildings,$ 10,000 was capitalized interest and the remainder was for land.
C.The capital outlay expenditures outlined in (B)were completed at the end of the year (no depreciation until next year). For purposes of financial statement presentation,all capital assets are depreciated using the straight-line method,with no estimated salvage value. Estimated lives are as follows:
buildings,50 years; improvements other than buildings,20 years; equipment,10 years.
D.Equipment with a cost of $ 90,000 and accumulated depreciation at the time of sale of $60,000 was sold for $25,000.
B.During the year,expenditures for capital outlays amounted to $14,250,000.Of that amount,$11,900,000 was for buildings; $1,950,000 was for improvements other than buildings,$ 10,000 was capitalized interest and the remainder was for land.
C.The capital outlay expenditures outlined in (B)were completed at the end of the year (no depreciation until next year). For purposes of financial statement presentation,all capital assets are depreciated using the straight-line method,with no estimated salvage value. Estimated lives are as follows:
buildings,50 years; improvements other than buildings,20 years; equipment,10 years.
D.Equipment with a cost of $ 90,000 and accumulated depreciation at the time of sale of $60,000 was sold for $25,000. (Essay)
4.8/5 (87)
(87) A company has bonds outstanding at the beginning of the current year.The debit in the worksheet entry to bring these on to the books would be to:
(Multiple Choice)
4.8/5 (70)
(70) The following data applies to the next three questions:
The City of Charlestown levied property taxes in the amount of $10,000,000. It is estimated that 2% will not be collected. The taxes were levied July 1, 2014 for the fiscal year ended June 30, 2015. During the year ended June 30, 2015, $8,900,000 in property taxes were collected from this levy. It is estimated that $620,000 will be collected during the next 60 days, $300,000 will be collected more than 60 days after June 30, 2015, and $180,000 will never be collected.
-When preparing the General Fund financial statements,how much property tax revenue should be recognized from this levy for the year ended June 30,2015?
(Multiple Choice)
4.8/5 (93)
(93) Which of the following is true concerning infrastructure assets?
(Multiple Choice)
4.9/5 (80)
(80) When preparing the government-wide statements,a worksheet entry is required to eliminate the current period expenditures for capital outlay and record those expenditures as capital assets
(True/False)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)