



 Chat with AI
Exam 5: Uncertainty

Exam 1: Preferences and Utility14 Questions
Exam 2: Utility Maximization and Choice15 Questions
Exam 3: Income and Substitution Effects22 Questions
Exam 4: Demand Relationships Among Goods18 Questions
Exam 5: Uncertainty19 Questions
Exam 6: Game Theory20 Questions
Exam 7: Production Functions14 Questions
Exam 8: Cost Functions20 Questions
Exam 9: Profit Maximization32 Questions
Exam 10: The Partial Equilibrium Competitive Model32 Questions
Exam 11: General Equilibrium and Welfare24 Questions
Exam 12: Monopoly22 Questions
Exam 13: Imperfect Competition21 Questions
Exam 14: Labor Markets20 Questions
Exam 15: Capital and Time20 Questions
Exam 16: Asymmetric Information18 Questions
Exam 17: Externalities and Public Goods25 Questions
Select questions type


An individual whose utility function is given by 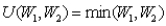 (where Wi is wealth in state i)will:
Free
(Multiple Choice)
4.8/5  (76)
(76) Correct Answer: Verified
A
A risk-averse individual is offered a gamble that promises a gain of $1000 with probability 0.25 and a loss of $300 with probability 0.75.Given this situation,he or she will:
Free
(Multiple Choice)
4.8/5 (81)
(81) Correct Answer:Verified
VerifiedD
Risk aversion is best explained by:
Free
(Multiple Choice)
4.9/5 (83)
(83) Correct Answer:Verified
VerifiedD
Suppose a person's utility of wealth is given by  And his or her initial wealth is 10,000.What is the maximum amount he or she would pay for insurance against a 50 percent chance of losing 3,600?
 (Multiple Choice)
4.9/5 (82)
(82) The condition for optimal portfolio choice can be represented by:
(Multiple Choice)
4.9/5 (74)
(74) Which of the following utility functions exhibits constant absolute risk aversion?
(Multiple Choice)
5.0/5 (97)
(97) Risk-averse individuals will diversify their investments because this will:
(Multiple Choice)
4.7/5 (75)
(75) People who always choose not to participate in fair games are called:
(Multiple Choice)
4.8/5 (72)
(72) If a fair game is played many times the monetary losses or gains will:
(Multiple Choice)
4.8/5 (79)
(79) A risk-neutral individual is offered a gamble that promises a gain of $1000 with probability 0.25 and a loss of $300 with probability 0.75.Given this situation,he or she will:
(Multiple Choice)
4.8/5 (83)
(83) Which of the following utility functions exhibits constant relative risk aversion?
(Multiple Choice)
4.9/5 (69)
(69) Faced with an uncertain situation,the best decision for a person obeying the von-Neumann Morgenstern axioms:
(Multiple Choice)
4.8/5 (68)
(68) Which of the following utility functions would indicate the most (relative)risk-averse behavior?
(Multiple Choice)
4.8/5 (69)
(69) What property of the von-Neumann Morgenstern utility function is related to risk aversion?
(Multiple Choice)
4.8/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)