



 Chat with AI
Exam 14: Competitive Market Equilibrium


Suppose there are no recurring fixed costs and the daily production process for all identical firms in a perfectly competitive industry has decreasing returns to scale throughout.Then each firm will only produce a single good each day when the industry is in long run equilibrium.

 (92)
 Verified
True
Suppose you are Joe -- one of many souvenir shop owners in a town centered around tourism.All souvenir shop owners face the same decreasing returns to scale production technology as well as recurring annual fixed costs, and they all sell a single local novelty x that is identical across all shops.Assume at the outset of each part below that the souvenir shop market in this town is in long run equilibrium and treat each part separately - i.e.do not carry what you concluded in one part into the next - except for part (e) where you are explicitly asked to continue with the set-up in part (d).
a.The Disney Corporation has set up a new theme park in a town 20 miles away and, as a result, a fraction of tourists that used to stay in your town are now staying elsewhere on their vacation.What happens to your price and output in the market and in Joe's business in the short and long run (assuming that you remain open for business)? Can you tell whether the number of souvenir shops in your town increases or decreases?
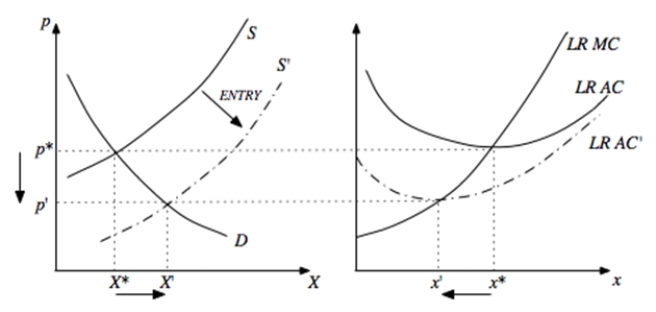
b.A new mayor in your town lowers recurring annual business license fees.What happens to the price and output in the market and Joe's business in the short and long run? Will the number of souvenir shops in the town increase or decrease?
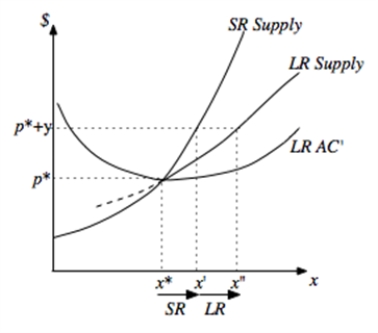
c.A local reporter discovers that the famous "Joe the Plummer" is a distant cousin of yours - and you convince your cousin Joe to join you in your business.The newly renamed souvenir shop, "Joe and Joe", is featured on national television after a visit by "Joe the Vice-President", and you decide to stamp "Greetings from Joe, Joe & Joe" on all of your merchandise.As a result, tourists are willing to pay $y more for your x than they would be willing to pay at any non-Joe store where x does not contain the coveted "Greetings from Joe, Joe & Joe" stamp.How does your output change in the short and long run (assuming capital is fixed in the short run but not in the long run and assuming it costs nothing to put the stamp on your products)?
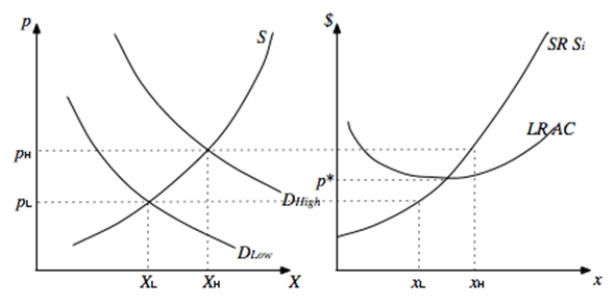
d.Suppose this town is located on the beach in North Carolina where there is a "high season" during the 6 warm months of the year and a "low season" during the 6 cool months of the year.Demand is high during the high season and low during the low season.On two recent visits to this town - one in the summer and one in the winter -- I noticed that prices for x where considerably higher during the high season.Explain how two different prices in different seasons could exist in an industry that is in long run equilibrium.Use side-by-side graphs of the market and Joe's business in your explanation, illustrating both the high demand DH and the low demand DL in the market.How do these different prices relate to the lowest point of the long run AC curve at Joe's business?
e.Suppose that I noticed one other thing on my recent two visits to this town: only half the souvenir shops are open in the winter while all are open in the summer.Is this compatible with our assumption that souvenir shops face decreasing returns to scale throughout (and no short run fixed costs)? (Hint: Think about what must be true for half the shops to close for 6 months - and what this implies for short run cost curves and shut down prices.)
(81) Verifieda. In the SR, price falls from p* to p' and output falls from x* to x' in each firm and from X* to X' in the industry. In the LR, price rises back to p* (because the long run AC curve has not changed), with each firm that remains going back to producing x* but market output t falling further to X". This implies that some firms must have existed -- and the number of firms falls. 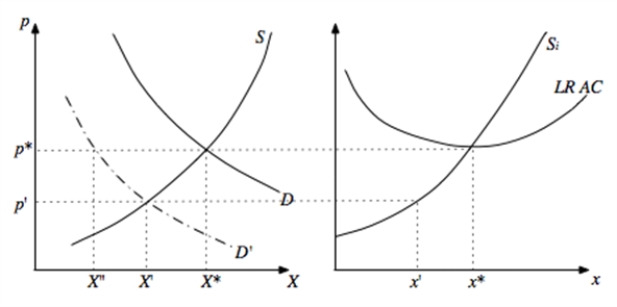 b. Nothing happens in the SR since license fees are sunk "costs" in the SR. In the LR, AC shifts down without the long run MC curve changing -- so the lowest point of the LR AC curve shifts down and to the left. Price falls to p' -- causing market output to rise to X' and each firm to reduce output to x'. This implies that firms must have entered -- and the number of firms has increased.
 c. Nothing changes in the market -- so p* remains unchanged. But Joe&Joe can now charge (p*+y). This leads to an increase in output by Joe&Joe from x* to x' in the SR and a further increase to x" in the LR when Joe&Joe can adjust capital.
 d. Each firm produces
 in the low season and x* in the high season. In order for firms to be making zero long run profit (which is necessary in long run equilibrium),
 has to fall below p* and
 has to fall above p*. Firms then make positive SR profit in the low season but negative LR profit -- which is exactly offset in the high season when firms make positive LR profit. This is a long run equilibrium because firms make zero annual LR profit and thus no firm wants to enter or exit.
 e. If some firms shut down and some stay open in the low season, it must be that firms are indifferent between shutting down and staying open in the low season. Thus, the firms that stay open must be making zero SR profit in the low season -- which means their price must be equal to the shut-down price at the lowest point of their SR AC curve. At that price, the market produces
 , with some firms producing
 and other firms producing zero in the low season. (To make up for the negative LR profit from the low season, it must also be the case, as in part (d), that the high season price
 lies above long run AC.)
This is not compatible with the assumption that firms face decreasing returns throughout (and no SR fixed costs). If this were the case, then the SR MC curve would be upward sloping throughout, with SR AC curves sharing the same vertical intercept but lying under the SR MC curves throughout. This would imply a shut-down price at which all firms would produce zero -- and would not allow for the observation of some firms producing and others shutting down in the low season. For this to happen, we need U-shaped SR AC curves -- for which we need initially increasing marginal product of labor which in turn implies increasing returns to scale at low levels of output. 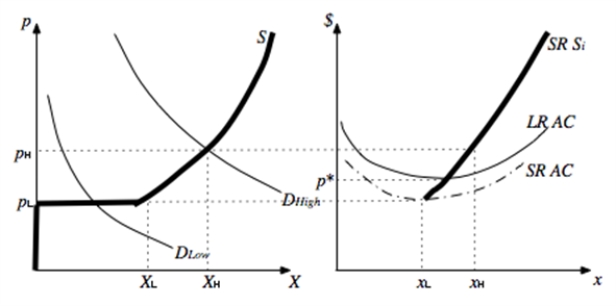
If firms differ in terms of their technologies, a drop in demand will cause a long run decrease in output price.
(77) VerifiedTrue
Suppose a price-taking firm uses a single input - labor - to produce an output x.The production technology has diminishing marginal product of labor throughout.
a.On a graph with labor hours on the horizontal and output on the vertical axis, illustrate the production frontier for this firm.
b.For a given wage rate w and output price p, illustrate three isoprofit curves corresponding to profit levels π < π'< π" -- indicating slopes and intercepts.Suppose the profit maximizing plan results in profit π'.Then use isoprofit to illustrate the profit maximizing production plan for the firm and show how w and p are related to the marginal product of labor at that plan.
c.Where on your graph do all cost-minimizing production plans lie?
d.On a graph with output on the horizontal and dollars on the vertical axis, illustrate the shape of the cost curve for the firm (holding fixed w).Then suppose that, in addition to labor costs, the firm has to pay a recurring (long run) fixed cost F.Where does the long run cost curve lie in relation to the initial (short run) cost curve you drew?
e.On a separate graph, illustrate the short run marginal and average cost curves.Then, on the same graph illustrate the long run marginal and average cost curves in the presence of the recurring fixed cost.f.Indicate where in your graph you can locate the short and long run supply curves for this firm.g.Call the industry in which our firm operates industry A.There is a second industry B that produces a different good y.Suppose that firms in industry B are identical to firms in industry A in the sense that they face the same production technology, the same prices w and p, and the same recurring fixed cost F.The only difference between industry A and industry B is that the market demand in industry A is shallower than the market demand in industry B - i.e.consumers in industry A are more responsive to price changes than consumers in industry B.Consider firm 1 operating in industry A and firm 2 operating in industry B.When both industries are in long-run equilibrium, do firms 1 and 2 produce the same level of output and sell that output at the same price? Explain.h.Suppose that all firms in these two industries rely exclusively on minimum wage workers.Now the government raises the minimum wage.We notice that, as a result of this increase in the minimum wage, each individual firm in both industries produces less in the new long run equilibrium.If the total number of firms across both industries A and B (together) remained the same, what happened to the number of firms in industry A and what happened to the number of firms in industry B?
(79) An increase in license fees -- a long run recurring fixed cost -- will lead to a drop in the number of firms competing in a competitive industry.
(76) If a firm makes negative short run profits, it will exit the industry in the long run.
(84) Economic actors in a competitive world think strategically in order to maintain profit.
(84) In a competitive industry, each firm has a cost function  (for a given set of input prices).Demand for the industry's output is
 .The (long run) equilibrium number of firms is
(for a given set of input prices).Demand for the industry's output is .The (long run) equilibrium number of firms is (78) Suppose all firms in an industry have a production technology described by the production function 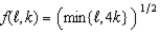 .The cost of labor is 2 and the cost of capital is 4, and each firm faces a recurring fixed cost of 300.
a.Derive the long run cost and average cost functions for each firm.(Hint: Given the shapes of the isoquants implied by the production function, you should be able to do this without solving a calculus problem.)
b.What is the long run equilibrium output price?
c.How much does each firm produce in long run equilibrium?
d.Suppose market demand is given by
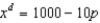 .How many firms are in the industry in long run equilibrium?
e.Suppose the industry is currently in long run equilibrium.Derive the short run cost function for each firm (assuming labor is variable but capital is fixed in the short run).f.Now suppose that demand falls to
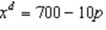 .What happens to output price in the short run? What happens to price and the number of firms in the long run?
.The cost of labor is 2 and the cost of capital is 4, and each firm faces a recurring fixed cost of 300.
a.Derive the long run cost and average cost functions for each firm.(Hint: Given the shapes of the isoquants implied by the production function, you should be able to do this without solving a calculus problem.)
b.What is the long run equilibrium output price?
c.How much does each firm produce in long run equilibrium?
d.Suppose market demand is given by .How many firms are in the industry in long run equilibrium?
e.Suppose the industry is currently in long run equilibrium.Derive the short run cost function for each firm (assuming labor is variable but capital is fixed in the short run).f.Now suppose that demand falls to .What happens to output price in the short run? What happens to price and the number of firms in the long run? (80) A decrease in the rental rate of capital can lead to a long run increase or decrease in the number of firms in the industry.
(78) A drop in output demand accompanied by a simultaneous drop in output supply will cause the output price to fall.
(78) Suppose a firm is making zero long run profit.Then it's short run profit cannot be negative.
(72) The long run market supply curve is formed by adding up individual firm supply curves in the industry.
(75) Equilibrium prices coordinate the actions of producers and consumers.
(94) Suppose gasoline stations operate with identical costs in a perfectly competitive industry.In each of the following cases, explain what happens to an individual gasoline station and what happens to the overall quantity of gasoline sold in the short and long run.Assume that labor is the only variable input in the short run.
a.Last year's tax returns from gasoline station owners show unusually high income for these owners because of the upward trend in prices this past year.So Congress passes a one-time "profits tax" based on these unusually high incomes last year.
b.Continue with part (a).After the imposition of the "profits tax" from part (a), Congress has to decide what to do with the revenues.The Texas Congressional delegation persuades the government that running a gasoline station is patriotic but difficult work - and that the Congress should put all the revenues from the "profits tax" into a trust fund which will be used to finance annual Christmas gifts in the form of a $10,000 check for all gasoline station owners from now on.
c.Moved by a Hollywood movie on global warming, a teary-eyed senator persuades Congress to impose a $2 per gallon tax on all gasoline sold at the pump.
d.After the industry settles into its new long run equilibrium (following the tax increase from (c)), the Congress decides to help out the gas station owners once more by subsidizing their equipment purchases through a tax credit - thereby lowering the rental rate they have to pay on their equipment.(Assume equipment is fixed in the short run, variable in the long run.)
e.True or False: Since the short run marginal cost curve measures only costs associated with variable inputs (like labor) and not with fixed inputs (like capital), the short run marginal cost curve in the new long run equilibrium (following the policy in part (d)) is the same as the short run marginal cost curve in the old equilibrium (before the policy in part (d)).Explain.
(81) The reason long run market supply curves are shallower than short run market supply curves is because individual firm supply curves are shallower in the long run than in the short run.
(81) Suppose Congress passes a one-time tax refund of all taxes paid by firms in an industry last year.This will lead to a drop in output price in the industry.
(78) Suppose all firms in a perfectly competitive industry have production processes characterized by the production function 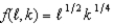 .Suppose the cost of labor is 20 and the cost of capital is 10.
a.Suppose that the industry is in long run equilibrium and that firms are using 1 unit of capital.What is the short run cost function of each firm?
b.Suppose there are 5,000 firms in long run equilibrium.What is the short run market supply function?
c.Suppose market demand is
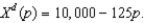 What is the equilibrium price?
d.Firms in this industry face a recurring fixed cost FC.What must FC be in order for this industry to indeed be in long run equilibrium with its 100 firms?
.Suppose the cost of labor is 20 and the cost of capital is 10.
a.Suppose that the industry is in long run equilibrium and that firms are using 1 unit of capital.What is the short run cost function of each firm?
b.Suppose there are 5,000 firms in long run equilibrium.What is the short run market supply function?
c.Suppose market demand is What is the equilibrium price?
d.Firms in this industry face a recurring fixed cost FC.What must FC be in order for this industry to indeed be in long run equilibrium with its 100 firms? (78) An increase in labor demand accompanied by a decline in labor supply cannot result in a decline in wages.
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)