



 Chat with AI
Exam 14: Accounting for Not-for-Profit Organizations

Exam 1: Introduction to Accounting and Financial Reporting for Government and Not-for-Profit Entities62 Questions
Exam 2: Principles of Accounting and Financial Reporting for State and Local Governments73 Questions
Exam 3: Governmental Operating Statement Accounts; Budgetary Accounting91 Questions
Exam 4: Accounting for Governmental Operating Activities–Illustrative Transactions and Financial Statements91 Questions
Exam 5: Accounting for General Capital Assets and Capital Projects83 Questions
Exam 6: Accounting for General Long-Term Liabilities and Debt Service75 Questions
Exam 7: Accounting for the Business-type Activities of State and Local Governments75 Questions
Exam 8: Accounting for Fiduciary Activities—Custodial and Trust Funds72 Questions
Exam 9: Financial Reporting of State and Local Governments66 Questions
Exam 10: Analysis of Government Financial Performance60 Questions
Exam 11: Auditing of Government and Not-for-Profit Organizations65 Questions
Exam 12: Budgeting and Performance Measurement60 Questions
Exam 13: Not-for-Profit Organizations—Regulatory, Taxation, and Performance Issues59 Questions
Exam 14: Accounting for Not-for-Profit Organizations77 Questions
Exam 15: Accounting for Colleges and Universities63 Questions
Exam 16: Accounting for Health Care Organizations63 Questions
Exam 17: Accounting and Reporting for the Federal Government66 Questions
Select questions type


A local philanthropist made an unconditional pledge to donate $100,000 to a not-for-profit organization to be paid in five equal installments of $20,000 beginning in two years. Under FASB standards the pledge would be recognized as:
(Multiple Choice)
4.8/5  (62)
(62) In the current year, the not-for-profit organization Save the Butterflies Foundation received cash of $500 to be used as the Foundation wishes and $1,000 to be used for butterfly research. Save the Butterflies also received pledges of $700 that it can use as it wishes and $600 for its building fund. All pledges are expected to be received next year. How much would Save the Butterflies report as contributions with donor restrictions in the current year?
(Multiple Choice)
4.8/5 (78)
(78) In the current year, the not-for-profit organization (NFP) How to Read Government Financial Reports received both cash of $1,000 and pledges of $2,000 to be used for teaching citizens how to read government financial reports. During the year the organization spent $1,500 teaching citizens to read financial statements. Assuming the NFP has a policy of spending its restricted resources first, in the current year what amount of contributions can be reclassified as without donor restrictions?
(Multiple Choice)
4.9/5 (77)
(77) The FASB requires the statement of financial position prepared by a not-for-profit organization to report net assets in three categories: net assets without donor restrictions, net investment in capital assets, and net assets with donor restrictions.
(True/False)
4.9/5 (82)
(82) Explain when donated materials should be recognized as a contribution and as an expense by a nongovernmental not-for-profit organization.
(Essay)
4.9/5 (89)
(89) According to the FASB Codification, donated materials are generally not recognized as contributions by a not-for-profit organization.
(True/False)
4.9/5 (81)
(81) The FASB Codification requires the following financial statements for all not-for-profit organizations:
(Multiple Choice)
4.9/5 (69)
(69) The not-for-profit organization Accountants Rule has a mission to promote the accounting profession in the local community. It is heavily supported by local accounting firms and businesses seeking to increase the number of individuals entering the profession. Following is the pre-closing trial balance for the organization.
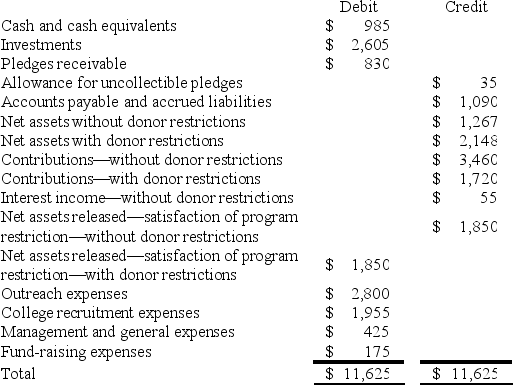 Prepare a statement of activities for the organization for the year ended December 31, 2020. (Negative amounts should be indicated by a minus sign.)
 (Essay)
4.7/5 (90)
(90) The FASB requires not-for-profit to prepare a statement of cash flow.
(True/False)
4.8/5 (100)
(100) Explain the accounting for contributions received by a financial intermediary under the FASB Codification.
(Essay)
4.9/5 (89)
(89) The FASB requires that the purchase of equity securities be initially recorded at the acquisition price and the purchase of debt securities be initially recorded at fair value.
(True/False)
4.8/5 (86)
(86) During the year a donor pledged $1,000,000 in funds to a not-for-profit private charter school. The school will receive the pledge if it is able to raise $500,000 in funds over the next year. According to the FASB, how would this pledge be recorded?
(Multiple Choice)
4.9/5 (75)
(75) Distinguish not-for-profit organizations from entities in the government and commercial sectors of the U.S. economy.
(Essay)
4.7/5 (71)
(71) A not-for-profit organization incurred $10,000 in management and general expenses in the current fiscal year. In the organization's statement of activities prepared in conformity with FASB standards, the $10,000 would be reported as:
(Multiple Choice)
5.0/5 (78)
(78) In accordance with the FASB Codification, which of the following would not be classified as a support expense by the not-for-profit organization Save Our Lakes?
(Multiple Choice)
4.9/5 (84)
(84) The FASB generally requires that not-for-profit organizations record unconditional pledges as support (contributions) only when received in cash.
(True/False)
4.7/5 (75)
(75) A not-for-profit organization that follows FASB standards must display the changes in all classes of net assets on which of the following statements?
(Multiple Choice)
4.9/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)