



 Chat with AI
Exam 5: Accounting for General Capital Assets and Capital Projects

Exam 1: Introduction to Accounting and Financial Reporting for Government and Not-for-Profit Entities62 Questions
Exam 2: Principles of Accounting and Financial Reporting for State and Local Governments73 Questions
Exam 3: Governmental Operating Statement Accounts; Budgetary Accounting91 Questions
Exam 4: Accounting for Governmental Operating Activities–Illustrative Transactions and Financial Statements91 Questions
Exam 5: Accounting for General Capital Assets and Capital Projects83 Questions
Exam 6: Accounting for General Long-Term Liabilities and Debt Service75 Questions
Exam 7: Accounting for the Business-type Activities of State and Local Governments75 Questions
Exam 8: Accounting for Fiduciary Activities—Custodial and Trust Funds72 Questions
Exam 9: Financial Reporting of State and Local Governments66 Questions
Exam 10: Analysis of Government Financial Performance60 Questions
Exam 11: Auditing of Government and Not-for-Profit Organizations65 Questions
Exam 12: Budgeting and Performance Measurement60 Questions
Exam 13: Not-for-Profit Organizations—Regulatory, Taxation, and Performance Issues59 Questions
Exam 14: Accounting for Not-for-Profit Organizations77 Questions
Exam 15: Accounting for Colleges and Universities63 Questions
Exam 16: Accounting for Health Care Organizations63 Questions
Exam 17: Accounting and Reporting for the Federal Government66 Questions
Select questions type


Which of the following is not True for capital projects funds?
(Multiple Choice)
4.8/5  (87)
(87) Which of the following is not a requirement that must be met to elect the "modified approach" to reporting certain eligible infrastructure assets?
(Multiple Choice)
4.8/5 (80)
(80) When a government experiences delays associated with a bond issuance, it is common practice to obtain temporary financing by use of bond anticipation notes.
(True/False)
4.9/5 (84)
(84) If bonds are sold at a premium to finance a capital project, what important question arises concerning the premium? Discuss the proper accounting for a bond premium in the capital projects fund, the debt service fund, and the government-wide statements assuming that the premium must be reserved for debt service.
(Essay)
4.8/5 (70)
(70) Which of the following statements regarding capital assets is not True?
(Multiple Choice)
4.9/5 (89)
(89) In late April, the Acme Construction Co. submitted a $1,200,000 progress billing on a construction contract. On May 2, the bill was approved for payment, subject to a ten percent retention, as provided by the contract. The amount that should be debited to Construction Expenditures is:
(Multiple Choice)
4.8/5 (73)
(73) Four new computers, for which the cost exceeded the city's capitalization threshold, were purchased for use in the city clerk's office using General Fund resources. Which of the following entries would be required to completely record this transaction?
(Multiple Choice)
4.9/5 (61)
(61) Capital projects funds generally do not use the Encumbrances control account.
(True/False)
5.0/5 (87)
(87) The following balances are included in the subsidiary records of Carrollwood: 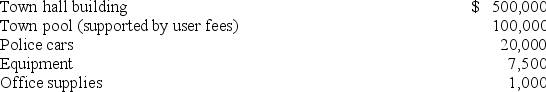 What is the total amount of general capital assets held by the town?
 (Multiple Choice)
4.9/5 (68)
(68) The following items were included in Castle City's General Fund expenditures for the year ended June. 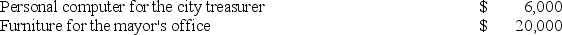 How much should be classified as capital assets in Castle City's General Fund balance sheet at June 30?
 (Multiple Choice)
4.8/5 (63)
(63) GASB standards require that general capital assets be recorded in the government-wide statements at:
(Multiple Choice)
4.8/5 (93)
(93) The City of McNeely sold bonds in the amount of $25,000,000 to finance the construction of a public health center. The bonds are serial bonds and were sold at par on January 1, the first day of a fiscal year. Shortly thereafter a construction contract in the amount of $22,000,000 was signed and the contractor commenced work. By year-end the contractor had been paid in full for all billings to date amounting to $12,000,000.
Prepare, in general journal form, all journal entries that should have been made during the fiscal year ended December 31 to record the preceding information in the capital projects fund. (No closing entry is required).
(Essay)
4.7/5 (74)
(74) Interest incurred during construction of general capital assets cannot be capitalized as part of the cost of those assets.
(True/False)
4.8/5 (81)
(81) The disposal of a general capital asset, resulting in no revenue or expenditure to the government, is recorded only in the governmental activities accounts.
(True/False)
4.9/5 (70)
(70) Intangible assets are defined by the GASB as capital assets that lack physical substance, have a useful life of more than one reporting period, and are nonfinancial in nature.
(True/False)
4.9/5 (82)
(82) The acquisition of long-lived assets under a lease agreement does not require any asset recognition in the accounts of any governmental fund.
(True/False)
4.8/5 (62)
(62) For each of the following definitions, select the key term from the list that relate to general capital assets and capital projects.
A. Bond anticipation notes
B. Infrastructure assets
C. Service Concession Arrangements
D. General capital assets
E. Capital projects funds
F. Asset impairment
G. Intangible assets
H. Depreciation
________ 1. Assets that lack physical substance and are nonfinancial in nature
________ 2. Short-term interest-bearing instruments issued by a government with a plan to replace with longer-term debt
________ 3. Roads, bridges, curbs and gutters, streets, sidewalks, and drainage systems installed for the common good
________ 4. Capital assets of a government that are not recorded in a proprietary or fiduciary fund
________ 5. Significant, unexpected decline in the service utility of a capital asset
(Essay)
4.8/5 (89)
(89) In 2020, Sunrise City signed a contract in the amount of $8,000,000 for the construction of a new city hall. Expenditures were $4,000,000 in 2020 and $2,050,000 in 2021, which included a change to the original construction design in the amount of $50,000. What amount should be added to capital assets in the governmental activities accounts in 2021?
(Multiple Choice)
4.7/5 (98)
(98) Which of the following activities or transactions would normally not be accounted for in a capital projects fund?
(Multiple Choice)
4.8/5 (75)
(75) Prepare journal entries for the following related transactions in the fund and activity journals affected: (If no entry is required for a transaction/event, select "No Journal Entry Required" in the first account field.)
1. A capital projects fund issued $5,000,000, 4 percent bonds for $5,050,000 to finance improvements of a park. Premiums received are to be used to service the debt issue.
2. The Parks and Recreation Special Revenue Fund transferred $250,000 for use in construction.
3. A construction contract was awarded in the amount of $5,200,000.
4. A bill was received from the contractor for $2,600,000.
5. The contractor's bill is paid, and 5% retainage is withheld.
6. The park renovations were completed and the final bill of $2,600,000 was received. The contractor's bill and retainages are approved for payment in full. Total construction expenditures were allocated as follows: $5,000,000 to building, and the remainder to equipment.
7. The capital projects fund temporary accounts were closed, and the capital projects fund was closed by transferring remaining funds to the debt service fund for use in debt repayment.
(Essay)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)