



 Chat with AI
Exam 9: Interest Rate Risk II

Exam 1: Why Are Financial Institutions Special90 Questions
Exam 2: Deposit-Taking Institutions43 Questions
Exam 3: Finance Companies71 Questions
Exam 4: Securities, Brokerage, and Investment Banking91 Questions
Exam 5: Mutual Funds, Hedge Funds, and Pension Funds61 Questions
Exam 6: Insurance Companies80 Questions
Exam 7: Risks of Financial Institutions110 Questions
Exam 8: Interest Rate Risk I110 Questions
Exam 9: Interest Rate Risk II116 Questions
Exam 10: Credit Risk: Individual Loans112 Questions
Exam 11: Credit Risk: Loan Portfolio and Concentration Risk51 Questions
Exam 12: Liquidity Risk85 Questions
Exam 13: Foreign Exchange Risk87 Questions
Exam 14: Sovereign Risk89 Questions
Exam 15: Market Risk95 Questions
Exam 16: Off-Balance-Sheet Risk101 Questions
Exam 17: Technology and Other Operational Risks107 Questions
Exam 18: Liability and Liquidity Management38 Questions
Exam 19: Deposit Insurance and Other Liability Guarantees54 Questions
Exam 20: Capital Adequacy102 Questions
Exam 21: Product and Geographic Expansion114 Questions
Exam 22: Futures and Forwards234 Questions
Exam 23: Options, Caps, Floors, and Collars113 Questions
Exam 24: Swaps95 Questions
Exam 25: Loan Sales83 Questions
Exam 26: Securitization Index98 Questions
Select questions type


A bond is scheduled to mature in five years. Its coupon rate is 9 percent with interest paid annually. This $1,000 par value bond carries a yield to maturity of 10 percent. Calculate the percentage change in this bond's price if interest rates on comparable risk securities increase to 11 percent. Use the duration valuation equation.
(Multiple Choice)
4.9/5  (83)
(83) The numbers provided are in millions of dollars and reflect market values: 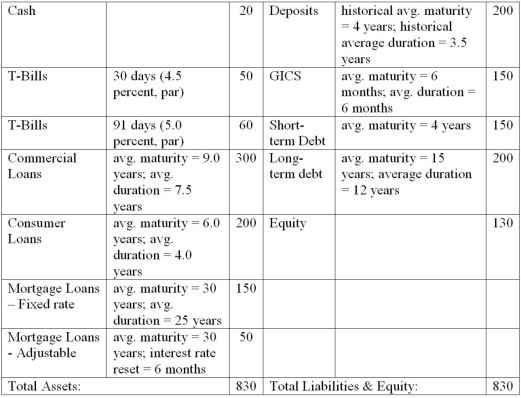 What is the leverage-adjusted duration gap of the FI?
 (Multiple Choice)
4.8/5 (85)
(85) The following is an FI's balance sheet ($millions). 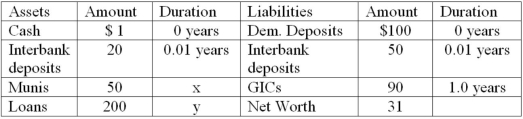 Notes to Balance Sheet: Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. GICs are 1-year pure discount certificates of deposit paying 4.75 percent.
What will be the impact, if any, on the market value of the bank's equity if all interest rates increase by 75 basis points?
Notes to Balance Sheet: Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. GICs are 1-year pure discount certificates of deposit paying 4.75 percent.
What will be the impact, if any, on the market value of the bank's equity if all interest rates increase by 75 basis points? (Multiple Choice)
4.8/5 (82)
(82) Setting the duration of the assets higher than the duration of the liabilities will exactly immunize the net worth of an FI from interest rate shocks.
(True/False)
4.8/5 (80)
(80) Consider a five-year, 8 percent annual coupon bond selling at par of $1,000. Using present value bond valuation techniques, calculate the exact price of the bond after the interest rate increase of 20 basis points.
(Multiple Choice)
4.8/5 (67)
(67) An FI can immunize its portfolio by matching the maturity of its asset with its liabilities.
(True/False)
5.0/5 (82)
(82) When does "duration" become a less accurate predictor of expected change in security prices?
(Multiple Choice)
4.8/5 (74)
(74) The immunization of a portfolio against interest rate risk means that the portfolio will neither gain nor lose value when interest rates change.
(True/False)
4.8/5 (87)
(87) The greater is convexity, the more insurance a portfolio manager has against interest rate increases and the greater potential gain from rate decreases.
(True/False)
4.8/5 (88)
(88) An FI has financial assets of $800 and equity of $50. If the duration of assets is 1.21 years and the duration of all liabilities is 0.25 years, what is the leverage-adjusted duration gap?
(Multiple Choice)
4.8/5 (80)
(80) Immunization of an FIs net worth requires the duration of the liabilities to be adjusted for the amount of leverage on the balance sheet.
(True/False)
4.7/5 (87)
(87) The following information is about current spot rates for Second Duration Savings' assets (loans) and liabilities (CDs). All interest rates are fixed and paid annually. 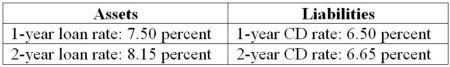 If the FI finances a $500,000 2-year loan with a $400,000 1-year CD and equity, what is the leveraged adjusted duration gap of this position? Use your answer to the previous question.
 (Multiple Choice)
4.9/5 (78)
(78) Consider a five-year, 8 percent annual coupon bond selling at par of $1,000. If interest rates increase by 20 basis points, what is the approximate change in the market price using the duration approximation?
(Multiple Choice)
4.7/5 (91)
(91) Which of the following is indicated by high numerical value of the duration of an asset?
(Multiple Choice)
4.9/5 (96)
(96) Managers can achieve the results of duration matching by using these to hedge interest rate risk.
(Multiple Choice)
4.9/5 (72)
(72) In duration analysis, the times at which cash flows are received are weighted by the relative importance in present value terms of the cash flows arriving at each point in time.
(True/False)
4.9/5 (92)
(92) Third Duration Investments has the following assets and liabilities on its balance sheet. The two-year Treasury notes are zero coupon assets. Interest payments on all other assets and liabilities occur at maturity. Assume 360 days in a year. 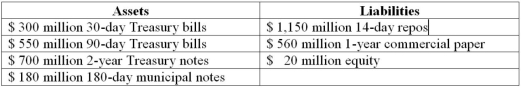 What is the duration of the assets?
 (Multiple Choice)
4.9/5 (80)
(80) Immunizing the net worth ratio requires that the duration of the assets be set equal to the duration of the liabilities.
(True/False)
4.9/5 (76)
(76) The following is an FI's balance sheet ($millions). 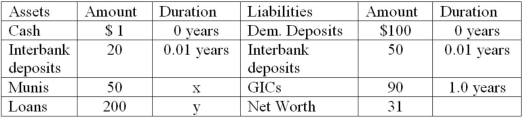 Notes to Balance Sheet: Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. GICs are 1-year pure discount certificates of deposit paying 4.75 percent.
What is the duration of the municipal notes (the value of x)?
Notes to Balance Sheet: Munis are 2-year 6 percent annual coupon municipal notes selling at par. Loans are floating rates, repriced quarterly. Spot discount yields for 91-day Treasury bills are 3.75 percent. GICs are 1-year pure discount certificates of deposit paying 4.75 percent.
What is the duration of the municipal notes (the value of x)? (Multiple Choice)
4.9/5 (81)
(81) An FI purchases a $9.982 million pool of commercial loans at par. The loans have an interest rate of 8 percent, a maturity of five years, and annual payments of principal and interest that will exactly amortize the loan at maturity. What is the duration of this asset?
(Multiple Choice)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)