



 Chat with AI
Exam 7: Perfect Competition

Exam 1: Introducing the Economic Way of Thinking177 Questions
Exam 1: A: Appendix: Applying Graphs to Economics69 Questions
Exam 2: Production Possibilities,Opportunity Cost,and Economic Growth200 Questions
Exam 3: Part 1: Market Demand and Supply250 Questions
Exam 3: Part 2: Market Demand and Supply106 Questions
Exam 4: Markets in Action250 Questions
Exam 5: Price Elasticity of Demand177 Questions
Exam 6: Production Costs249 Questions
Exam 7: Perfect Competition222 Questions
Exam 8: Monopoly170 Questions
Exam 9: Monopolistic Competition and Oligopoly161 Questions
Exam 10: Labor Markets and Income Distribution180 Questions
Exam 11: Gross Domestic Product202 Questions
Exam 12: Business Cycles and Unemployment194 Questions
Exam 13: Inflation127 Questions
Exam 14: Aggregate Demand and Supply188 Questions
Exam 14: A: Appendix: The Self-Correcting Aggregate Demand and Supply Model83 Questions
Exam 15: Fiscal Policy201 Questions
Exam 16: The Public Sector127 Questions
Exam 17: Federal Deficits,Surpluses,and the National Debt97 Questions
Exam 18: Money and the Federal Reserve System154 Questions
Exam 19: Money Creation246 Questions
Exam 20: Monetary Policy214 Questions
Exam 20: A: Appendix: Policy Disputes Using the Self-Correcting Aggregate Demand and Supply Model31 Questions
Exam 21: International Trade and Finance246 Questions
Exam 22: Economies in Transition104 Questions
Exam 23: Growth and the Less-Developed Countries116 Questions
Select questions type


A firm operating in a perfectly competitive market is a price taker because:
(Multiple Choice)
4.8/5  (64)
(64) Exhibit 7-3 Cost per unit curves
 -In Exhibit 7-3,if the price of the firm's product is $2.00 per unit,the firm will produce:
 (Multiple Choice)
4.7/5 (82)
(82) 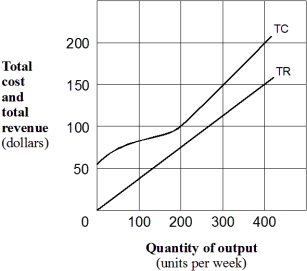 -In Exhibit 7-14,if output is at 200 units per week,total economic profit for the firm is:
 (Multiple Choice)
4.9/5 (81)
(81) The price-taker firm should discontinue production immediately if:
(Multiple Choice)
4.8/5 (66)
(66) A competitive firm maximizes its profits (or minimizes is losses)by producing the quantity where the market price equals the firm's:
(Multiple Choice)
4.9/5 (82)
(82) In the short run,why would a firm in a perfectly competitive market shut down production if the prevailing market price falls below the lowest possible average variable cost?
(Multiple Choice)
4.8/5 (82)
(82) Exhibit 7-15 Short-run cost curves for E-Z Care lawn mowing company
 -In Exhibit 7-15,if the market price of mowing lawns is $16 per lawn,then E-Z-Care will earn the biggest profit by mowing:
 (Multiple Choice)
4.9/5 (86)
(86) Exhibit 7-17 Marginal revenue and cost per unit curves
 -As shown in Exhibit 7-17,the firm will produce in the short run if the price is at least equal to:
 (Multiple Choice)
4.8/5 (84)
(84) In a perfectly competitive industry,assume the short-run average total cost increases as the output of the industry expands.In the long run,the industry supply curve will:
(Multiple Choice)
4.9/5 (73)
(73) Consider a firm operating with the following: price = 10; MR = 10; MC = 10; ATC = 10.This firm is:
(Multiple Choice)
4.7/5 (65)
(65) Which of the following is a characteristic of a competitive price-taker market?
(Multiple Choice)
4.8/5 (83)
(83) Which of the following best illustrates a perfectly competitive market?
(Multiple Choice)
4.7/5 (70)
(70) Exhibit 7-18 A typical firm in a perfectly competitive market
 -In Exhibit 7-18,assume the perfectly competitive firm is in long-run equilibrium and there is an increase in demand.As a result,the firm in the short run will increase output along its:
 (Multiple Choice)
4.9/5 (73)
(73) If there is a permanent increase in demand for the product of a perfectly competitive industry,the process of transition to a new long-run equilibrium will include:
(Multiple Choice)
4.8/5 (79)
(79) In long-run equilibrium,which of the following is not equal to price for a perfectly competitive firm?
(Multiple Choice)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)