



 Chat with AI
Exam 3: Demand and Supply

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem439 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Measuring GDP and Economic Growth396 Questions
Exam 5: Monitoring Jobs and Inflation407 Questions
Exam 6: Economic Growth353 Questions
Exam 7: Finance, Saving, and Investment240 Questions
Exam 8: Money, The Price Level, and Inflation583 Questions
Exam 9: The Exchange Rate and the Balance of Payments481 Questions
Exam 10: Aggregate Supply and Aggregate Demand418 Questions
Exam 11: Expenditure Multipliers454 Questions
Exam 12: Inflation, Jobs, and the Business Cycle401 Questions
Exam 13: Fiscal Policy263 Questions
Exam 14: Monetary Policy225 Questions
Exam 15: International Trade Policy197 Questions
Exam 16: Introduction23 Questions
Exam 17: Monitoring Macroeconomic Performance11 Questions
Exam 18: Macroeconomic Trends19 Questions
Exam 19: Macroeconomic Fluctuations23 Questions
Exam 20: Macroeconomic Policy25 Questions
Select questions type


Price (dollars per pound of cat food) Quantity demanded (tons of cat food per year) Quantity supplied (tons of cat food per year) 1.00 52 15 1.50 46 26 2.00 43 34 2.50 40 30 3.00 35 44
-The above table gives the demand and supply schedules for cat food.If the price is $1.00 per pound of cat food,will there be a shortage,a surplus,or is this price the equilibrium price?
If there is a shortage,how much is the shortage?
If there is a surplus,how much is the surplus?
If $3.00 is the equilibrium price,what is the equilibrium quantity?
(Essay)
5.0/5  (82)
(82) 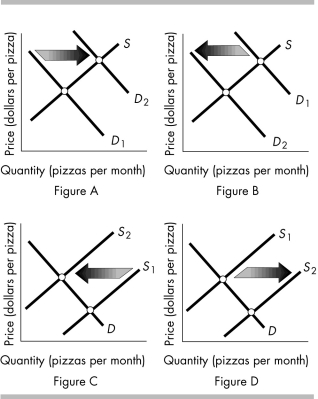 -The above figure shows the market for pizza.Which figure shows the effect of an increase in the price of a complement such as soda?
 (Multiple Choice)
4.9/5 (86)
(86) Using supply-and-demand diagrams,show and explain the effects of the following events on the price of CD-Rs and the quantity of CD-Rs sold.For each event,identify which of the determinants of demand or supply is affected,how it influences demand or supply,and what happens to the equilibrium price and quantity.
a) The price of a CD burner falls.
b) Workers who make CD-Rs get a pay raise.
c) Producers introduce new cost-saving technologies in their CD-R production plants.
d) Consumers' incomes increase and CD-Rs are a normal good.
e) Free peer-to-peer music exchange through the Internet becomes legal.
(Essay)
4.9/5 (75)
(75) If the price is above the equilibrium price,then there is a
(Multiple Choice)
4.8/5 (70)
(70) Blank DVDs and prerecorded DVDs are substitutes in production.An increase in the price of a blank DVD will lead to
(Multiple Choice)
4.9/5 (82)
(82) Consider the market for broccoli.If the price of a pound of broccoli increases,what happens to the supply of broccoli?
(Multiple Choice)
4.9/5 (69)
(69) If there exists a shortage in the market for snowmobiles,then the price of a snowmobile will
(Multiple Choice)
4.9/5 (71)
(71) If the price of lumber rises,then,in the market for sawdust,
(Multiple Choice)
4.8/5 (78)
(78) If a decrease in the price of gasoline increases the demand for large cars,then
(Multiple Choice)
4.9/5 (87)
(87) When graphing a demand curve for corn,we are showing the relationship between the quantity demanded of corn and the
(Multiple Choice)
4.7/5 (70)
(70) An increase in the number of suppliers in a market results in a
(Multiple Choice)
4.9/5 (89)
(89) The equilibrium price will rise and the equilibrium quantity might increase,decrease,or stay the same when the
(Multiple Choice)
4.8/5 (74)
(74) Coffee and sugar are complements.If the supply curve of coffee shifts leftward because of poor weather,then there will be
(Multiple Choice)
4.8/5 (90)
(90) Which of the following shifts the supply curve of broccoli?
(Multiple Choice)
5.0/5 (80)
(80) The law of demand states that the quantity of a good demanded varies
(Multiple Choice)
4.9/5 (78)
(78) The "law of demand" states that,other things remaining the same,the quantity demanded of any good is
(Multiple Choice)
4.8/5 (87)
(87) 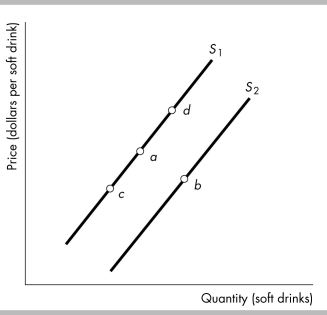 -The figure above shows supply curves for soft drinks.Suppose the economy is at point a.An increase in the price of a soft drink is shown as a movement from point a to
 (Multiple Choice)
4.8/5 (79)
(79) A fall in the price of a good causes producers to reduce the quantity of the good they are willing to produce.This fact illustrates
(Multiple Choice)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)