



 Chat with AI
Exam 9: Perfect Competition

Exam 1: Introduction: What Is Economics163 Questions
Exam 2: The Key Principles of Economics199 Questions
Exam 3: Exchange and Markets133 Questions
Exam 4: Demand,supply,and Market Equilibrium279 Questions
Exam 5: Elasticity: a Measure of Responsiveness170 Questions
Exam 6: Market Efficiency and Government Intervention120 Questions
Exam 7: Consumer Choice: Utility Theory and Insights From Neuroscience114 Questions
Exam 8: Production Technology and Cost163 Questions
Exam 9: Perfect Competition167 Questions
Exam 10: Monopoly and Price Discrimination127 Questions
Exam 11: Market Entry and Monopolistic Competition112 Questions
Exam 12: Oligopoly and Strategic Behavior116 Questions
Exam 13: Controlling Market Power: Antitrust and Regulation81 Questions
Exam 14: Imperfect Information: Adverse Selection and Moral Hazard98 Questions
Exam 15: Public Goods and Public Choice95 Questions
Exam 16: External Costs and Environmental Policy100 Questions
Exam 17: The Labor Market and the Distribution of Income177 Questions
Exam 18: International Trade and Public Policy224 Questions
Select questions type


What happens to a firm's profit-maximizing level of output if the price of the product rises? Use a graph to explain your answer.
(Essay)
4.9/5  (87)
(87) Assume that a smartphone maker operates in a perfectly competitive market producing 25,000 smartphones per day.At this output level,price is less than this firm's marginal cost.It follows that producing one more smartphone will cause this firm's
(Multiple Choice)
4.9/5 (82)
(82) A pasta producer is in a perfectly competitive market.To maximize profits,the pasta producer should produce the output level where
(Multiple Choice)
4.7/5 (71)
(71) UG Tech,Inc.is a perfectly competitive firm producing wireless earbuds where marginal revenue is equal to marginal cost.The current market price of wireless earbuds is $30.00.UG Tech,Inc.sells 500 wireless earbuds.Its short-run average variable cost is $10.00 and its average fixed cost is $5.00.What should UG Tech,Inc.do?
(Multiple Choice)
4.9/5 (79)
(79) In a perfectly competitive market,an individual firm faces a perfectly elastic demand curve.
(True/False)
5.0/5 (73)
(73) 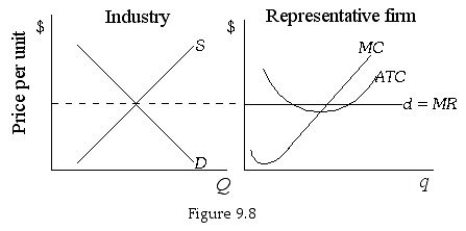 -Refer to Figure 9.8.In the long run,
What is the shape of the marginal revenue curve for a perfectly competitive firm? Why is it that way?
(Essay)
4.8/5 (90)
(90) A firm suffering economic losses decides whether or not to produce in the short run on the basis of
(Multiple Choice)
4.8/5 (80)
(80) Recall the Application about the price and supply of blueberries to answer the following question(s).
-According to the Application,the blueberry industry is roughly a(n)
(Multiple Choice)
4.9/5 (67)
(67)  -Refer to Table 9.1.The shut-down point for this firm is a price of
 (Multiple Choice)
4.9/5 (77)
(77) If a firm is indifferent between operating and shutting down in the short run,then it must be true that
(Multiple Choice)
4.9/5 (76)
(76)  -Refer to Figure 9.5.If this farmer is maximizing his profits,his total variable cost is
 (Multiple Choice)
4.8/5 (64)
(64) The long-run industry supply curve is positively sloped for a decreasing-cost industry.
(True/False)
4.8/5 (82)
(82) Explain when a firm will shut down to minimize losses.Draw a graph to illustrate this situation.
(Essay)
4.7/5 (77)
(77)  -Refer to Figure 9.4.If the market price of hay falls to $18,then to maximize profits this farmer should produce
 (Multiple Choice)
4.9/5 (72)
(72)  -Refer to Figure 9.6.At a market price of $20,this profit-maximizing firm would earn ________ in economic profit.
 (Multiple Choice)
4.9/5 (79)
(79) Recall the Application about the shut-down price for zinc to answer the following question(s).
-Recall the Application.What is the shut-down price for the zinc mines?
(Multiple Choice)
4.8/5 (73)
(73) In an increasing-cost industry,firms can enter and leave in the long run.
(True/False)
4.8/5 (99)
(99) Recall the Application about the demand and price for margarine to answer the following question(s).
-Recall the Application.The margarine industry is an example of a constant-cost industry because as the total output of the industry changes,the price of the key inputs to the production of margarine don't change.As a result,
(Multiple Choice)
4.9/5 (87)
(87) For oligopolistic industries,demand is more elastic than the demand facing monopolistically competitive industries.
(True/False)
4.7/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)