



 Chat with AI
Exam 12: Inventories and Cost of Goods Sold

Exam 1: The Role of the Public Accountant in the American Economy56 Questions
Exam 2: Professional Standards69 Questions
Exam 3: Professional Ethics76 Questions
Exam 4: Legal Liability of Cpas61 Questions
Exam 5: Audit Evidence and Documentation92 Questions
Exam 6: Audit Planning, understanding the Client, assessing Risks, and Responding84 Questions
Exam 7: Internal Control97 Questions
Exam 8: Consideration of Internal Control in an Information Technology Environment76 Questions
Exam 9: Audit Sampling91 Questions
Exam 10: Cash and Financial Investments69 Questions
Exam 11: Accounts Receivable, notes Receivable, and Revenue73 Questions
Exam 12: Inventories and Cost of Goods Sold64 Questions
Exam 13: Property,plant,and Equipment: Depreciation and Depletion46 Questions
Exam 14: Accounts Payable and Other Liabilities57 Questions
Exam 15: Debt and Equity Capital45 Questions
Exam 16: Auditing Operations and Completing the Audit83 Questions
Exam 17: Auditors Reports73 Questions
Exam 18: Integrated Audits of Public Companies49 Questions
Exam 19: Additional Assurance Services: Historical Financial Information65 Questions
Exam 20: Additional Assurance Services: Other Information55 Questions
Exam 21: Internal, operational, and Compliance Auditing51 Questions
Select questions type


Which of the following is true about the auditors' observation of the client's physical inventory?
(Multiple Choice)
4.8/5  (78)
(78) The proper cutoff of inventories is best achieved when receiving reports and purchase invoices surrounding the year-end are examined.
(True/False)
4.8/5 (85)
(85) To assure that all purchases are authorized before payment is made,accounting department personnel should match the vendor's invoice to:
(Multiple Choice)
4.8/5 (66)
(66) Auditors should not review the client's planning of the physical inventory.
(True/False)
4.8/5 (87)
(87) The auditors will usually trace the details of the test counts made during the observation of the physical inventory taking to a final inventory schedule.This audit procedure is undertaken to provide evidence that items physically present and observed by the auditors at the time of the physical inventory count are:
(Multiple Choice)
4.9/5 (88)
(88) Your audit client,Banner,is a retail sporting goods store.You are currently working on the inventory portion of the audit.In obtaining audit evidence in support of financial statement assertions,the auditor develops specific audit objectives in response to those assertions.Audit procedures are then selected to accomplish audit objectives.
For each specific inventory audit objective listed,select the most closely related account balance financial statement assertion and the most appropriate audit procedure.Financial statement assertions and audit procedures may be selected once,more than once,or not at all.
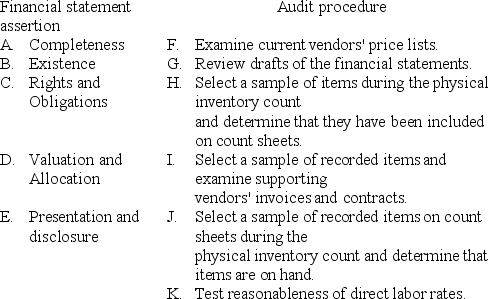 Specific audit objectives 1 The entity has legal title to inventories. 2 Recorded inventory quantities include all products on hand. 3 Inventories are reduced, when appropriate, to replacement costs or net realizable value. 4 Cost of inventories is properly calculated. 5 The major categories of inventories and their basis of valuation are adequately rep orted in the financial statements.
(Essay)
4.8/5 (79)
(79) The client's physical count of inventories is lower than the inventory quantities in the perpetual records.This could be the result of a failure to record:
(Multiple Choice)
4.9/5 (75)
(75) In auditing a client's inventory,the auditors must be concerned with the detection of goods that are both damaged and obsolete.
a.Why are the auditors concerned with detecting damaged and obsolete goods?
b.How do the auditors test for damaged goods in the client's inventory?
c.How do the auditors test for obsolete goods in the client's inventory?
(Essay)
4.8/5 (81)
(81) Which of the following is an auditor least likely to consider a departure from U.S.generally accepted accounting principles?
(Multiple Choice)
4.8/5 (89)
(89) Which one of the following procedures would not be appropriate for the auditors in discharging their responsibilities concerning the client's physical inventories?
(Multiple Choice)
4.8/5 (70)
(70) The most reliable procedure for an auditor to use to test the existence of a client's inventory at an outside location would be to:
(Multiple Choice)
4.8/5 (75)
(75) Which of the following is an internal control weakness for a company whose inventory of supplies consists of a large number of individual items?
(Multiple Choice)
4.7/5 (87)
(87) Which of the following best describes the auditors' response to a client's use of statistical sampling techniques to estimate the inventory?
(Multiple Choice)
4.9/5 (77)
(77) The lower-of-cost-or-market test by the auditors is generally designed to assure that inventories are valued at or above their net realizable values.
(True/False)
4.7/5 (86)
(86) An auditor has accounted for a sequence of inventory tags and is now going to trace information on a representative number of tags to the inventory summary sheets.Which assertion does this procedure relate to most directly?
(Multiple Choice)
4.9/5 (82)
(82) For good internal control over purchase transactions,purchases should be documented by a purchase requisition by the department needing the goods.
(True/False)
4.8/5 (78)
(78) After accounting for a sequence of inventory tags,an auditor traces a sample of tags to the physical inventory listing to obtain evidence that all items:
(Multiple Choice)
4.7/5 (76)
(76) Effective internal control for purchases generally can be achieved in a well-planned organizational structure with a separate purchasing department that has:
(Multiple Choice)
4.9/5 (84)
(84) The use of a tagging system for inventory taking is designed to prevent double counting of goods.
(True/False)
4.9/5 (80)
(80) An inventory turnover analysis is useful to the auditor because it may detect:
(Multiple Choice)
4.9/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)