



 Chat with AI
Exam 9: Audit Evidence

Exam 1: The Demand for Audit and Other Assurance Services69 Questions
Exam 2: The Public Accounting Profession and Audit Quality68 Questions
Exam 3: Legal Liability55 Questions
Exam 4: Professional Judgment and Ethics72 Questions
Exam 5: Audit Responsibilities and Objectives67 Questions
Exam 6: Client Acceptance and Planning the Audit60 Questions
Exam 7: Materiality and Risk65 Questions
Exam 8: Internal Controls and Control Risk62 Questions
Exam 9: Audit Evidence80 Questions
Exam 10: Audit Strategy and Audit Program67 Questions
Exam 11: Audit Sampling Concepts67 Questions
Exam 12: Audit of the Revenue Cycle134 Questions
Exam 13: Audit of the Acquisition and Payment Cycle64 Questions
Exam 14: Audit of the Inventory and Distribution Cycle66 Questions
Exam 15: Audit of the Human Resources and Payroll Cycle66 Questions
Exam 16: Audit of the Capital Acquisition and Repayment Cycle66 Questions
Exam 17: Audit of Cash Balances65 Questions
Exam 18: Completing the Audit65 Questions
Exam 19: Audit Reports on Financial Statements67 Questions
Exam 20: Other Assurance and Nonassurance Services59 Questions
Select questions type


To improve the appropriateness of audit evidence, the auditor should
(Multiple Choice)
4.9/5  (80)
(80) Reperformance is often conducted using computer-assisted audit techniques. The most effective use of generalized audit software for reperformance would be to
(Multiple Choice)
4.8/5 (87)
(87) "Use of comparisons and relationships to determine whether account balances or other data appear reasonable" is a definition of
(Multiple Choice)
4.9/5 (75)
(75) The following are audit procedures in the sales and collection cycle.
1. Inspect a sample of shipping documents to determine if each has a sales invoice number included on it.
2. Discuss with the sales manager whether any sales allowances have been granted after the balance sheet date that may apply to the current period.
3. Add the columns on the aged trial balance and compare the total with the general ledger.
4. Observe whether the controller makes an independent comparison of the total in the general ledger with the trial balance of accounts receivable.
5. For the month of May, count the approximate number of shipping documents filed in the shipping department and compare the total with the number of sales invoices in the sales journal.
6. Compare the date on a sample of shipping documents throughout the year with related duplicate sales invoices and the accounts receivable master file.
7. Examine a sample of customer orders and see if each has a credit authorization.
8. Send letters directly to former customers whose accounts have been written off as uncollectible to determine if any have actually been paid.
9. Examine the master file of accounts receivable to see if each has an indication of "C" for a regular customer, "N" for interest-bearing receivables, and "R" for related parties.
10. Compare the date on a sample of shipping documents a few days before and after the balance sheet date with related sales journal transactions.
Required:
For each procedure, identify the type of evidence being used. For each procedure, identify either the transaction-related audit objective(s) being met or the balance-related audit objective(s) being met.
(Essay)
4.8/5 (64)
(64) Ordinarily, the working papers can be provided to someone else only with the express permission of the client. This is the case even if the papers are
(Multiple Choice)
5.0/5 (80)
(80) In addition to including on each working paper the name of the client, the period covered, the date of preparation, and an index code, each working paper should clearly include
(Multiple Choice)
4.8/5 (84)
(84) Which of the following is an example of subjective evidence?
(Multiple Choice)
4.8/5 (66)
(66) An example of a document that the auditor receives from the client, but which was prepared by someone outside the client's organization, is a(n)
(Multiple Choice)
4.9/5 (70)
(70) When an auditor calculates the gross margin as a percent of sales and compares it with previous periods, this type of evidence is called
(Multiple Choice)
4.8/5 (79)
(79) Which of the following types of evidence would be considered most reliable in the audit of accounts payable?
(Multiple Choice)
4.9/5 (76)
(76) When the current year's unaudited trial balance amounts are compared to the prior year's audited trial balance amounts,
(Multiple Choice)
4.7/5 (92)
(92) Confirmations from outside organizations such as banks and law firms are
(Multiple Choice)
4.8/5 (86)
(86) An auditor is conducting the audit of the financial statements of a retail department store. The auditor is aware that he must obtain sufficient appropriate evidence with respect to various audit assertions associated with management assertions and thus with material financial statement amounts.
The following is a list of specific audit procedures the auditor plans to perform:
1. Send negative external confirmation requests to a large sample of the store's customers who have balances due on account at year end.
2. Perform test counts of goods on hand during the company's normal physical inventory taking, one month prior to the year end.
3. Examine receiving reports dated prior to the year end that have not been matched to vendor invoices.
4. Review paid invoices and supporting documents for amounts classified as repair and maintenance expense for large or unusual items.
5. Examine audited financial statements of several foreign companies in which the client owns shares, and which are being held as temporary investments.
Required:
For each of the five audit procedures listed, describe only the PRIMARY management assertion being tested, the PRIMARY audit assertion being tested, and the quality of evidence (high, medium, low) obtained, explaining WHY the evidence is the quality level you specify.
(Essay)
4.8/5 (83)
(83) When comparing the reliability of external versus internal documents, the external documents are generally considered
(Multiple Choice)
4.9/5 (77)
(77) To facilitate the working paper preparation process, defaults can be established to automatically insert client name, period covered, and preparer. This can best be done using
(Multiple Choice)
4.8/5 (79)
(79) A common comparison occurs when the auditor calculates the expected balance and compares it with the actual balance. The auditor's expected account balance may be determined by
(Multiple Choice)
4.8/5 (90)
(90) The audit of Simcoe Transports Inc. was completed three months ago, so the PA firm proceeded to the file archive stage in accordance with Canadian Audit Standards. If the audit firm receives additional information related to the audit but the information does not affect the audit conclusions, the information should be
(Multiple Choice)
4.8/5 (61)
(61) Below are 12 audit procedures. Classify each procedure according to the following types of audit evidence: 1) inspection, 2) external confirmation, 3) recalculation, 4) observation, 5) inquiry of the client, 6) reperformance, and 7) analytical procedure.
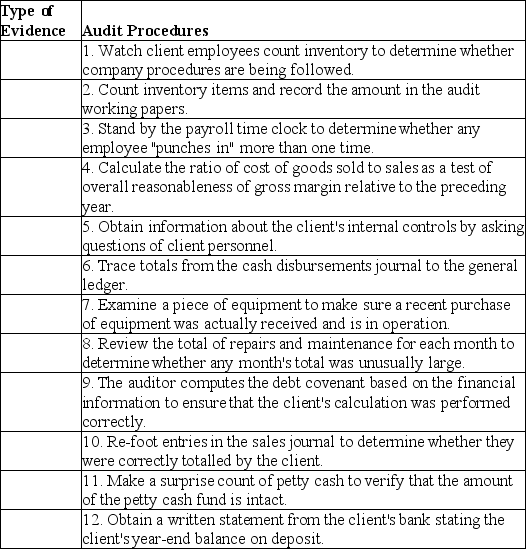
(Essay)
4.9/5 (77)
(77) During final review of working papers and financial statements, possible oversights in the audit can be identified by
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)