
Exam 9: Audit Evidence

arrow
  • Select Tags
search iconSearch Question
  • Select Tags

If most companies in the industry use FIFO inventory valuation and straight-line depreciation, and the audit client uses LIFO and double-declining balance, comparisons of client and industry data

Free
(Multiple Choice)
4.7/5
(86)
Correct Answer:
Verified

D

The working papers prepared during the engagement are the property of the

Free
(Multiple Choice)
4.9/5
(84)
Correct Answer:
Verified

B

For each of the following audit procedures, state and describe the type of audit evidence, state the audit assertion that it applies to, and describe the reliability of the evidence (with reasons). A) Watch staff scan products and enter cash received. B) Reconcile daily cash drawer receipts (cash, debit card sales, credit card sales) with daily sales for one week. C) Calculate daily gross profit and gross profit by product line. D) Account for a sequence of sales documents.

Free
(Essay)
4.8/5
(83)
Correct Answer:
Verified

A)Watch staff scan products and enter cash received.
 Type of audit evidence  (with reason)  Applicable audit  assertion  Reliability of evidence  (higedium, or low,  with reason)  Observation, as the auditor is  Medium. Although it is being  using a sense (vision) to  Occurrence  performed by the auditor, this  assess the activity of  is point-in-time test and is  limited to the actual duration  of the observation.  recording sales \begin{array} { | l | l | l | } \hline \begin{array} { l } \text { Type of audit evidence } \\\text { (with reason) }\end{array} & \begin{array} { l } \text { Applicable audit } \\\text { assertion }\end{array} & \begin{array} { l } \text { Reliability of evidence } \\\text { (higedium, or low, } \\\text { with reason) }\end{array} \\\hline \text { Observation, as the auditor is } & & \text { Medium. Although it is being } \\\text { using a sense (vision) to } & \text { Occurrence } & \text { performed by the auditor, this } \\\text { assess the activity of } & & \begin{array} { l } \text { is point-in-time test and is } \\\text { limited to the actual duration } \\\text { of the observation. }\end{array} \\\hline \text { recording sales } & & \\\hline\end{array}
B)Reconcile daily cash drawer receipts (cash, debit card sales, credit card sales)with daily sales for one week.
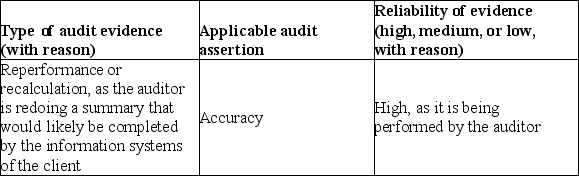
 A)Watch staff scan products and enter cash received.   \begin{array} { | l | l | l | }  \hline \begin{array} { l }  \text { Type of audit evidence } \\ \text { (with reason) } \end{array} & \begin{array} { l }  \text { Applicable audit } \\ \text { assertion } \end{array} & \begin{array} { l }  \text { Reliability of evidence } \\ \text { (higedium, or low, } \\ \text { with reason) } \end{array} \\ \hline \text { Observation, as the auditor is } & & \text { Medium. Although it is being } \\ \text { using a sense (vision) to } & \text { Occurrence } & \text { performed by the auditor, this } \\ \text { assess the activity of } & & \begin{array} { l }  \text { is point-in-time test and is } \\ \text { limited to the actual duration } \\ \text { of the observation. } \end{array} \\ \hline \text { recording sales } & & \\ \hline \end{array}   B)Reconcile daily cash drawer receipts (cash, debit card sales, credit card sales)with daily sales for one week.     C)Calculate daily gross profit and gross profit by product line.     D)Account for a sequence of sales documents.   \begin{array} { l | l | l }  \begin{array} { l }  \text { Type of audit evidence } \\ \text { (with reason) } \end{array} & \begin{array} { l }  \text { Applicable audit } \\ \text { assertion } \end{array} & \begin{array} { l }  \text { Reliability of evidence } \\ \text { (high, medium, or low, } \\ \text { with reason) } \end{array} \\ \hline \text { Inspection, as the auditor is } & & \\ \text { examining client } & & \text { High, as it is being } \\ \text { documentation for the } \\ \text { continuity, or } & & \text { performed by the auditor } \\ \text { reperformance, as the } & \text { Completeness } & \text { and is substantiated by client } \\ \text { auditor is re-doing and } & & \text { documentation. } \\ \text { checking the issuance of an } & & \\ \text { ascending sequence for } & & \\ \text { sales documents. } & & \\ \hline \end{array}
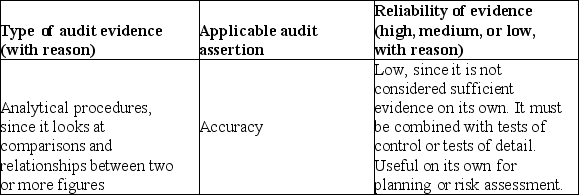
C)Calculate daily gross profit and gross profit by product line.
 A)Watch staff scan products and enter cash received.   \begin{array} { | l | l | l | }  \hline \begin{array} { l }  \text { Type of audit evidence } \\ \text { (with reason) } \end{array} & \begin{array} { l }  \text { Applicable audit } \\ \text { assertion } \end{array} & \begin{array} { l }  \text { Reliability of evidence } \\ \text { (higedium, or low, } \\ \text { with reason) } \end{array} \\ \hline \text { Observation, as the auditor is } & & \text { Medium. Although it is being } \\ \text { using a sense (vision) to } & \text { Occurrence } & \text { performed by the auditor, this } \\ \text { assess the activity of } & & \begin{array} { l }  \text { is point-in-time test and is } \\ \text { limited to the actual duration } \\ \text { of the observation. } \end{array} \\ \hline \text { recording sales } & & \\ \hline \end{array}   B)Reconcile daily cash drawer receipts (cash, debit card sales, credit card sales)with daily sales for one week.     C)Calculate daily gross profit and gross profit by product line.     D)Account for a sequence of sales documents.   \begin{array} { l | l | l }  \begin{array} { l }  \text { Type of audit evidence } \\ \text { (with reason) } \end{array} & \begin{array} { l }  \text { Applicable audit } \\ \text { assertion } \end{array} & \begin{array} { l }  \text { Reliability of evidence } \\ \text { (high, medium, or low, } \\ \text { with reason) } \end{array} \\ \hline \text { Inspection, as the auditor is } & & \\ \text { examining client } & & \text { High, as it is being } \\ \text { documentation for the } \\ \text { continuity, or } & & \text { performed by the auditor } \\ \text { reperformance, as the } & \text { Completeness } & \text { and is substantiated by client } \\ \text { auditor is re-doing and } & & \text { documentation. } \\ \text { checking the issuance of an } & & \\ \text { ascending sequence for } & & \\ \text { sales documents. } & & \\ \hline \end{array}
D)Account for a sequence of sales documents.
 Type of audit evidence  (with reason)  Applicable audit  assertion  Reliability of evidence  (high, medium, or low,  with reason)  Inspection, as the auditor is  examining client  High, as it is being  documentation for the  continuity, or  performed by the auditor  reperformance, as the  Completeness  and is substantiated by client  auditor is re-doing and  documentation.  checking the issuance of an  ascending sequence for  sales documents. \begin{array} { l | l | l } \begin{array} { l } \text { Type of audit evidence } \\\text { (with reason) }\end{array} & \begin{array} { l } \text { Applicable audit } \\\text { assertion }\end{array} & \begin{array} { l } \text { Reliability of evidence } \\\text { (high, medium, or low, } \\\text { with reason) }\end{array} \\\hline \text { Inspection, as the auditor is } & & \\\text { examining client } & & \text { High, as it is being } \\\text { documentation for the } \\\text { continuity, or } & & \text { performed by the auditor } \\\text { reperformance, as the } & \text { Completeness } & \text { and is substantiated by client } \\\text { auditor is re-doing and } & & \text { documentation. } \\\text { checking the issuance of an } & & \\\text { ascending sequence for } & & \\\text { sales documents. } & & \\\hline\end{array}

Mary is entering a fictitious transaction in the sales data entry system to see if the system will reject the order for a client that is already exceeding its credit limit. Mary is using

(Multiple Choice)
4.8/5
(82)

An example of an internal document is

(Multiple Choice)
4.9/5
(91)

To facilitate the working paper preparation process, defaults can be established to automatically insert client name, period covered, and preparer. This can best be done using

(Multiple Choice)
4.7/5
(85)

Last year, the client's internal controls were weak. This year, the internal controls are stronger. This means that information recorded on internal documentation is

(Multiple Choice)
4.9/5
(76)

An example of a document that the auditor receives from the client, but which was prepared by someone outside the client's organization, is a(n)

(Multiple Choice)
4.9/5
(74)

Which of the following types of evidence is most appropriate in the audit of fixed assets?

(Multiple Choice)
4.9/5
(87)

Gina is performing the audit of the payables section of Reno Inc. She wants to confirm the payables from an independent source. Which of the following actions would achieve this?

(Multiple Choice)
4.8/5
(87)

When an auditor calculates the gross margin as a percent of sales and compares it with previous periods, this type of evidence is called

(Multiple Choice)
4.9/5
(67)

Evidence is generally considered appropriate when

(Multiple Choice)
4.7/5
(83)

Which one of the following forms of evidence would be least reliable?

(Multiple Choice)
4.8/5
(82)

An important benefit of industry comparisons is as

(Multiple Choice)
4.8/5
(75)

CAS 330, the auditor's response to assessed risks, explains that the auditor needs to link completed audit work to the assessed risks at the assertion level and

(Multiple Choice)
4.9/5
(90)

Inquiry is a valuable technique during the planning phase of the audit because it

(Multiple Choice)
4.9/5
(75)

The decision of how many items to test must be made by the auditor for each audit procedure. The sample size for any given procedure

(Multiple Choice)
5.0/5
(70)

Reperformance is often conducted using computer-assisted audit techniques. The most effective use of generalized audit software for reperformance would be to

(Multiple Choice)
4.7/5
(82)

Which of the following characteristics of samples would make the sample more sufficient?

(Multiple Choice)
4.9/5
(78)

Observation is an important audit technique where the auditor can use sight, hearing, touch, and smell. Observation needs to be used together with other audit techniques because

(Multiple Choice)
4.9/5
(96)
Showing 1 - 20 of 80
close modal

Filters

  • Essay(0)
  • Multiple Choice(0)
  • Short Answer(0)
  • True False(0)
  • Matching(0)