



 Chat with AI
Exam 14: Audit sampling

Exam 1: Demand for audit and assurance services74 Questions
Exam 2: Auditors’ legal environment89 Questions
Exam 3: Audit quality and ethics101 Questions
Exam 4: Audit responsibilities and objectives113 Questions
Exam 5: Audit evidence118 Questions
Exam 6: Audit planning and documentation105 Questions
Exam7: Materiality and risk105 Questions
Exam 8: Internal control and control risk119 Questions
Exam 9: Fraud auditing75 Questions
Exam 10: The impact of information technology on the audit process104 Questions
Exam 11: Overall audit plan and audit program105 Questions
Exam 12: Audit of the sales and collection cycle: Tests of controls and substantive tests of transactions120 Questions
Exam 13: Completing tests in the sales and collection cycle: Accounts receivable109 Questions
Exam 14: Audit sampling146 Questions
Exam 15: Audit of transaction cycles and financial statement balances I138 Questions
Exam 16: Audit of transaction cycles and financial statement balances II137 Questions
Exam 17: Completing the audit100 Questions
Exam 18: Audit reporting85 Questions
Exam 19: Other auditing and assurance engagements102 Questions
Select questions type


A frequency distribution of the results of all possible samples of a specified size that could be obtained from a population containing some specific parameter is the:
(Multiple Choice)
4.9/5  (84)
(84) As a result of tests of controls, an auditor assessed control risk too low and decreased substantive testing.This occurred because the true deviation rate in the population was:
(Multiple Choice)
4.8/5 (77)
(77) Which one of the following statements regarding monetary-unit sampling (MUS)is NOT true?
(Multiple Choice)
4.9/5 (83)
(83) For tests of details of balances, a lower frequency of misstatements can result in smaller sample sizes.
(True/False)
4.9/5 (71)
(71) The auditor must deal with layers of the computed upper deviation rate (CUDR)from the attributes table because there are different error assumptions for each error.Assume a sample of 100 had found 1 error, and the computed upper deviation rate is shown in the following table:
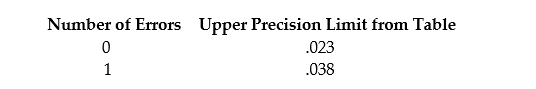 What is the CUDR layer for the first mistake?
 (Multiple Choice)
4.8/5 (81)
(81) When an auditor performs tests of details of balances, the concern is determining:
(Multiple Choice)
4.8/5 (76)
(76) How are tests of controls affected when the auditor decides to assess control risk at the maximum level?
(Multiple Choice)
4.8/5 (81)
(81) In monetary-unit sampling, the values of the estimated likely maximum misstatements are referred to as the:
(Multiple Choice)
4.9/5 (61)
(61) Sampling error and non-sampling error can each cause a sample result to be non-representative.
(True/False)
4.7/5 (78)
(78) Explain the rule used in monetary-unit sampling to decide whether the population is acceptable.
(Essay)
4.9/5 (83)
(83) Although systematic sample selection is easy to use, its primary disadvantage is that it is not a probabilistic sampling method.
(True/False)
4.8/5 (70)
(70) A sample of all items in a population will have a zero sampling risk.
(True/False)
4.9/5 (75)
(75) Acceptable risk of assessing control risk too low (ARO)and allowable risk of incorrect acceptance (ARIA)are inversely related; that is, a decrease in ARO is accompanied by an increase in ARIA.
(True/False)
4.7/5 (80)
(80) Non-sampling errors occur when audit tests do NOT uncover existing exceptions in the:
(Multiple Choice)
4.9/5 (85)
(85) In audit sampling, an advance estimate of the deviation rate is necessary to plan the appropriate sample size.The relationship of estimated population deviation rate (EPDR)to sample size is:
(Multiple Choice)
4.9/5 (87)
(87) When monetary-unit sampling is used to audit accounts receivable, a customer's account with a small year-end balance has the same chance of being included in the sample as a customer's account with a large year-end balance.
(True/False)
4.8/5 (83)
(83) Which one of the following BEST illustrates the concept of sampling risk?
(Multiple Choice)
4.9/5 (96)
(96) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)