



 Chat with AI
Exam 13: Auditing Debt Obligations and Stockholders Equity Transactions

Exam 1: Auditing: Integral to the Economy100 Questions
Exam 2: The Auditors Responsibilities Regarding Fraud and Mechanisms to Address Fraud: Regulation and Corporate Governance120 Questions
Exam 3: Internal Control Over Financial Reporting: Responsibilities of Management and the External Auditors104 Questions
Exam 4: Professional Liability, Auditor Judgment Frameworks, and Professional Responsibilities88 Questions
Exam 5: Professional Auditing Standards and the Audit Opinion Formulation Process104 Questions
Exam 6: A Framework for Audit Evidence108 Questions
Exam 7: Planning the Audit: Identifying and Responding to the Risks of Material Misstatement92 Questions
Exam 8: Specialized Audit Tools: Sampling and Generalized Audit Software114 Questions
Exam 9: Auditing the Revenue Cycle116 Questions
Exam 10: Auditing Cash and Marketable Securities101 Questions
Exam 11: Auditing Inventory, Goods and Services, and Accounts Payable: the Acquisition and Payment Cycle102 Questions
Exam 12: Auditing Long-Lived Assets: Acquisition, Use, Impairment, and Disposal97 Questions
Exam 13: Auditing Debt Obligations and Stockholders Equity Transactions120 Questions
Exam 14: Activities Required in Completing a Quality Audit184 Questions
Exam 15: Audit Reports on Financial Statements109 Questions
Exam 16: Advanced Topics Concerning Complex Auditing Judgments132 Questions
Exam 17: Other Services Provided by Audit Firms107 Questions
Select questions type


Normally, an auditor can gain an understanding of internal controls by means of a walkthrough of the process, inquiry, observation, and review of the client's documentation.
(True/False)
4.8/5  (81)
(81) When auditing debt obligations, which of the following is the primary substantive analytical procedure?
(Multiple Choice)
4.9/5 (77)
(77) Which of the following will an auditor not perform when looking for debt reductions?
(Multiple Choice)
4.8/5 (82)
(82) Which of the following is not a relevant account when auditing stockholders' equity?
(Multiple Choice)
4.8/5 (83)
(83) The auditor is primarily concerned with overstatement when auditing bonds.
(True/False)
5.0/5 (76)
(76) As part of brainstorming activities, the auditor might identify possible fraudulent transactions related to stockholders' equity accounts that are the result of charging expenses directly to retained earnings rather than to the appropriate expense accounts.
(True/False)
4.7/5 (72)
(72) Bonds are issued to finance major expansions or to refinance existing debt.
(True/False)
4.8/5 (80)
(80) Which of the following is not a common transaction affecting stockholders' equity?
(Multiple Choice)
4.8/5 (86)
(86) Using substantive procedures to test debt obligations is most appropriate because there are a relatively large number of transactions involving immaterial dollar amounts.
(True/False)
4.9/5 (88)
(88) A CPA firm is engaged in the examination of the financial statements of Garrison Corporation for the year ended December 31, 2014. Garrison Corporation's financial statements and records have never been audited by a CPA. The stockholders' equity section of Garrison Corporation's balance sheet at December 31, 2014, follows:
Stockholders' Equity:
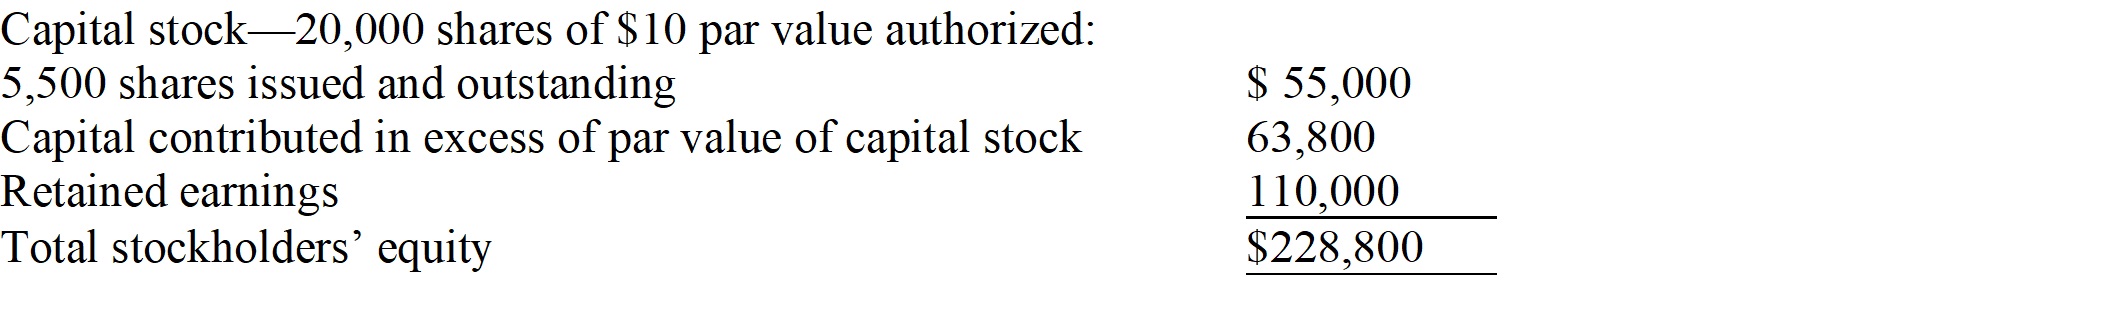 REQUIRED:
Prepare the detailed audit program for the examination of the three accounts composing the stockholders’ equity section of Garrison Corporation’s balance sheet. (Do not include in the audit program the verification of the results of the current-year operations.)
REQUIRED:
Prepare the detailed audit program for the examination of the three accounts composing the stockholders’ equity section of Garrison Corporation’s balance sheet. (Do not include in the audit program the verification of the results of the current-year operations.)
(Essay)
4.9/5 (79)
(79) Auditing standards require the auditor to identify and assess the risks of material misstatement due to fraud at the financial statement level only.
(True/False)
4.9/5 (69)
(69) An auditor determines that there is an inherent risk that dividends may be recorded and paid before being declared. This determination is most likely tied to which of the following management assertions?
(Multiple Choice)
4.8/5 (86)
(86) An auditor determines that there is an inherent risk that stock options exercised or expired remain on the organization's books. This determination is most likely tied to which of the following management assertions?
(Multiple Choice)
4.7/5 (76)
(76) Which of the following is not typically included in the audit of debt obligations?
(Multiple Choice)
4.8/5 (81)
(81) Which of the following will an auditor not perform when looking for additions to debt?
(Multiple Choice)
4.7/5 (68)
(68) If interest expense recorded by the client is significantly lower than the auditor's expectation, it may mean that interest payments have not been properly recorded, possibly having been charged to principal.
(True/False)
4.9/5 (68)
(68) Which of the following is not important documentation for substantive procedures for capital stock and equity transactions?
(Multiple Choice)
4.7/5 (87)
(87) Which of the following is not a common debt covenant restriction?
(Multiple Choice)
4.9/5 (83)
(83) When auditing the gains or losses on refinancing debt, the auditor primarily focuses on which assertion?
(Multiple Choice)
4.9/5 (71)
(71) If preliminary analytical procedures do not identify any unexpected relationships related to debt obligations, the auditor would conclude that there is not a heightened risk of material misstatements in these accounts.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)