



 Chat with AI
Exam 15: Leases

Exam 1: Environment and Theoretical Structure of Financial Accounting181 Questions
Exam 2: Review of the Accounting Process 139 Questions
Exam 3: The Balance Sheet and Financial Disclosures168 Questions
Exam 4: The Income Statement, Comprehensive Income, and the Statement of Cash Flows178 Questions
Exam 5: Revenue Recognition316 Questions
Exam 6: Time Value of Money Concepts126 Questions
Exam 7: Cash and Receivables187 Questions
Exam 8: Inventories: Measurement182 Questions
Exam 9: Inventories: Additional Issues153 Questions
Exam 10: Property, Plant, and Equipment and Intangible Assets: Acquisition149 Questions
Exam 11: Property, Plant, and Equipment and Intangible Assets: Utilization and Disposition223 Questions
Exam 12: Investments183 Questions
Exam 13: Current Liabilities and Contingencies155 Questions
Exam 14: Bonds and Long-Term Notes256 Questions
Exam 15: Leases262 Questions
Exam 16: Accounting for Income Taxes176 Questions
Exam 17: Pensions and Other Postretirement Benefits246 Questions
Exam 18: Shareholders Equity179 Questions
Exam 19: Share-Based Compensation and Earnings Per Share231 Questions
Exam 20: Accounting Changes and Error Corrections152 Questions
Exam 21: The Statement of Cash Flows Revisited192 Questions
Select questions type


On January 1, 2018, Osiris Inc. leased manufacturing equipment from Giza Leasing for a four-year period ending December 31, 2018, at which time possession of the leased asset will revert back to Giza. The equipment cost Giza $206,092 and has an expected economic life of five years. Giza expects the residual value at December 31, 2018, to be $25,000. Negotiations led to Osiris guaranteeing a $35,000 residual value.
Equal payments under the lease are $50,000 and are due on December 31 of each year with the first payment being made on December 31, 2018. Osiris is aware that Giza used a 5% interest rate when calculating lease payments.
Required:
Round your answers to the nearest whole dollar amounts.
1. Prepare the appropriate journal entry for Osiris on January 1, 2018, to record the lease.
2. Prepare all appropriate journal entries for Osiris on December 31, 2018, related to the lease.
(Essay)
5.0/5  (95)
(95) At the beginning of a lease agreement, a lessee's debt to equity ratio and rate of return on assets are both affected regardless of whether the lease is classified as a finance lease or as an operating lease.
(True/False)
4.9/5 (82)
(82) A noncancelable lease contains an option to purchase a leased asset at a price that is sufficiently lower than the asset's expected fair value so that the exercise of the option appears reasonably certain. The fair value of the asset exceeds the lessor's cost of the asset. Therefore, the lease will be accounted for by the lessor as a(n):
(Multiple Choice)
4.8/5 (73)
(73) If the lessee expects to obtain title to leased property due to a purchase option that is reasonably certain to be exercised or the passage of title at the end of the lease term:
(Multiple Choice)
4.8/5 (79)
(79) In connection with a lease of more than 12 months, the lessee always will record each of the following except:
(Multiple Choice)
4.9/5 (75)
(75) In a financing lease, "front loading" of lease expense and lease revenue occurs. What does this mean, and how is it avoided in an operating lease?
(Essay)
4.9/5 (73)
(73) On January 1, 2018, Green Co. recorded a right-of-use asset of $270,360 in an operating lease. The lease calls for ten annual payments of $40,000 at the beginning of each year. The interest rate charged by the lessor was 10%. The balance in the right-of-use asset at December 31, 2018, will be:
(Multiple Choice)
4.8/5 (71)
(71) Karla Salons leased equipment from Smith Co. on July 1, 2018, in a finance lease. The present value of the lease payments discounted at 10% was $80,000. Ten annual lease payments of $12,000 are due each year beginning July 1, 2018. Smith Co. had constructed the equipment recently for $66,000, and its retail fair value was $80,000.
-What amount of interest revenue from the lease should Smith Co. report in its December 31, 2018, income statement?
(Multiple Choice)
4.9/5 (72)
(72) 1) In a lease transaction, what are initial direct costs?
2) How does the lessor account for initial direct costs in an operating lease, a sales-type lease with selling profit, and a sales-type lease with no selling profit?
(Essay)
5.0/5 (75)
(75) I. Lasch Co. recorded a right-of-use asset of $200,000 in a 10-year operating lease. Payments of $32,550 are made annually at the end of each year. The interest rate charged by the lessor was 10%. The balance in the right-of-use asset after the first year will be:
(Multiple Choice)
4.7/5 (76)
(76) On December 31, 2018, B Corp. sold a machine to Royal and simultaneously leased it back for one year. Pertinent information at this date follows: 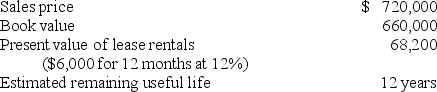 In B's December 31, 2018, balance sheet, the recognized gain from the sale of this machine should be:
 (Multiple Choice)
4.9/5 (94)
(94) On January 1, 2018, Robertson Construction leased several items of equipment under a two-year operating lease agreement from Jamison Leasing, which routinely finances equipment for other firms at an annual interest rate of 4%. The contract calls for four rent payments of $40,000 each, payable semiannually on June 30 and December 31 each year. The equipment was acquired by Jamison Leasing at a cost of $360,000 and was expected to have a useful life of five years with no residual value. Both firms record amortization and depreciation semi-annually.
-Required:
Prepare the appropriate journal entries for the lessee from the beginning of the lease through the end of 2018. Round your answers to the nearest whole dollar amounts.
(Essay)
4.8/5 (79)
(79) Refer to the following lease amortization schedule. The five payments are made annually starting with the beginning of the lease. A $2,000 purchase option is reasonably certain to be exercised at the end of the five-year lease. The asset has an expected economic life of eight years.
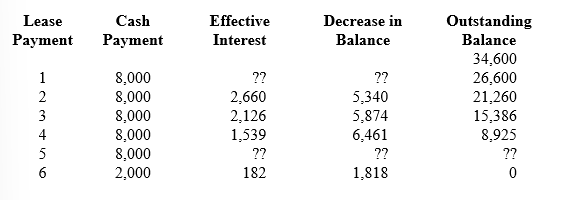 -What would be the amount of interest expense recorded with payment 5?
 (Multiple Choice)
4.8/5 (72)
(72) The costs that (a) are associated directly with consummating a lease, (b) are essential to acquire the lease, and (c) would not have been incurred had the lease agreement not occurred, are referred to as initial direct costs. Initial direct costs incurred by the lessor are deferred and expensed over the lease term:
(Multiple Choice)
4.9/5 (69)
(69) Refer to the following lease amortization schedule. The 10 payments are made annually starting with the beginning of the lease. Title does not transfer to the lessee and there is no purchase option or guaranteed residual value. The asset has an expected economic life of 12 years. The lease is noncancelable.
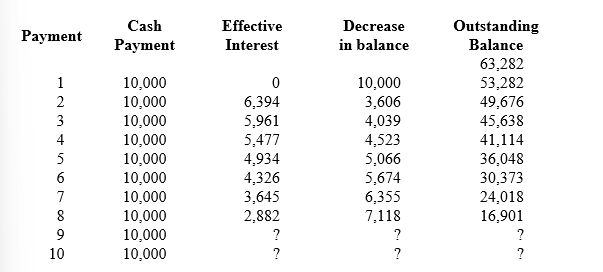 -Like other assets, the cost of a leasehold improvement is allocated as depreciation expense over its useful life to the lessee, which will be:
 (Multiple Choice)
4.8/5 (90)
(90) On January 1, 2018, Patagonia Leasing leased equipment to Pebble Services under a finance/sales-type lease designed to earn Patagonia a 12% rate of return for providing long-term financing. The lease agreement specified:
a. Ten annual payments of $110,000 beginning January 1, 2018, the beginning of the lease and each December 31 thereafter through 2026.
b. The estimated useful life of the leased equipment is 10 years with no residual value. Its cost to Patagonia was $632,824.
c. The lease qualifies as a finance lease/sales-type lease.
d. A 10-year service agreement with Mechanics International was negotiated to provide maintenance of the equipment as required. Payments of $10,000 per year are specified, beginning January 1, 2018. Patagonia was to pay this cost as incurred, but lease payments reflect this expenditure.
e. A partial amortization schedule, appropriate for both the lessee and lessor, follows:
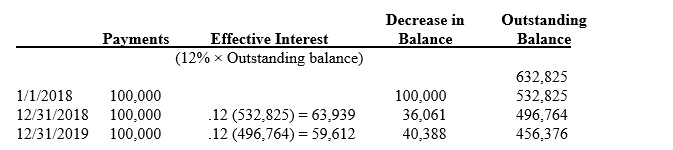 Required:
Round your answers to the nearest whole dollar amounts.
Prepare the appropriate journal entries for both the lessee and lessor related to the lease on:
1. January 1, 2018.
2. December 31, 2018.
Required:
Round your answers to the nearest whole dollar amounts.
Prepare the appropriate journal entries for both the lessee and lessor related to the lease on:
1. January 1, 2018.
2. December 31, 2018. (Essay)
4.8/5 (76)
(76) Big Bucks leased equipment to Shannon Company on July 1, 2018. The lease payments were calculated to provide the lessor a 10% return. Ten annual lease payments of $36,000 are due each July 1, beginning July 1, 2018.
Required
1. Prepare the journal entries to record the lease by Shannon at July 1, 2018, and at December 31, 2018, the end of the reporting period. Consider this to be a finance lease. Round your answers to the nearest whole dollar amounts.
2. Prepare the journal entries to record the lease by Shannon at July 1, 2018, and at December 31, 2018, the end of the reporting period. Consider this to be an operating lease. Round your answers to the nearest whole dollar amounts.
(Essay)
4.8/5 (85)
(85) By the lessee, a lessee-guaranteed residual value at the beginning of a finance lease should be:
(Multiple Choice)
4.9/5 (77)
(77) Which of the following statements regarding a lessee-guaranteed residual value is true?
(Multiple Choice)
4.9/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)