



 Chat with AI
Exam 1: Certified Credit Research Analyst

Exam 1: Certified Credit Research Analyst83 Questions
Select questions type


Loss assets should be written off. If loss assets are permitted to remain in the books for any reason, ______percent of the outstanding should be provided for.
(Multiple Choice)
4.8/5  (75)
(75) Satish Dhawan, a veteran fixed income trader is conducting interviews for the post of a junior fixed income trader. He interviewed four candidates Adam, Balkrishnan, Catherine and Deepak and following are the answers to his questions. Question 1: Tell something about Option Adjusted Spread Adam: OAS is applicable only to bond which do not have any options attached to it. It is for the plain bonds. Balkishna: In bonds with embedded options, AS reflects not only the credit risk but also reflects prepayment risk over and above the benchmark. Catherine: Sincespreads are calculated to know the level of credit risk in the bound, OAS is difference between in the Z spread and price of a call option for a callable bond. Deepark: For callable bond OAS will be lower than Z Spread. Question 2 : This is a spread that must be added to the benchmark zero rate curve in a parallel shift so that the sum of the risky bond's discounted cash flows equals its current market price. Which Spread I am talking about? Adam: Z Spread Balkrishna: Nominal Spread Catherine: Option Adjusted Spread Deepark: Asset Swap Spread Question 3 : What do you know about Interpolated spread and yield spread? Adam: Yield spread is the difference between the YTM of a risky bond and the YTM of an on-the-run treasury benchmark bond whose maturity is closest, but not identical to that of risky bond. Interpolated spread is the spread between the YTM of risky bond and the YTM of same maturity treasury benchmark, which is interpolated from the two nearest on-the-run treasury securities. Balkrishna: Interpolated spread is preferred to yield spread because the latter has the maturity mismatch, which leads to error if the yield curve is not flat and the benchmark security changes over time, leading to inconsistency. Catherine: Interpolated spread takes account the shape of the benchmark yield curve and therefore better than yield spread. Deepak: Both Interpolated Spread and Yield Spread rely on YTM which suffers from drawbacks and inconsistencies such as the assumption of flat yield curve and reinvestment at YTM itself. Then Satish gave following information related to the benchmark YTMs: 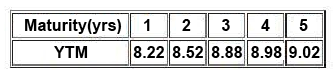 There is an 8.75% risky bond with a maturity of 2.75% year(s). Its current price is INR102.31, which corresponds to YTM of 8.52%. Compute Yield Spread from the information provided in the vignette:
 (Multiple Choice)
4.9/5 (68)
(68) During FY13, Small Bazar, a leading retail company has sold three of its prime properties for a sum of USD 24 Million. The same had a carrying value of USD 30 Million. Analyst had considered the same as operating income and considered it to be part of operating expenses. However, she realized her mistake and recorded the loss as non-operating loss. Which of the following ratio will not change despite the correction? A) EBITDA Margins B) Interest Coverage C) PAT Margins D) Gross Profit Margin
(Multiple Choice)
4.8/5 (75)
(75) Which of the following statements concerning having a CEO serve as chairman of the board is most accurate? Having a CEO also serve as chairman is considered:
(Multiple Choice)
4.9/5 (87)
(87) In a weakening economy, which of the following is least accurate?
(Multiple Choice)
4.8/5 (88)
(88) Project 1: Company X has a sugar mill at Philadelphia and is replicating same at Toronto. Project 2: Company Y has a sugar mill at Philadelphia and is increasing capacity from 100000 MT to 140000 MT per annum. What type of projects are Project 1 and Project 2?
(Multiple Choice)
4.9/5 (79)
(79) Scott is a credit analyst with one of the credit rating agencies in India. He was looking in Oil and Gas Industry companies and has presented brief financials for following 4 entities: 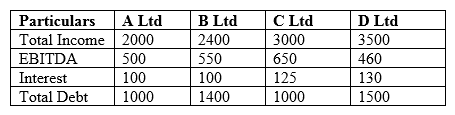 Giving equal weightage to all three ratios, determine which of the above entities should be rated highest on a relative scale.
 (Multiple Choice)
4.8/5 (84)
(84) Awesome Mobile Ltd is a leading mobile seller who manufactures mobile phone under own brand Awesome. Which of the following is the biggest business risk for Awesome?
(Multiple Choice)
4.9/5 (85)
(85) In an industry there are only 20 firms and each of them has equal share. Compute Herfindahl Hirschman Index and state the level of concentration in the industry.
(Multiple Choice)
4.9/5 (67)
(67) Satish Dhawan, a veteran fixed income trader is conducting interviews for the post of a junior fixed income trader. He interviewed four candidates Adam, Balkrishnan, Catherine and Deepak and following are the answers to his questions. Question 1: Tell something about Option Adjusted Spread Adam: OAS is applicable only to bond which do not have any options attached to it. It is for the plain bonds. Balkishna: In bonds with embedded options, AS reflects not only the credit risk but also reflects prepayment risk over and above the benchmark. Catherine: Sincespreads are calculated to know the level of credit risk in the bound, OAS is difference between in the Z spread and price of a call option for a callable bond. Deepark: For callable bond OAS will be lower than Z Spread. Question 2 : This is a spread that must be added to the benchmark zero rate curve in a parallel shift so that the sum of the risky bond's discounted cash flows equals its current market price. Which Spread I am talking about? Adam: Z Spread Balkrishna: Nominal Spread Catherine: Option Adjusted Spread Deepark: Asset Swap Spread Question 3 : What do you know about Interpolated spread and yield spread? Adam: Yield spread is the difference between the YTM of a risky bond and the YTM of an on-the-run treasury benchmark bond whose maturity is closest, but not identical to that of risky bond. Interpolated spread is the spread between the YTM of risky bond and the YTM of same maturity treasury benchmark, which is interpolated from the two nearest on-the-run treasury securities. Balkrishna: Interpolated spread is preferred to yield spread because the latter has the maturity mismatch, which leads to error if the yield curve is not flat and the benchmark security changes over time, leading to inconsistency. Catherine: Interpolated spread takes account the shape of the benchmark yield curve and therefore better than yield spread. Deepak: Both Interpolated Spread and Yield Spread rely on YTM which suffers from drawbacks and inconsistencies such as the assumption of flat yield curve and reinvestment at YTM itself. Then Satish gave following information related to the benchmark YTMs: 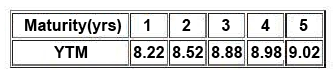 There is a 10.25% risky bond with a maturity of 4.75 year(s). Its current price is INR105.31, which corresponds to YTM of 9.22%. Compute Interpolated Spread from the information provided in the vignette:
 (Multiple Choice)
4.8/5 (85)
(85) Two economies HardLand and SincereLand have provided following information with respect to their economies in USD Billion: 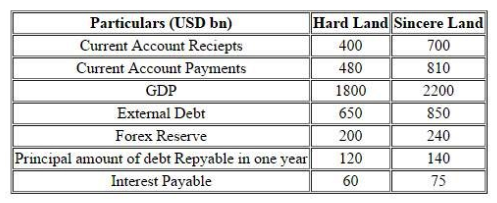 Based on the above information which entity is better in terms of current account deficit %?
 (Multiple Choice)
4.8/5 (80)
(80) Satish Dhawan, a veteran fixed income trader is conducting interviews for the post of a junior fixed income trader. He interviewed four candidates Adam, Balkrishnan, Catherine and Deepak and following are the answers to his questions. Question 1: Tell something about Option Adjusted Spread Adam: OAS is applicable only to bond which do not have any options attached to it. It is for the plain bonds. Balkishna: In bonds with embedded options, AS reflects not only the credit risk but also reflects prepayment risk over and above the benchmark. Catherine: Sincespreads are calculated to know the level of credit risk in the bound, OAS is difference between in the Z spread and price of a call option for a callable bond. Deepark: For callable bond OAS will be lower than Z Spread. Question 2 : This is a spread that must be added to the benchmark zero rate curve in a parallel shift so that the sum of the risky bond's discounted cash flows equals its current market price. Which Spread I am talking about? Adam: Z Spread Balkrishna: Nominal Spread Catherine: Option Adjusted Spread Deepark: Asset Swap Spread Question 3 : What do you know about Interpolated spread and yield spread? Adam: Yield spread is the difference between the YTM of a risky bond and the YTM of an on-the-run treasury benchmark bond whose maturity is closest, but not identical to that of risky bond. Interpolated spread is the spread between the YTM of risky bond and the YTM of same maturity treasury benchmark, which is interpolated from the two nearest on-the-run treasury securities. Balkrishna: Interpolated spread is preferred to yield spread because the latter has the maturity mismatch, which leads to error if the yield curve is not flat and the benchmark security changes over time, leading to inconsistency. Catherine: Interpolated spread takes account the shape of the benchmark yield curve and therefore better than yield spread. Deepak: Both Interpolated Spread and Yield Spread rely on YTM which suffers from drawbacks and inconsistencies such as the assumption of flat yield curve and reinvestment at YTM itself. Then Satish gave following information related to the benchmark YTMs: 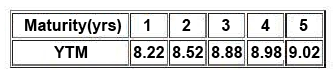 An investor decides to invest in the bond futures and has an outlook that the term structure curve would steepen. What should be his trading strategy?
 (Multiple Choice)
4.7/5 (80)
(80) The following information pertains to bonds: 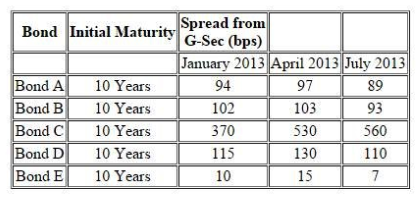 Further following information is available about a particular bond 'Bond F' There is a 10.25% risky bond with a maturity of 2.25% year(s) its current price is INR105.31, which corresponds to YTM of 9.22%. The following are the benchmark YTMs.
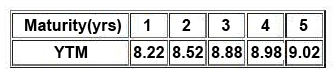 Compute interpolated spread for Bond F based on the information provided in the vignette:
Further following information is available about a particular bond 'Bond F' There is a 10.25% risky bond with a maturity of 2.25% year(s) its current price is INR105.31, which corresponds to YTM of 9.22%. The following are the benchmark YTMs. Compute interpolated spread for Bond F based on the information provided in the vignette: (Multiple Choice)
4.9/5 (82)
(82) An increase in the salaries of the bank employees due to new bank employee pay commission implemented by the Central Government will lead to deterioration of which of the following ratios: A: Cost to Income Ratio B: Net Interest Margin C: Core Spread
(Multiple Choice)
4.8/5 (93)
(93) Following is information related banks: Auckland Ltd is a public sector bank operating with about 120 branches across India. The bank has been in business since 1971 and has about 40% branches in rural areas and about 75% of all branches are in Western India. On the basis of the size, Auckland Ltd will be ranked at number 31 amongst 40 banks in India. Although top management has appointment period of 5 years, generally they retire on ach sieving age of 60 years with an average tenure of only 2 years at the top job. Profit and Loss Account 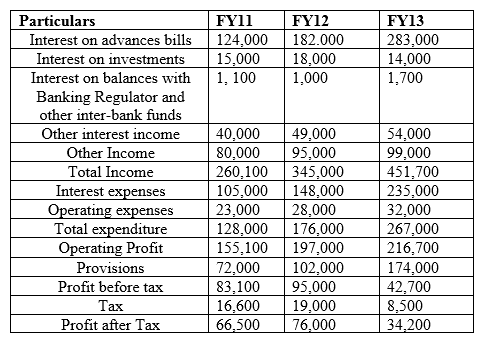 Balance Sheet
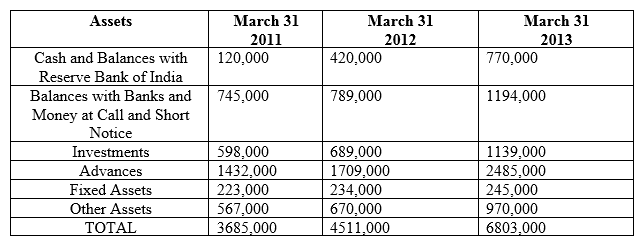
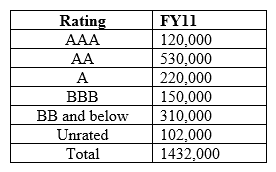
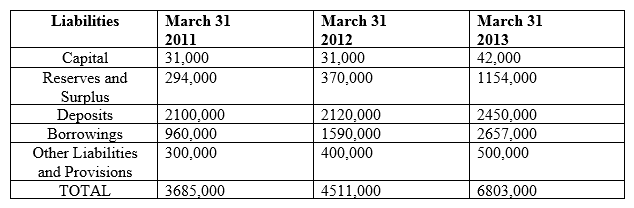 The rating wise break-up of assets for FY11 is as follows:
 The ROTA for Auckland deteriorated from ___in FY12 to___ in FY13.
Balance Sheet The rating wise break-up of assets for FY11 is as follows: The ROTA for Auckland deteriorated from ___in FY12 to___ in FY13. (Multiple Choice)
4.9/5 (70)
(70) Which of the following shall not be used as a source of information for the credit risk assessment?
(Multiple Choice)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)