



 Chat with AI
Exam 16: Accounting for Income Taxes

Exam 1: Environment and Theoretical Structure of Financial Accounting144 Questions
Exam 2: Review of the Accounting Process124 Questions
Exam 3: The Balance Sheet and Financial Disclosures111 Questions
Exam 4: The Income Statement, comprehensive Income, and the Statement of Cash Flows103 Questions
Exam 5: Income Measurement347 Questions
Exam 6: Time Value of Money Concepts109 Questions
Exam 7: Cash and Receivables160 Questions
Exam 8: Inventories: Measurement129 Questions
Exam 9: Inventories: Additional Issues124 Questions
Exam 10: Property, plant, and Equipment and Intangible Assets: Acquisition and Disposition120 Questions
Exam 11: Property, plant, and Equipment and Intangible Assets: Utilization and Impairment133 Questions
Exam 12: Investments179 Questions
Exam 13: Current Liabilities and Contingencies116 Questions
Exam 14: Bonds and Long-Term Notes147 Questions
Exam 15: Leases143 Questions
Exam 16: Accounting for Income Taxes155 Questions
Exam 17: Pensions and Other Postretirement Benefits196 Questions
Exam 18: Shareholders Equity158 Questions
Exam 19: Share-Based Compensation and Earnings Per Share179 Questions
Exam 20: Accounting Changes125 Questions
Exam 21: The Statement of Cash Flows155 Questions
Select questions type


North Dakota Corporation began operations in January 2015 and purchased a machine for $20,000.North Dakota uses straight-line depreciation over a four-year period for financial reporting purposes.For tax purposes,the deduction is 50% of cost in 2015,30% in 2016,and 20% in 2017.Pretax accounting income for 2015 was $150,000,which includes interest revenue of $20,000 from municipal bonds.The enacted tax rate is 30% for all years.There are no other differences between accounting and taxable income.
Required:
Prepare a journal entry to record income taxes for the year 2015.Show well-labeled computations for the amount of income tax payable and the change in the deferred tax account.
(Essay)
4.8/5  (87)
(87) Why are differences in reported amounts for deferred taxes are among the most frequent between IFRS and U.S.GAAP,despite the fact that the two follow similar approaches for accounting for taxation?
(Essay)
4.9/5 (81)
(81) What should Kent report as the current portion of its income tax expense in the year 2016?
(Multiple Choice)
4.9/5 (73)
(73) A deferred tax asset represents the tax effect of the temporary difference between the financial carrying value of an asset or liability and its tax basis.
(True/False)
4.7/5 (80)
(80) The following information is for James Industries' first year of operations.Amounts are in millions of dollars. 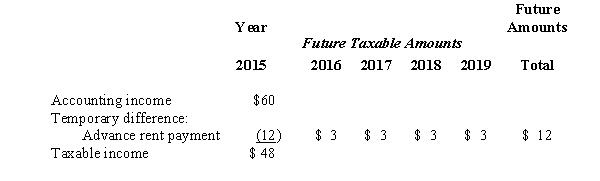 In 2016 the company's pretax accounting income was $67.The enacted tax rate for 2015 and 2016 is 40%,and it is 35% for years after 2016.
Required:
Prepare a journal entry to record the income tax expense for the year 2016.Show well-labeled computations for income tax payable and the change in the deferred tax account.
In 2016 the company's pretax accounting income was $67.The enacted tax rate for 2015 and 2016 is 40%,and it is 35% for years after 2016.
Required:
Prepare a journal entry to record the income tax expense for the year 2016.Show well-labeled computations for income tax payable and the change in the deferred tax account. (Essay)
4.7/5 (90)
(90) Which of the following differences between financial accounting and tax accounting ordinarily creates a deferred tax liability?
(Multiple Choice)
4.9/5 (68)
(68) At December 31,2016,Moonlight Bay Resorts had the following deferred income tax items:
Deferred tax asset of $54 million related to a current liability
Deferred tax asset of $36 million related to a noncurrent liability
Deferred tax liability of $120 million related to a noncurrent asset
Deferred tax liability of $72 million related to a current asset
Moonlight Bay should report in the current section of its December 31,2016,balance sheet a:
(Multiple Choice)
4.8/5 (82)
(82) Prepare two disclosure notes for Typical's year 2016 financial statements to:
(a. )Show the composition of Typical's income tax expense for the year.
(b. )Explain the classification and description of the deferred tax liability.
Give supporting computations to show how you arrived at the dollar amounts disclosed in your disclosure notes.
(Essay)
4.9/5 (88)
(88) A reconciliation of pretax financial statement income to taxable income is shown below for See Shipping for the year ended December 31,2016,its first year of operations.The income tax rate is 40%. 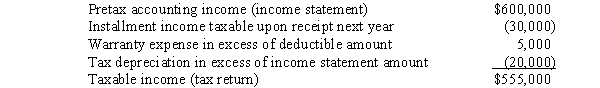 What amount should See report as a current item related to deferred income taxes in its 2016 balance sheet?
 (Multiple Choice)
4.8/5 (88)
(88) Four independent situations are described below.Each involves future deductible amounts and/or future taxable amounts produced by temporary differences reported first on:
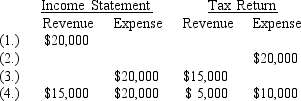 Required:
For each situation,determine the taxable income assuming pretax accounting income is $100,000.Show well-labeled computations.
Required:
For each situation,determine the taxable income assuming pretax accounting income is $100,000.Show well-labeled computations. (Essay)
4.8/5 (69)
(69) Use the following to answer questions
The following information relates to Franklin Freightways for its first year of operations (data in millions of dollars):
 The applicable tax rate is 40%.There are no other temporary or permanent differences.
-Franklin's taxable income ($ in millions)is:
The applicable tax rate is 40%.There are no other temporary or permanent differences.
-Franklin's taxable income ($ in millions)is: (Multiple Choice)
4.8/5 (81)
(81) Giada Foods reported $940 million in income before income taxes for 2016,its first year of operations.Tax depreciation exceeded depreciation for financial reporting purposes by $100 million.The company also had non-tax-deductible expenses of $80 million relating to permanent differences.The income tax rate for 2016 was 35%,but the enacted rate for years after 2016 is 40%.The balance in the deferred tax liability in the December 31,2016,balance sheet is:
(Multiple Choice)
4.9/5 (91)
(91) Use the following to answer questions
Puritan Corp.reported the following pretax accounting income and taxable income for its first three years of operations:
 Puritan's tax rate is 40% for all years.Puritan elected a loss carryback.
As of December 31,2016.Puritan was certain that it would recover the full tax benefit of the
NOL that remained after the operating loss carryback.
-What did Puritan report on December 31,2016,as the deferred tax asset for the NOL
Carryforward?
Puritan's tax rate is 40% for all years.Puritan elected a loss carryback.
As of December 31,2016.Puritan was certain that it would recover the full tax benefit of the
NOL that remained after the operating loss carryback.
-What did Puritan report on December 31,2016,as the deferred tax asset for the NOL
Carryforward? (Multiple Choice)
4.8/5 (83)
(83) Estimated employee compensation expenses earned during the current period but expected to be paid in the next period causes:
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)