



 Chat with AI
Exam 15: Perfect Competition

Exam 1: Getting Started347 Questions
Exam 2: The U.S.and Global Economies211 Questions
Exam 3: The Economic Problem283 Questions
Exam 4: Demand and Supply334 Questions
Exam 5: Elasticities of Demand and Supply342 Questions
Exam 6: Efficiency and Fairness of Markets362 Questions
Exam 7: Government Actions in Markets248 Questions
Exam 8: Taxes270 Questions
Exam 9: Global Markets in Action281 Questions
Exam 10: Externalities301 Questions
Exam 11: Public Goods and Common Resources180 Questions
Exam 12: Markets with Private Information103 Questions
Exam 13: Consumer Choice and Demand295 Questions
Exam 14: Production and Cost274 Questions
Exam 15: Perfect Competition285 Questions
Exam 16: Monopoly384 Questions
Exam 17: Monopolistic Competition221 Questions
Exam 18: Oligopoly228 Questions
Exam 19: Markets for Factors of Production188 Questions
Exam 20: Economic Inequality164 Questions
Select questions type


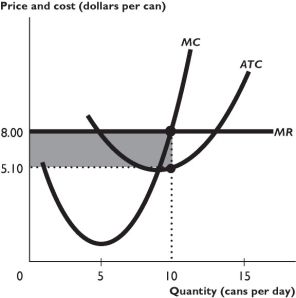 The figure above shows some of a firm's cost curves and its marginal revenue curve.
-Based on the figure above,what is the price of a can?
The figure above shows some of a firm's cost curves and its marginal revenue curve.
-Based on the figure above,what is the price of a can? (Multiple Choice)
5.0/5  (95)
(95)  The above figure shows some a firm's cost curves and its marginal revenue curve.
-Suppose the price of a can was $5.14.In this case,to maximize its profit the firm illustrated in the figure above would
The above figure shows some a firm's cost curves and its marginal revenue curve.
-Suppose the price of a can was $5.14.In this case,to maximize its profit the firm illustrated in the figure above would (Multiple Choice)
4.9/5 (87)
(87) One requirement for an industry to be perfectly competitive is that
(Multiple Choice)
4.8/5 (70)
(70) Keith is a perfectly competitive carnation grower.The market price is $2 per dozen carnations.Keith's average total cost to grow carnations is $2.50 per dozen.In the long run,Keith will
(Multiple Choice)
4.7/5 (74)
(74) If perfectly competitive firms are making an economic profit,then
(Multiple Choice)
4.9/5 (84)
(84) A perfectly competitive furniture-rental firm in Phoenix incurs an economic loss if the average total cost of each rental is
(Multiple Choice)
4.8/5 (78)
(78) For a perfectly competitive firm,profit maximization occurs when output is such that
(Multiple Choice)
5.0/5 (58)
(58) Will a perfectly competitive firm ever produce in the short run even though it is suffering an economic loss?
(Essay)
4.8/5 (81)
(81) Alice,Bud,and Celia can produce rubber bands in a perfectly competitive market.If they enter the market,the minimum average total cost for a bundle of rubber bands,for the three of them is $2,$3,and $4,respectively.If the market price is $2.10 per bundle,then
(Multiple Choice)
4.9/5 (77)
(77) Perfect competition ________ an efficient outcome because ________.
(Multiple Choice)
4.9/5 (93)
(93) If a perfectly competitive firm finds that price is less than its ATC,then the firm
(Multiple Choice)
4.9/5 (71)
(71) Technological change brings a ________ to firms that adopt the new technology.
(Multiple Choice)
5.0/5 (74)
(74) 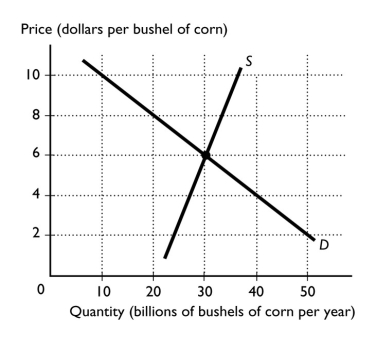 -Farmer Brown produces corn in a perfectly competitive market.Farmer Brown produces and sells 500 bushels of corn.The market supply and demand curves are illustrated in the above figure.
a.What is Farmer Brown's total revenue?
b.What is Farmer Brown's marginal revenue?
-Farmer Brown produces corn in a perfectly competitive market.Farmer Brown produces and sells 500 bushels of corn.The market supply and demand curves are illustrated in the above figure.
a.What is Farmer Brown's total revenue?
b.What is Farmer Brown's marginal revenue? (Essay)
4.7/5 (71)
(71) 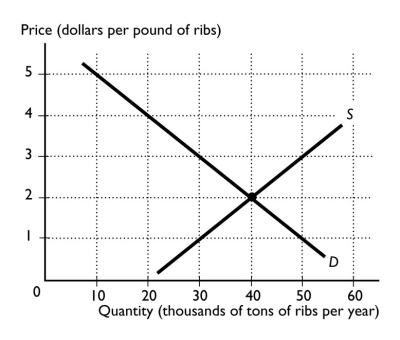
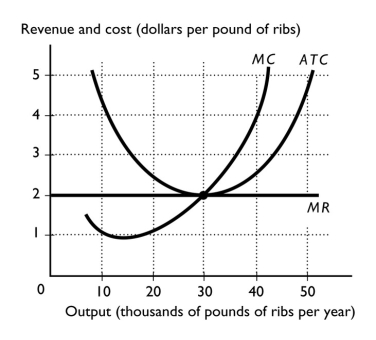 -American restaurants receive their supply of baby back-ribs from American farms and from farms in Denmark.In the figures above,the left diagram shows the perfectly competitive market for baby back ribs in the United States.The right figure shows the situation at Premium Standard Farm in Kansas,one of the many U.S.farms supplying these ribs.
Now assume that the United States imposes a ban on European meat in response to the foot-and-mouth disease that has infected livestock in Europe.(Which the United States did a few years ago.)In particular,suppose that the U.S.ban decreases the supply by 40 tons a year.Using the figure on the left,show the impact of this ban on the baby back rib market.Using the figure on the right,show the impact on Premium Standard Farm in Kansas.
-American restaurants receive their supply of baby back-ribs from American farms and from farms in Denmark.In the figures above,the left diagram shows the perfectly competitive market for baby back ribs in the United States.The right figure shows the situation at Premium Standard Farm in Kansas,one of the many U.S.farms supplying these ribs.
Now assume that the United States imposes a ban on European meat in response to the foot-and-mouth disease that has infected livestock in Europe.(Which the United States did a few years ago.)In particular,suppose that the U.S.ban decreases the supply by 40 tons a year.Using the figure on the left,show the impact of this ban on the baby back rib market.Using the figure on the right,show the impact on Premium Standard Farm in Kansas. (Essay)
5.0/5 (89)
(89)  -Use the figure above to answer this question.Consider a perfectly competitive firm in a short run equilibrium.Figure ________ shows a firm in bad times because the firm makes a(n)________.
 (Multiple Choice)
4.8/5 (76)
(76) If the price is less than a perfectly competitive firm's minimum average variable cost,the firm
(Multiple Choice)
4.9/5 (88)
(88) Technological change allows perfectly competitive firms to ________ and leads to ________.
(Multiple Choice)
5.0/5 (81)
(81) 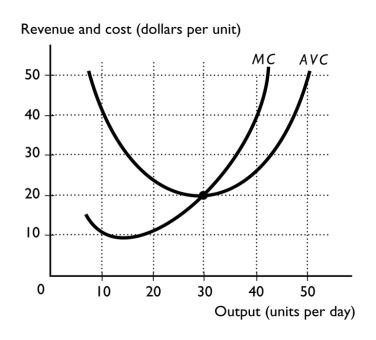 -The above figure illustrates a perfectly competitive firm.If the market price is $10 a unit,to maximize its profit (or minimize its loss)the firm should
 (Multiple Choice)
4.8/5 (85)
(85) Technology reduces the average cost of production,so in the long run
i.perfectly competitive firms produce at a lower average cost.
ii.the market price of the good falls.
iii.firms with older plants either exit the market or adopt the new technology.
(Multiple Choice)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)