



 Chat with AI
Exam 18: Auditing Investments and

Exam 1: Auditing and the Public Accounting69 Questions
Exam 2: Financial Statement Audits and84 Questions
Exam 3: Professional Ethics86 Questions
Exam 4: Auditors Legal Liability67 Questions
Exam 5: Overview of the Audit Process49 Questions
Exam 6: Audit Evidence, Audit Objectives,71 Questions
Exam 7: Accepting the Engagement and56 Questions
Exam 8: Materiality Decisions and Performing Analytical Procedures47 Questions
Exam 9: Audit Risk, Including the Risk of Fraud44 Questions
Exam 10: Understanding Internal Controls91 Questions
Exam 11: Audit Procedures in Response to Assessed Risks: Tests of Controls18 Questions
Exam 12: Audit Procedures in Response to Assessed Risks: Substantive Tests82 Questions
Exam 13: Audit Sampling in Substantive Tests72 Questions
Exam 14: Auditing the Revenue Cycle72 Questions
Exam 15: Auditing the Expenditure Cycle80 Questions
Exam 16: Auditing the Production and81 Questions
Exam 17: Auditing the Investing and77 Questions
Exam 18: Auditing Investments and92 Questions
Exam 19: Completing the Audit and Postaudit102 Questions
Exam 20: Attest and Assurance Services, and Related Reports61 Questions
Exam 21: Internal, Operational, and103 Questions
Select questions type


The substantive testing of investments does not ordinarily employ analytical procedures.
(True/False)
4.8/5  (79)
(79) Kiting is possible when the same individual can issue and record checks.
(True/False)
4.8/5 (85)
(85) The nature of cash balances and the ability to obtain confirmations from banks minimize inherent risk for most cash balance assertions, especially existence or occurrence and completeness.
(True/False)
4.7/5 (89)
(89) Consider the following financial statement assertions:
-Confirm securities held by others.
_____
(Multiple Choice)
4.8/5 (96)
(96) The confirmation of bank deposit and loan balances with banks provides evidence for which of the following assertions? Existence or Rights and Valuation or Presentation Occurrence Completeness Obligations Allocation or Disclosure
A) 4 4 4
B) 4 4 4 4
C) 4 4 4
D) 4 4 4
(Short Answer)
4.9/5 (72)
(72) Information concerning other arrangements with banks is usually obtained from the client's banks in separate communications. This information is likely to include:
(Multiple Choice)
4.9/5 (74)
(74) Common documents and records relating to the investing cycle would not ordinarily include:
(Multiple Choice)
4.9/5 (65)
(65) During the count of cash on hand, it is not necessary for the auditor to:
(Multiple Choice)
4.9/5 (73)
(73) Authorization for the purchase and sale of marketable securities should be found in the minutes the audit committee meetings.
(True/False)
5.0/5 (76)
(76) Which of the following is correct concerning the inspecting and counting of securities on hand?
(Multiple Choice)
4.8/5 (74)
(74) The auditor is most likely to review the client's bank reconciliation when the acceptable level of detection risk is:
(Multiple Choice)
4.7/5 (95)
(95) Analyzing ratio results relative to expectations based on prior year, budgeted, or other data relates to:
(Multiple Choice)
4.9/5 (72)
(72) The performance of cash cutoff tests provides evidence for which of the following assertions? 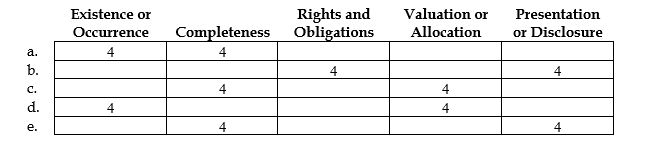
(Short Answer)
4.8/5 (67)
(67) Bank transfers may result in a misstatement of the bank balance per books if the disbursement and receipt are not recorded in the same journal.
(True/False)
4.8/5 (83)
(83) Consider the following financial statement assertions:
-Confirm bank deposit and loan balances with banks.
_____
(Multiple Choice)
5.0/5 (80)
(80) The fact that the quantity of transactions affecting cash are greater than any other account in the financial statements relates to control risk.
(True/False)
4.9/5 (78)
(78) The primary source document for recording investing transactions is the:
(Multiple Choice)
4.7/5 (82)
(82) A surprise confirmation of accounts receivable at an interim date is useful when the auditor suspects:
(Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)