



 Chat with AI
Exam 10: Statement of Cash Flows


Select transactions of Irene Accounting Inc. (IAI)are listed below. IAI uses the indirect method to determine cash flows from operating activities.
1. IAI sells an investment at amortized cost for $28,000. The investment's book value is $20,000.
2. IAI's income tax expense totaled $30,000. Its income tax payable account increased $5,000, while its deferred income tax liability account decreased $18,000.
3. IAI declares a cash dividend of $3,000. The dividends payable account increases $1,000.
4. At year-end IAI increases its allowance for bad debts by $15,000.
Required:
Discuss how the activities listed above would be reported in the statement of cash flows. For items with multiple reporting options, identify all available options. For items not reported on the statement of cash flows, indicate the disclosure requirements, if any.

 (79)
 Verified
1. The $8,000 gain on sale ($28,000 - $20,000 = $8,000)is deducted as an adjustment from net income in the cash flows from operating activities section. The $28,000 cash received is reported as a cash inflow from investments at amortized cost and is included in the investing activities section of the cash flow statement.
2. The $43,000 net cash paid for taxes is reported as a cash outflow from operating activities ($30,000 income tax expense + $18,000 decrease in deferred income taxes payable account - $5,000 decrease in income taxes payable account = $43,000).
3. The net cash outflow of $2,000 ($3000 declared - $1,000 increase in the dividends payable account)is reported as either a cash outflow from operating activities or a cash outflow from financing.
4. The $15,000 is a non-cash expense and will be added back to net income as an adjusting entry in the cash flow from operating activities section. From a practical perspective, this function is accomplished by adjusting net income by the increase or decrease in net accounts receivable.
Angela's Angels Corp.'s policy is to report all cash inflows from interest and dividends in the investing section and cash outflows arising from interest and dividends in the financing section. Angela's activities for the year ended December 31, 2019 included the following:
• Declared and issued a stock dividend valued at $15,000.
• Issued $300,000 in ordinary shares.
• Accounts payable decreased $38,000 during the year.
• Paid $910,000 to repurchase bonds. The book value of the bonds was $1,000,000.
• Made a $25,000 principal payment on a bank loan.
• Interest expense for the period was $12,000. The interest payable account increased $2,000.
• Declared a $12,000 cash dividend payable on January 15, 2020.
• Acquired the right to use an automobile valued at $30,000 under a lease agreement.
Required:
a. Prepare the cash flows from financing activities section of the statement of cash flows.
b. Identify how the activities listed above that are not financing activities would be reported in the statement of cash flows assuming that the statement is prepared using the indirect method.
(74) Verifieda. 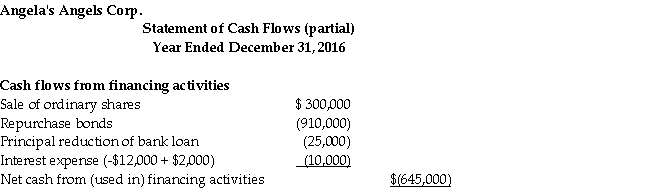 * Note that while interest paid can also be classified as an operating activity, Angela's has adopted a policy of reporting interest and dividend paid as a financing activities.
b.
• The stock dividend is a non-cash activity and is not reported on the statement of cash flows. Note disclosure is appropriate.
• The decrease in accounts payable is reported as a decrease in cash from operating activities.
• The gain on repurchase of bonds will be deducted from net income in the operating activities section (indirect method).
• The declaration of the dividend is not reported on the statement of cash flows as it was not paid in 2019. Rather, this amount is used to explain the change in retained earnings during the year.
• The acquisition of the right to use an automobile under a lease agreement is a non-cash activity and is not reported on the statement of cash flows. Material non-cash transactions are reported in the notes to the financial statements.
If a company has gaps between the change in cash and the net income for the year:
(79) VerifiedC
Why are "cash and cash equivalents" treated as a single unit on the cash flow statement?
(75) The opening balance in the computer account for Adara Corp for fiscal 2020 was $100,000; the closing balance was $107,000. The corresponding balances in the accumulated depreciation accounts were $63,000 and $67,500. During the year Adara scrapped a computer originally costing $13,000 having a remaining net book value of $3,500 and purchased a replacement machine for cash.
Required:
a. Prepare the underlying journal entries to record the foregoing transactions and record events stemming from the transactions.
b. For each entry identify the cash flow effects, if any, under both the direct and indirect methods of presentation and classify the cash flow according to its nature.
(83) ABC Inc.'s policy is to report all cash flows arising from interest and dividends in the operating activities section. Tub Time's activities for the year ended December 31, 2020 included the following:
• Net income after taxes totaled $400,000.
• The company recorded a $4000 goodwill impairment loss during the year.
• Depreciation expense for the year was $24,000.
• Declared and issued a stock dividend valued at $10,000.
• Accounts receivable increased $33,000 in the year.
• Sold an investment at FVPL for $23,000. The book value was $18,000. The investment was held for trading purposes
• Interest revenue for the period was $6,000. The interest receivable account decreased $4,000.
• Declared a $10,000 dividend payable. The dividends payable account decreased $19,000 in the year.
• Sold an investment at FVOCI for $19,000. The original cost was $14,000.
Required:
a. Prepare the cash flows from operating activities section of the statement of cash flows using the indirect method.
b. Identify how the activities listed above that are not operating activities would be required in the statement of cash flows.
(88) Hoboken's activities for the year ended December 31, 2021 included the following: • Sold an investment at FVPL for $12,000. The investment was held for trading purposes. The book value was $10,000.
• Sold an Investment at FVOCI for $8,000. The original cost of the investment was $9,000.
Using the direct method, how much would be presented as cash flow from operations for the investment at FVPL investment?
(81) Rusabh Ltd.'s policy is to report all cash flows arising from interest and dividends in the operating section. Rusabh's activities for the year ended December 31, 2021 included the following:
• Sold an investment at FVPL for $16,000. The book value of this investment, which was held for trading purposes, was $13,000.
• Purchased an investment at FVOCI for $51,000.
• Borrowed $100,000 from the bank for investment purposes.
• Sold equipment for $23,000 that originally cost $55,000. The net book value of this item at time of sale was $35,000.
• Purchased inventory costing $84,000 for cash.
• Received $8,000 in interest and 5,500 in dividends on sundry investments.
• Acquired the right to use forklift costing $32,000 under a lease agreement.
• Acquired land and buildings valued at $100,000 by issuing ordinary shares.
• Bought $400,000 in bonds at a discount, paying $375,000 cash.
Required:
a. Prepare the cash flows from investing activities section of the statement of cash flows.
b. Identify how the activities listed above that are not investing activities would be reported in the statement of cash flows assuming that the statement is prepared using the indirect method.
(73) The activities for the year ended December 31, 2021 included the following: • 2021's net income after taxes totaled $125,000.
• Accounts receivable increased $32,000
• Recorded a $10,000 goodwill impairment loss during the year
• Inventory decreased $8,000
How much would be presented as cash flow from operations?
(80) Select transactions of SimBis Accounting Inc. (SAI)are listed below. SAI uses the indirect method to determine cash flows from operating activities.
1. SAI purchases a $200,000, 45-day Treasury bill and classified it at FVPL.
2. SAI amortizes $32,000 of the discount on bonds payable.
3. At year-end SAI increases its allowance for bad debts by $10,000.
4. SAI's income tax expense totaled $40,000. Its income tax payable account increased $5,000, while its deferred income tax liability account decreased $8,000.
5. SAI acquires the right to use equipment valued at $80,000 under a lease agreement.
6. SAI declares and distributes a stock dividend valued at $33,000.
7. SAI declares a cash dividend of $30,000. The dividends payable account increases $15,000.
8. SAI's comprehensive income for the year totaled $200,000 consisting of $150,000 net income and $50,000 other comprehensive income.
9. SAI sells an investment at amortized cost for $22,000. The investment's amortized cost is $20,000.
Required:
Discuss how the activities listed above would be reported in the statement of cash flows. For items with multiple reporting options, identify all available options. For items not reported on the statement of cash flows, indicate the disclosure requirements, if any.
(91) Briefly describe non-cash transactions and how they are reported on the statement of cash flows.
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)