



 Chat with AI
Exam 2: Fund Accounting

Exam 1: The Government and Not-For-Profit Environment50 Questions
Exam 2: Fund Accounting68 Questions
Exam 3: Issues of Budgeting and Control69 Questions
Exam 4: Recognizing Revenues in Governmental Funds73 Questions
Exam 5: Recognizing Expenditures in Governmental Funds81 Questions
Exam 6: Accounting for Capital Projects and Debt Service79 Questions
Exam 7: Capital Assets and Investments in Marketable Securities65 Questions
Exam 8: Long-Term Obligations60 Questions
Exam 9: Business-Type Activities79 Questions
Exam 10: Pensions and Other Fiduciary Activities74 Questions
Exam 11: Issues of Reporting, Disclosure, and Financial Analysis79 Questions
Exam 12: Not-For-Profit Organizations66 Questions
Exam 13: Colleges and Universities24 Questions
Exam 14: Health-Care Providers49 Questions
Exam 15: Auditing Governments and Not-For-Profit Organizations62 Questions
Exam 16: Federal Government Accounting71 Questions
Select questions type


Fiduciary activities are where governments act as trustee or custodians for individuals or entities other than itself.
(True/False)
4.9/5  (74)
(74) Which of the following funds of Chessie City would be consolidated to form the governmental activities column in the city's government-wide financial statements?
(Multiple Choice)
4.9/5 (82)
(82) The Financial Accounting Standards Board requires all nongovernmental not-for-profit entities to use fund accounting.
(True/False)
4.8/5 (77)
(77) The City of San Jose built a new city hall and financed construction by issuing bonds due in installments over the next 30 years. The proceeds will be accounted for in which of the following funds?
(Multiple Choice)
4.9/5 (73)
(73) Which fund type would all governments normally include in their fund financial statements?
(Multiple Choice)
4.8/5 (75)
(75) Under the GASB Statement No. 34 reporting model, which of the following is required?
(Multiple Choice)
4.9/5 (75)
(75) Katerah City maintains the following funds:
-General
-Special revenue
-Capital projects
-Debt service
-Enterprise
-Investment trust
-Permanent
-Agency
For each of the following transactions, indicate which fund would most likely be used to report the transaction:
a. The city collects $1 million of taxes for an independent fire district located within the city.
b. The city spends $1.2 million on street maintenance using the proceeds of a city gas tax dedicated for road and highway maintenance and improvements.
c. The city receives a bequest of $1.5 million. The donor's will, requires that the principal amount be invested in perpetuity and that the earnings on the investment be used to maintain a city park to be renamed for the donor.
d. The city collects water and sewer fees of $4.2 million.
e. The city pays $4 million to a contractor for work on a new bridge.
f. The city receives $1.3 million to invest on behalf of the county.
g. The city pays its police officers wages of $325,000.
h. The city pays $2.2 million in bond interest on its general obligation debt.
(Short Answer)
4.9/5 (88)
(88) The newly established Environmental Council (a nongovernmental not-for-profit organization) uses two funds for internal reporting purposes. The general fund is used to record day-to-day operating transactions. A building fund is used to accumulate resources for a new building to house the Council's operations. Both funds are reported using the accrual basis of accounting. In its first year, the Council engaged in the following transactions:
-It received cash contributions of $500,000. Donors stipulate that $100,000 of this amount must be used for the new building.
-It incurred operating payroll costs of $200,000, of which $180,000 is paid in cash.
-It earned $1,000 in interest (paid in cash) on investments restricted to the acquisition of the new building.
-It transferred $25,000 from its general fund to the building fund.
-It paid $15,000 in fees (accounted for as expenses) for architectural drawings for the proposed building.
a. Prepare journal entries to record the transactions. Be sure to indicate the fund in which the entry would be made.
b. Prepare a statement of revenues, expenses, and other changes in fund balances and a balance sheet. Use a two-column format, one column for each of the Council's two funds.
(Essay)
4.8/5 (86)
(86) Kayla Township issued the following bonds during the year: 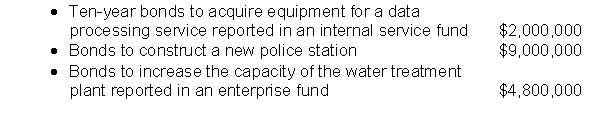 a. The amount of debt reported in the Township's general fund is:
1. $0
2. $9,000,000
3. $11,000,000
4. $15,800,000
b. The township should report depreciation expense on related new capital assets in:
1. General fund
2. Enterprise fund
3. Enterprise and internal service funds
4. Capital projects fund
c. The bonds issued to construct the new police station should be reported as:
1. Debt proceeds in the general fund
2. Long-term debt in a debt service fund
3. Debt proceeds in a capital projects fund
4. None of the above
d. In accordance with bond covenants the township sets aside $1,000,000 to help ensure that it is able to meet its first payment of principal and interest on the police station debt due one year from the date the bonds were issued. The amount of liability that the township should report in its debt service fund is:
1. $0
2. $1,000,000
3. $9,000,000
4. $8,000,000
a. The amount of debt reported in the Township's general fund is:
1. $0
2. $9,000,000
3. $11,000,000
4. $15,800,000
b. The township should report depreciation expense on related new capital assets in:
1. General fund
2. Enterprise fund
3. Enterprise and internal service funds
4. Capital projects fund
c. The bonds issued to construct the new police station should be reported as:
1. Debt proceeds in the general fund
2. Long-term debt in a debt service fund
3. Debt proceeds in a capital projects fund
4. None of the above
d. In accordance with bond covenants the township sets aside $1,000,000 to help ensure that it is able to meet its first payment of principal and interest on the police station debt due one year from the date the bonds were issued. The amount of liability that the township should report in its debt service fund is:
1. $0
2. $1,000,000
3. $9,000,000
4. $8,000,000 (Short Answer)
5.0/5 (86)
(86) A not-for-profit entity's statement of activities will report which of the following?
(Multiple Choice)
4.9/5 (83)
(83) GASB Statement No. 34 mandates that the government reconcile total governmental fund balances per the fund balance sheet with net assets of governmental activities per the government-wide statements. What are likely to be the two largest reconciling items for most major cities? Why?
(Essay)
4.9/5 (85)
(85) Assume that the City of Fort Smith maintains its books and records in a manner that facilitates the preparation of fund financial statements. For each of the following events indicate in which fund(s) of the city the event would be recorded and justify your fund selection.
a. The city collected property taxes levied for the general operations of the city.
b. The city collected property taxes levied to pay principal and interest on bonds issued several years in the past to construct a new fire station.
c. The city collected property taxes levied on a specific area of the city for the purposes of providing more frequent snow removal than is enjoyed by the rest of the city.
d. The city sold bonds to finance the construction of a new city hall.
e. The city sold bonds to finance major renovations at the city-owned electric utility.
f. The city purchased a street sweeping machine.
(Essay)
4.9/5 (75)
(75) For which of the following entities is fund accounting mandated for financial reporting?
(Multiple Choice)
4.9/5 (79)
(79) What is the primary reason that governmental entities use fund accounting?
(Multiple Choice)
4.9/5 (94)
(94) Why is long-term debt generally not reported in a government's debt service funds?
(Essay)
5.0/5 (85)
(85) FASB requires that not-for-profit entities classify net assets into the following i. Not Restricted
ii. Restricted
iii. Temporarily Restricted
(Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)