



 Chat with AI
Exam 7: Capital Assets and Investments in Marketable Securities

Exam 1: The Government and Not-For-Profit Environment50 Questions
Exam 2: Fund Accounting68 Questions
Exam 3: Issues of Budgeting and Control69 Questions
Exam 4: Recognizing Revenues in Governmental Funds73 Questions
Exam 5: Recognizing Expenditures in Governmental Funds81 Questions
Exam 6: Accounting for Capital Projects and Debt Service79 Questions
Exam 7: Capital Assets and Investments in Marketable Securities65 Questions
Exam 8: Long-Term Obligations60 Questions
Exam 9: Business-Type Activities79 Questions
Exam 10: Pensions and Other Fiduciary Activities74 Questions
Exam 11: Issues of Reporting, Disclosure, and Financial Analysis79 Questions
Exam 12: Not-For-Profit Organizations66 Questions
Exam 13: Colleges and Universities24 Questions
Exam 14: Health-Care Providers49 Questions
Exam 15: Auditing Governments and Not-For-Profit Organizations62 Questions
Exam 16: Federal Government Accounting71 Questions
Select questions type


At what value should the new truck be reported in the government-wide financial statements?
(Multiple Choice)
4.9/5  (74)
(74) With regard to accounting for infrastructure, which of the following is true?
(Multiple Choice)
4.8/5 (77)
(77) Governments invest in marketable securities for much the same reason that businesses do-to earn a return on cash that otherwise would be unproductive.
(True/False)
4.8/5 (85)
(85) Governments must disclose information about investment risks in which of the following categories?
(Multiple Choice)
4.8/5 (88)
(88) Changes in the fair value of derivative instruments that qualify as hedges should be reported as
(Multiple Choice)
4.8/5 (67)
(67) Mariano County traded in a used pickup for a new pickup truck with a sticker price of $44,000. The old pickup had a fair value of $26,000, historical cost of $45,000, and accumulated depreciation of $18,000. The dealer took the old truck and $15,000 for the new truck.
-The amount of gain or loss that should be recognized on this transaction in the government-wide financial statements is
(Multiple Choice)
4.7/5 (68)
(68) In 1991, Katie City constructed a new Fifth Avenue bridge. The city has no records of the cost of the bridge. The city's engineers estimate that the current replacement cost (2016) of the bridge is $24 million. The construction price index was 150 in 1991 and is 200 in 2016. The engineers also estimate that the bridge has a total useful life of 30 years.
REQUIRED:
a. What values should the city assign to the bridge for estimated historical cost and accumulated depreciation?
b. Suppose the city decided to use the modified approach to report its bridges. What value would the city assign to the bridge?
c. In your opinion, would a depreciation charge for the bridge add significant information to the city's financial statements? Why or why not?
(Essay)
4.8/5 (69)
(69) The table below lists the types of investments reported by the Lisbet City in its general fund. All of the investments of the general fund will be needed to liquidate liabilities within the next six to twelve months. What types of investment risks should the city disclose? 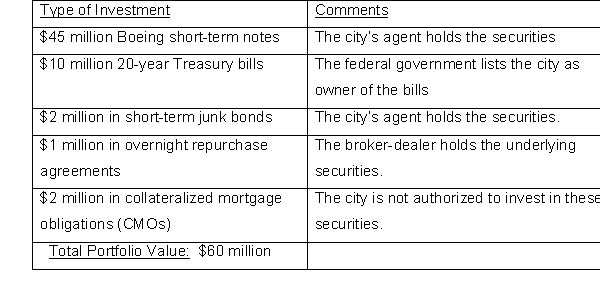
(Essay)
4.8/5 (75)
(75) Governments do not have to depreciate infrastructure assets if governments can demonstrate they are preserving these assets at a specified condition level.
(True/False)
4.8/5 (86)
(86) The government-wide financial statements report capital assets:
(Multiple Choice)
4.7/5 (82)
(82) FASB and GASB require that all debt and equity securities be recorded at historical cost.
(True/False)
4.8/5 (70)
(70) The City of Baconsville engaged in the following transactions. Assume that the city maintains its books and records in a manner that facilitates the preparation of the government-wide financial statements.
Required: Prepare the appropriate journal entries. If appropriate, write "No entry required."
a) The city purchased for cash three dump trucks for $80,000 each.
b) The city sold for $4,000, a police car that had been purchased four years ago at a cost of $30,000. At the time of acquisition, the city estimated that the police car had a useful life of five years and a salvage value of $5,000.
c) During the year, the city spent $12 million to build a third lane on both sides of the major north-south highway through town.
d) The city traded in a pickup truck used in general government operations for a new pickup truck, paying a difference of $18,000. The old pickup truck was purchased four years ago at a cost of $21,000. At the time it had an estimated useful life of five years, and an estimated salvage value of $6,000. At the time of the trade, the old truck had a fair value of $10,000. The new truck has a sticker price of $29,000.
e) During the year the city began construction of a new city hall. By year-end, the city had made progress payments to the contractor of $3 million.
f) The city received a gift of land from a citizen. The land is to be used to build a city park. The land had been in the donor's family since it was homesteaded. It has a fair value when contributed of $2 million.
(Essay)
4.9/5 (69)
(69) Most infrastructure assets are the responsibility of the federal government, not state and local governments.
(True/False)
4.9/5 (75)
(75) A drunk driver crashed into a fully loaded gasoline truck while trying to pass on a city's Main Avenue bridge. The truck exploded and the heat of the fire caused a portion of the structure of the bridge to melt. The city did not use the modified approach to report the bridge. Rather, its historical cost of $10 million was being depreciated over 20 years with no expected salvage value. The bridge was 10 years old. Its current replacement cost is $20 million. The city's engineers estimate that it will take $8 million to restore the bridge.
REQUIRED:
a. What is the deflated restoration cost for the bridge, calculated as using the restoration approach?
b. If an impairment loss is calculated by dividing the deflated restoration cost by the asset's original historical cost and then multiplying that percentage times the carrying amount of the bridge, what is the city's impairment loss?
c. Assuming the city makes the $8 million of repairs, how should the city report this cost?
(Essay)
4.9/5 (70)
(70) For a government that elects to capitalize its works of art and similar assets, the appropriate entry for reporting in the government-wide financial statements when receiving a contribution of a work of art is
(Multiple Choice)
4.7/5 (81)
(81) Which of the following is true with regard to deferred maintenance?
(Multiple Choice)
4.8/5 (68)
(68) If a government elects to capitalize certain works of art and similar assets, which of the following statements is true relative to depreciation on those assets?
(Multiple Choice)
4.8/5 (83)
(83) Under the modified approach, initial costs are capitalized while preservation costs are expensed when incurred.
(True/False)
4.9/5 (75)
(75) The "restoration cost" approach to determining the extent of a capital asset impairment
(Multiple Choice)
4.7/5 (67)
(67) The following information pertains to a city government.
A. The city (1) purchased a 3-year, 7 percent U.S. Treasury note (2) used the note to enter into a 90-day short-term loan transaction that incorporated an interest rate of 6 percent and (3) used the proceeds from the short-term loan transaction to purchase another 3-year 7 percent U.S. Treasury note. What are the benefits and risks of the city's investment practices?
B. In 2015 the city constructed a new highway at a cost of $120 million. In the years following 2015, the city did not record a depreciation charge on the highway - not even in its government-wide statements. Can the omission of the depreciation charge be justified under GASB standards? Explain.
(Essay)
4.8/5 (64)
(64) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)