



 Chat with AI
Exam 9: Financial Modeling Basics:

Exam 1: Introduction to Mergers, Acquisitions, and Other Restructuring Activities139 Questions
Exam 2: The Regulatory Environment129 Questions
Exam 3: The Corporate Takeover Market:152 Questions
Exam 4: Planning: Developing Business and Acquisition Plans: Phases 1 and 2 of the Acquisition Process137 Questions
Exam 5: Implementation: Search Through Closing: Phases 310 of the Acquisition Process131 Questions
Exam 6: Postclosing Integration: Mergers, Acquisitions, and Business Alliances138 Questions
Exam 7: Merger and Acquisition Cash Flow Valuation Basics108 Questions
Exam 8: Relative, Asset-Oriented, and Real Option109 Questions
Exam 9: Financial Modeling Basics:97 Questions
Exam 10: Analysis and Valuation127 Questions
Exam 11: Structuring the Deal:138 Questions
Exam 12: Structuring the Deal:125 Questions
Exam 13: Financing the Deal149 Questions
Exam 14: Applying Financial Modeling116 Questions
Exam 15: Business Alliances: Joint Ventures, Partnerships, Strategic Alliances, and Licensing138 Questions
Exam 16: Alternative Exit and Restructuring Strategies152 Questions
Exam 17: Alternative Exit and Restructuring Strategies:118 Questions
Exam 18: Cross-Border Mergers and Acquisitions:120 Questions
Select questions type


Trend extrapolation, which entails extending present trends into the future using historical growth rates or multiple regression techniques, is rarely used to forecast cash flow.
(True/False)
4.9/5  (76)
(76) What are common size financial statements and how might they impact the financial model building process?
(Essay)
4.8/5 (66)
(66) Ford Acquires Volvo’s Passenger Car Operations
This case illustrates how the dynamically changing worldwide automotive market is spurring a move toward consolidation among automotive manufacturers. The Volvo financials used in the valuation are for illustration only— they include revenue and costs for all of the firm’s product lines. For purposes of exposition, we shall assume that Ford’s acquisition strategy with respect to Volvo was to acquire all of Volvo’s operations and later to divest all but the passenger car and possibly the truck operations. Note that synergy in this business case is determined by valuing projected cash flows generated by combining the Ford and Volvo businesses rather than by subtracting the standalone values for the Ford and Volvo passenger car operations from their combined value including the effects of synergy. This was done because of the difficulty in obtaining sufficient data on the Ford passenger car operations.
Background
By the late 1990s, excess global automotive production capacity totaled 20 million vehicles, and three-fourths of the auto manufacturers worldwide were losing money. Consumers continued to demand more technological innovations, while expecting to pay lower prices. Continuing mandates from regulators for new, cleaner engines and more safety measures added to manufacturing costs. With the cost of designing a new car estimated at $1.5 billion to $3 billion, companies were finding mergers and joint ventures an attractive means to distribute risk and maintain market share in this highly competitive environment.
By acquiring Volvo, Ford hoped to expand its 10% worldwide market share with a broader line of near-luxury Volvo sedans and station wagons as well as to strengthen its presence in Europe. Ford saw Volvo as a means of improving its product weaknesses, expanding distribution channels, entering new markets, reducing development and vehicle production costs, and capturing premiums from niche markets. Volvo Cars is now part of Ford’s Premier Automotive Group, which also includes Aston Martin, Jaguar, and Lincoln. Between 1987 and 1998, Volvo posted operating profits amounting to 3.7% of sales. Excluding the passenger car group, operating margins would have been 5.3%. To stay competitive, Volvo would have to introduce a variety of new passenger cars over the next decade. Volvo viewed the capital expenditures required to develop new cars as overwhelming for a company its size.
Historical and Projected Data
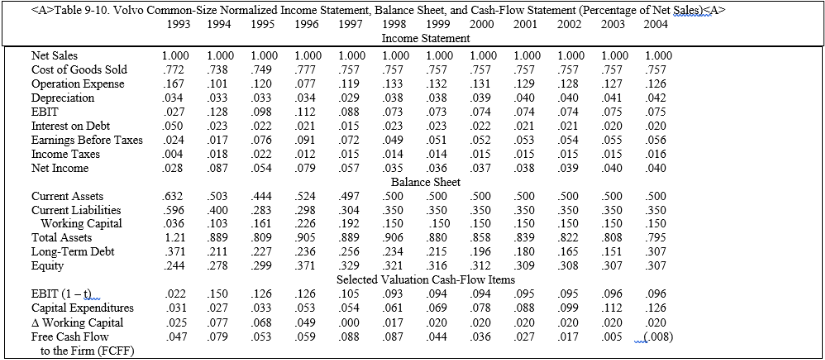
The initial review of Volvo’s historical data suggests that cash flow is highly volatile. However, by removing nonrecurring events, it is apparent that Volvo’s cash flow is steadily trending downward from its high in 1997. Table 9-10 displays a common-sized, normalized income statement, balance sheet, and cash-flow statement for Volvo, including both the historical period from 1993 through 1999 and a forecast period from 2000 through 2004. Although Volvo has managed to stabilize its cost of goods sold as a percentage of net sales, operating expenses as a percentage of net revenue have escalated in recent years. Operating margins have been declining since 1996. To regain market share in the passenger car market, Volvo would have to increase substantially its capital outlays. The primary reason valuation cash flow turns negative by 2004 is the sharp increase in capital outlays during the forecast period. Ford’s acquisition of Volvo will enable volume discounts from vendors, reduced development costs as a result of platform sharing, access to wider distribution networks, and increased penetration in selected market niches because of the Volvo brand name. Savings from synergies are phased in slowly over time, and they will not be fully realized until 2004. There is no attempt to quantify the increased cash flow that might result from increased market penetration.
 Determining the Initial Offer Price
Volvo’s estimated value on a standalone basis is $15 billion. The present value of anticipated synergy is $1.1 billion, suggesting that the purchase price for Volvo should lie within a range of $15 million to about $16 billion. Although potential synergies appear to be substantial, savings due to synergies will be phased in gradually between 2000 and 2004. The absence of other current bidders for the entire company and Volvo’s urgent need to fund future capital expenditures in the passenger car business enabled Ford to set the initial offer price at the lower end of the range. Thus, the initial offer price could be conservatively set at about $15.25 billion, reflecting only about one-fourth of the total potential synergy resulting from combining the two businesses. Other valuation methodologies tended to confirm this purchase price estimate. The market value of Volvo was $11.9 billion on January 29, 1999. To gain a controlling interest, Ford had to pay a premium to the market value on January 29, 1999. Applying the 26% premium Ford paid for Jaguar, the estimated purchase price including the premium is $15 billion, or $34 per share. This compares to $34.50 per share estimated by dividing the initial offer price of $15.25 billion by Volvo’s total common shares outstanding of 442 million.
Determining the Appropriate Financing Structure
Ford had $23 billion in cash and marketable securities on hand at the end of 1998 (Naughton, 1999). This amount of cash is well in excess of its normal cash operating requirements. The opportunity cost associated with this excess cash is equal to Ford’s cost of capital, which is estimated to be 11.5%—about three times the prevailing interest on short-term marketable securities at that time. By reinvesting some portion of these excess balances to acquire Volvo, Ford would be adding to shareholder value, because the expected return, including the effects of synergy, exceeds the cost of capital. Moreover, by using this excess cash, Ford also is making itself less attractive as a potential acquisition target. The acquisition is expected to increase Ford’s EPS. The loss of interest earnings on the excess cash balances would be more than offset by the addition of Volvo’s pretax earnings.
Epilogue
Seven months after the megamerger between Chrysler and Daimler-Benz in 1998, Ford Motor Company announced that it was acquiring only Volvo’s passenger-car operations. Ford acquired Volvo’s passenger car operations on March 29, 1999, for $6.45 billion. At $16,000 per production unit, Ford’s offer price was considered generous when compared with the $13,400 per vehicle that Daimler-Benz AG paid for Chrysler Corporation in 1998. The sale of the passenger car business allows Volvo to concentrate fully on its truck, bus, construction equipment, marine engine, and aerospace equipment businesses. (Note that the standalone value of Volvo in the case was estimated to be $15 billion. This included Volvo’s trucking operations.)
-What is the purpose of the common-size financial statements developed for Volvo (see Table 8-8 in the textbook)? What insights does this table provide about the historical trend in Volvo's historical performance? Based on past performance, how realistic do you think the projections are for 2000-2004?
Determining the Initial Offer Price
Volvo’s estimated value on a standalone basis is $15 billion. The present value of anticipated synergy is $1.1 billion, suggesting that the purchase price for Volvo should lie within a range of $15 million to about $16 billion. Although potential synergies appear to be substantial, savings due to synergies will be phased in gradually between 2000 and 2004. The absence of other current bidders for the entire company and Volvo’s urgent need to fund future capital expenditures in the passenger car business enabled Ford to set the initial offer price at the lower end of the range. Thus, the initial offer price could be conservatively set at about $15.25 billion, reflecting only about one-fourth of the total potential synergy resulting from combining the two businesses. Other valuation methodologies tended to confirm this purchase price estimate. The market value of Volvo was $11.9 billion on January 29, 1999. To gain a controlling interest, Ford had to pay a premium to the market value on January 29, 1999. Applying the 26% premium Ford paid for Jaguar, the estimated purchase price including the premium is $15 billion, or $34 per share. This compares to $34.50 per share estimated by dividing the initial offer price of $15.25 billion by Volvo’s total common shares outstanding of 442 million.
Determining the Appropriate Financing Structure
Ford had $23 billion in cash and marketable securities on hand at the end of 1998 (Naughton, 1999). This amount of cash is well in excess of its normal cash operating requirements. The opportunity cost associated with this excess cash is equal to Ford’s cost of capital, which is estimated to be 11.5%—about three times the prevailing interest on short-term marketable securities at that time. By reinvesting some portion of these excess balances to acquire Volvo, Ford would be adding to shareholder value, because the expected return, including the effects of synergy, exceeds the cost of capital. Moreover, by using this excess cash, Ford also is making itself less attractive as a potential acquisition target. The acquisition is expected to increase Ford’s EPS. The loss of interest earnings on the excess cash balances would be more than offset by the addition of Volvo’s pretax earnings.
Epilogue
Seven months after the megamerger between Chrysler and Daimler-Benz in 1998, Ford Motor Company announced that it was acquiring only Volvo’s passenger-car operations. Ford acquired Volvo’s passenger car operations on March 29, 1999, for $6.45 billion. At $16,000 per production unit, Ford’s offer price was considered generous when compared with the $13,400 per vehicle that Daimler-Benz AG paid for Chrysler Corporation in 1998. The sale of the passenger car business allows Volvo to concentrate fully on its truck, bus, construction equipment, marine engine, and aerospace equipment businesses. (Note that the standalone value of Volvo in the case was estimated to be $15 billion. This included Volvo’s trucking operations.)
-What is the purpose of the common-size financial statements developed for Volvo (see Table 8-8 in the textbook)? What insights does this table provide about the historical trend in Volvo's historical performance? Based on past performance, how realistic do you think the projections are for 2000-2004? (Essay)
4.9/5 (69)
(69) The income statement measures a firm's financial performance at a specific point in time.
(True/False)
4.8/5 (60)
(60) Value drivers are factors such as product volume, selling price, and cost of sales that have a significant impact on the value of the firm whenever they are altered.
(True/False)
4.7/5 (59)
(59) It is rarely useful to review more than one or two years of historical data for the acquiring or target firms.
(True/False)
4.9/5 (74)
(74) What does it mean to normalize historical financial data and why is this an important part of the financial model building process?
(Essay)
4.8/5 (92)
(92) Common size financial statements may be constructed by calculating the percentage each line item of the income statement, balance sheet, and cash flow statement is of annual sales for each quarter or year for which historical data are available.
(True/False)
4.7/5 (90)
(90) Use the Microsoft Excel model in a file folder entitled Target Valuation Model on the companion site to this book to address the following questions. The model already contains data and an estimate of Life Tech’s enterprise and equity valuations based on this data and a set of assumptions about the planning period spanning 2014 through 2018, as well as the years beyond. In answering the following questions, assume the valuation provided in this model represents the firm’s base case and reflects what the firm could do if it continued the business strategy in effect in 2012.
-Note the enterprise and equity valuations for Life Technology in the Excel spreadsheet model entitled Target Valuation Model on the companion website accompanying this book. View this as the base case. The CEO Greg Lucier asks his chief financial officer (CFO) to determine the impact of plausible assumption changes on the firm's valuation. The CFO asks you as a financial analyst to estimate the impact of a change in the firm's revenue growth rate and cost of sales as a percent of sales. On the Target Assumptions Worksheet, make the following changes and note their impact on Life Tech's enterprise and equity values on the Valuation Worksheet:
a. Increase the sales growth rate in 2014 by two percentage points
b. Retaining the assumption change made in (a), decrease the cost of sales as a percent of sales by
two percentage points in 2014
What is Life Tech's enterprise and equity value resulting from these changes? How do they compare to the base case? Briefly explain why each of these changes affects firm value. Do not undo the results of your changes to the model's base case.
(Essay)
4.7/5 (80)
(80) A firm's financial statements are tightly linked such that an increase in a key variable on one statement will impact the other financial statements. Assuming a firm's gross margin (i.e., sales less cost of sales) is positive and constant, describe how an increase in revenue will impact net income and in turn the other financial statements? Assume the firm does not pay preferred dividends.
(Essay)
4.9/5 (79)
(79) Historical cash flow may be adjusted by deducting unusually large increases in reserves or by adding back large decreases in reserves from free cash flow to the firm.
(True/False)
4.8/5 (77)
(77) The accuracy of any valuation is heavily dependent on understanding the historical competitive dynamics of the industry, the historical performance of the company within the industry, and the reliability of the data used in the valuation.
(True/False)
4.8/5 (64)
(64) When changing financial model assumptions, which of the following is true?
(Multiple Choice)
5.0/5 (70)
(70) While GAAP does not ensure accuracy, it is helpful to the analyst in that statements that conform to GAAP rules must adhere to certain standards.
(True/False)
4.9/5 (86)
(86) Ford Acquires Volvo’s Passenger Car Operations
This case illustrates how the dynamically changing worldwide automotive market is spurring a move toward consolidation among automotive manufacturers. The Volvo financials used in the valuation are for illustration only— they include revenue and costs for all of the firm’s product lines. For purposes of exposition, we shall assume that Ford’s acquisition strategy with respect to Volvo was to acquire all of Volvo’s operations and later to divest all but the passenger car and possibly the truck operations. Note that synergy in this business case is determined by valuing projected cash flows generated by combining the Ford and Volvo businesses rather than by subtracting the standalone values for the Ford and Volvo passenger car operations from their combined value including the effects of synergy. This was done because of the difficulty in obtaining sufficient data on the Ford passenger car operations.
Background
By the late 1990s, excess global automotive production capacity totaled 20 million vehicles, and three-fourths of the auto manufacturers worldwide were losing money. Consumers continued to demand more technological innovations, while expecting to pay lower prices. Continuing mandates from regulators for new, cleaner engines and more safety measures added to manufacturing costs. With the cost of designing a new car estimated at $1.5 billion to $3 billion, companies were finding mergers and joint ventures an attractive means to distribute risk and maintain market share in this highly competitive environment.
By acquiring Volvo, Ford hoped to expand its 10% worldwide market share with a broader line of near-luxury Volvo sedans and station wagons as well as to strengthen its presence in Europe. Ford saw Volvo as a means of improving its product weaknesses, expanding distribution channels, entering new markets, reducing development and vehicle production costs, and capturing premiums from niche markets. Volvo Cars is now part of Ford’s Premier Automotive Group, which also includes Aston Martin, Jaguar, and Lincoln. Between 1987 and 1998, Volvo posted operating profits amounting to 3.7% of sales. Excluding the passenger car group, operating margins would have been 5.3%. To stay competitive, Volvo would have to introduce a variety of new passenger cars over the next decade. Volvo viewed the capital expenditures required to develop new cars as overwhelming for a company its size.
Historical and Projected Data
The initial review of Volvo’s historical data suggests that cash flow is highly volatile. However, by removing nonrecurring events, it is apparent that Volvo’s cash flow is steadily trending downward from its high in 1997. Table 9-10 displays a common-sized, normalized income statement, balance sheet, and cash-flow statement for Volvo, including both the historical period from 1993 through 1999 and a forecast period from 2000 through 2004. Although Volvo has managed to stabilize its cost of goods sold as a percentage of net sales, operating expenses as a percentage of net revenue have escalated in recent years. Operating margins have been declining since 1996. To regain market share in the passenger car market, Volvo would have to increase substantially its capital outlays. The primary reason valuation cash flow turns negative by 2004 is the sharp increase in capital outlays during the forecast period. Ford’s acquisition of Volvo will enable volume discounts from vendors, reduced development costs as a result of platform sharing, access to wider distribution networks, and increased penetration in selected market niches because of the Volvo brand name. Savings from synergies are phased in slowly over time, and they will not be fully realized until 2004. There is no attempt to quantify the increased cash flow that might result from increased market penetration.
Determining the Initial Offer Price
Volvo’s estimated value on a standalone basis is $15 billion. The present value of anticipated synergy is $1.1 billion, suggesting that the purchase price for Volvo should lie within a range of $15 million to about $16 billion. Although potential synergies appear to be substantial, savings due to synergies will be phased in gradually between 2000 and 2004. The absence of other current bidders for the entire company and Volvo’s urgent need to fund future capital expenditures in the passenger car business enabled Ford to set the initial offer price at the lower end of the range. Thus, the initial offer price could be conservatively set at about $15.25 billion, reflecting only about one-fourth of the total potential synergy resulting from combining the two businesses. Other valuation methodologies tended to confirm this purchase price estimate. The market value of Volvo was $11.9 billion on January 29, 1999. To gain a controlling interest, Ford had to pay a premium to the market value on January 29, 1999. Applying the 26% premium Ford paid for Jaguar, the estimated purchase price including the premium is $15 billion, or $34 per share. This compares to $34.50 per share estimated by dividing the initial offer price of $15.25 billion by Volvo’s total common shares outstanding of 442 million.
Determining the Appropriate Financing Structure
Ford had $23 billion in cash and marketable securities on hand at the end of 1998 (Naughton, 1999). This amount of cash is well in excess of its normal cash operating requirements. The opportunity cost associated with this excess cash is equal to Ford’s cost of capital, which is estimated to be 11.5%—about three times the prevailing interest on short-term marketable securities at that time. By reinvesting some portion of these excess balances to acquire Volvo, Ford would be adding to shareholder value, because the expected return, including the effects of synergy, exceeds the cost of capital. Moreover, by using this excess cash, Ford also is making itself less attractive as a potential acquisition target. The acquisition is expected to increase Ford’s EPS. The loss of interest earnings on the excess cash balances would be more than offset by the addition of Volvo’s pretax earnings.
Epilogue
Seven months after the megamerger between Chrysler and Daimler-Benz in 1998, Ford Motor Company announced that it was acquiring only Volvo’s passenger-car operations. Ford acquired Volvo’s passenger car operations on March 29, 1999, for $6.45 billion. At $16,000 per production unit, Ford’s offer price was considered generous when compared with the $13,400 per vehicle that Daimler-Benz AG paid for Chrysler Corporation in 1998. The sale of the passenger car business allows Volvo to concentrate fully on its truck, bus, construction equipment, marine engine, and aerospace equipment businesses. (Note that the standalone value of Volvo in the case was estimated to be $15 billion. This included Volvo’s trucking operations.)
-How was the initial offer price determined according to this case study? Do you find the logic underlying the initial offer price compelling? Explain your answer.
Determining the Initial Offer Price
Volvo’s estimated value on a standalone basis is $15 billion. The present value of anticipated synergy is $1.1 billion, suggesting that the purchase price for Volvo should lie within a range of $15 million to about $16 billion. Although potential synergies appear to be substantial, savings due to synergies will be phased in gradually between 2000 and 2004. The absence of other current bidders for the entire company and Volvo’s urgent need to fund future capital expenditures in the passenger car business enabled Ford to set the initial offer price at the lower end of the range. Thus, the initial offer price could be conservatively set at about $15.25 billion, reflecting only about one-fourth of the total potential synergy resulting from combining the two businesses. Other valuation methodologies tended to confirm this purchase price estimate. The market value of Volvo was $11.9 billion on January 29, 1999. To gain a controlling interest, Ford had to pay a premium to the market value on January 29, 1999. Applying the 26% premium Ford paid for Jaguar, the estimated purchase price including the premium is $15 billion, or $34 per share. This compares to $34.50 per share estimated by dividing the initial offer price of $15.25 billion by Volvo’s total common shares outstanding of 442 million.
Determining the Appropriate Financing Structure
Ford had $23 billion in cash and marketable securities on hand at the end of 1998 (Naughton, 1999). This amount of cash is well in excess of its normal cash operating requirements. The opportunity cost associated with this excess cash is equal to Ford’s cost of capital, which is estimated to be 11.5%—about three times the prevailing interest on short-term marketable securities at that time. By reinvesting some portion of these excess balances to acquire Volvo, Ford would be adding to shareholder value, because the expected return, including the effects of synergy, exceeds the cost of capital. Moreover, by using this excess cash, Ford also is making itself less attractive as a potential acquisition target. The acquisition is expected to increase Ford’s EPS. The loss of interest earnings on the excess cash balances would be more than offset by the addition of Volvo’s pretax earnings.
Epilogue
Seven months after the megamerger between Chrysler and Daimler-Benz in 1998, Ford Motor Company announced that it was acquiring only Volvo’s passenger-car operations. Ford acquired Volvo’s passenger car operations on March 29, 1999, for $6.45 billion. At $16,000 per production unit, Ford’s offer price was considered generous when compared with the $13,400 per vehicle that Daimler-Benz AG paid for Chrysler Corporation in 1998. The sale of the passenger car business allows Volvo to concentrate fully on its truck, bus, construction equipment, marine engine, and aerospace equipment businesses. (Note that the standalone value of Volvo in the case was estimated to be $15 billion. This included Volvo’s trucking operations.)
-How was the initial offer price determined according to this case study? Do you find the logic underlying the initial offer price compelling? Explain your answer. (Essay)
4.9/5 (84)
(84) An increase in gross margin over time could indicate what about the firm:
(Multiple Choice)
4.9/5 (83)
(83) A clear statement of all assumptions underlying the model's projections forces the analyst to display their biases and to be prepared to defend their assumptions to others.
(True/False)
4.9/5 (88)
(88) Financial modeling may be applied in which of the following situations:
(Multiple Choice)
4.8/5 (73)
(73) Common size financial statements are useful for comparing businesses of different sizes in the same industry at different points in time.
(True/False)
4.9/5 (72)
(72) Pro forma financial statements are simply another name for GAAP financial statements.
(True/False)
4.8/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)