



 Chat with AI
Exam 10: Special Partnership Issues

Exam 1: Tax Research115 Questions
Exam 2: Corporate Formations and Capital Structure207 Questions
Exam 3: The Corporate Income Tax114 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies56 Questions
Exam 6: Corporate Liquidating Distributions97 Questions
Exam 7: Corporate Acquisitions and Reorganizations102 Questions
Exam 8: Consolidated Tax Returns87 Questions
Exam 9: Partnership Formation and Operation114 Questions
Exam 10: Special Partnership Issues103 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax104 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates101 Questions
Exam 15: Administrative Procedures105 Questions
Exam 16: Tax Deductions and Travel Expenses for Employees and Self-Employed Individuals2 k+ Questions
Select questions type


Under Sec. 751, unrealized receivables include potential Section 1245 or 1250 recapture on the partnership's depreciable property.
(True/False)
4.9/5  (68)
(68) The XYZ Partnership owns the following assets on December 31: 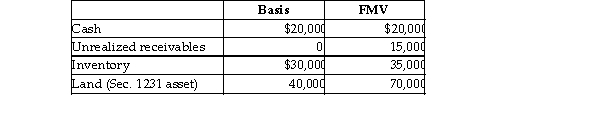 By how much must XYZ reduce its unrealized receivables to avoid meeting the substantially apprec inventory test?
 (Multiple Choice)
4.7/5 (74)
(74) The limited liability company (LLC) has become a popular business form because of its limited liability protection for its owner. The S corporation also provides limited liability protection for its owner. What advantages does an LLC provide that are not available with an S corporation?
(Essay)
4.9/5 (69)
(69) Under the check- the- box rules, an LLC with more than one member is taxed as a partnership unless it elects to be taxed as a corporation.
(True/False)
4.9/5 (84)
(84) A partnership cannot recognize a gain or loss on a current distribution.
(True/False)
4.7/5 (78)
(78) Carlos has a basis in his partnership interest of $30,000. He receives a current distribution of $6,000 cash, unrealized receivables (FMV $11,000, basis $10,000), inventory (FMV $8,000, basis $4,000), land held as an investment (FMV $7,000, basis, $6,000), and building (FMV $21,000, basis $9,000). The partners' relative interests in the Sec. 751 assets do not change as a result of the current distribution. Carlos's basis in the building is
(Multiple Choice)
4.8/5 (81)
(81) The Tandy Partnership owns the following assets on December 31: 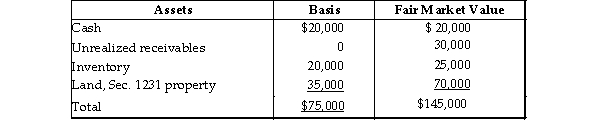 Is the partnership's inventory considered to be substantially appreciated for purposes of Sec. 751? Show your work.
 (Essay)
4.8/5 (77)
(77) The STU Partnership, an electing Large Partnership, has no passive activities and reports the following transactions for the year: net long- term capital losses $50,000, Sec. 1231 gain $60,000, ordinary income $20,000, charitable contributions $15,000, and tax- exempt income $2,000. How much will be reported as long- term capital gains to its partners?
(Multiple Choice)
4.9/5 (83)
(83) Do most distributions made by a partnership require a Sec. 751 calculation?
(Essay)
5.0/5 (82)
(82) Rod owns a 65% interest in the RRR Partnership, a general partnership, which he sells to the two remaining partners - Roger and Regis. The three partners have agreed that Rod will receive $160,000 in cash from the sale. Rod's basis in the partnership interest before the sale is $125,000, which includes his $35,000 share of partnership recourse liabilities. The partnership has assets with a $310,000 FMV and a $210,000 adjusted basis. What issues should Rod, Roger, and Regis consider before this sale takes place?
(Essay)
4.9/5 (79)
(79) What are the advantages of a firm being formed as a limited liability company (LLC) instead of as a limited partnership?
(Essay)
4.9/5 (82)
(82) What is an electing large partnership? What are the advantages to the partnership of electing to be taxed under the electing large partnership rules?
(Essay)
4.7/5 (74)
(74) The Principle Limited Partnership has more than 300 partners and is publicly traded. The Principle was grandfathered under the 1987 Tax Act and has consistently been taxed as a partnership. In the current year, The Principle Limited Partnership will continue to be very profitable and will continue to pay out about 30% of its income to its owners each year. The managing partners of The Principle want to consider the firm's options for taxation in the current and later years.
(Essay)
4.9/5 (84)
(84) A limited liability company is a form of business entity that combines the legal benefits of the corporate form with the tax benefits of the partnership form.
(True/False)
4.8/5 (76)
(76) Sally is a calendar- year taxpayer who owns a 30% capital and profits interest in the SEM Partnership. Eric sells the remaining 70% capital and profits interest to Michelle on October 3. The partnership year- end is March 31 as permitted by the IRS for business purposes. Which of the following statements is correct?
(Multiple Choice)
4.9/5 (73)
(73) Jerry has a $50,000 basis for his interest in JJ Partnership before receiving a current distribution consisting of
$8,000 in money, accounts receivable having a zero basis to the partnership, and land having a $28,000 basis to the partnership. What will Jerry's basis be in these assets?
(Essay)
4.8/5 (74)
(74) What is the definition of "substantially appreciated inventory"?
(Multiple Choice)
4.9/5 (77)
(77) The STU Partnership, an electing Large Partnership, has no passive activities and reports the following transactions for the year: net long- term capital losses $50,000, Sec. 1231 gain $60,000, ordinary income $20,000, charitable contributions $15,000, and tax- exempt income $2,000. How much will be reported as ordinary income to its partners?
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)