



 Chat with AI
Exam 13: The Estate Tax

Exam 1: Tax Research115 Questions
Exam 2: Corporate Formations and Capital Structure207 Questions
Exam 3: The Corporate Income Tax114 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies56 Questions
Exam 6: Corporate Liquidating Distributions97 Questions
Exam 7: Corporate Acquisitions and Reorganizations102 Questions
Exam 8: Consolidated Tax Returns87 Questions
Exam 9: Partnership Formation and Operation114 Questions
Exam 10: Special Partnership Issues103 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax104 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates101 Questions
Exam 15: Administrative Procedures105 Questions
Exam 16: Tax Deductions and Travel Expenses for Employees and Self-Employed Individuals2 k+ Questions
Select questions type


A qualified disclaimer is a valuable estate planning tool because
(Multiple Choice)
4.7/5  (66)
(66) In 2016, Clara made taxable gifts of $2 million. This year, Clara dies with a taxable estate of $4 million. At the time of her death, the FMV of the property Clara gifted in 2001 is $8 million. What is the amount of the estate tax base?
(Short Answer)
4.8/5 (98)
(98) For 2014, the unified credit is equivalent to a statutory exemption of
(Multiple Choice)
4.9/5 (86)
(86) Which of the following is deductible in arriving at the amount of the taxable estate?
(Multiple Choice)
4.9/5 (77)
(77) Lily dies early in the current year. All her property passes subject to her will, which provides that her surviving husband, Rick, is to receive all the property outright. Her will further states that any property Rick disclaims will pass instead to their children in equal shares. Lily's gross estate is about $10 million, and her Sec. 2053 deductions are very small. Rick, who is in poor health, already owns about $6 million of property. What tax issues should Rick consider with respect to the property bequeathed to him by his wife?
(Essay)
4.7/5 (78)
(78) Administrative expenses are not deductible on the estate's income tax return.
(True/False)
4.7/5 (82)
(82) On December 1, 1976, Bart made a gift and claimed a $30,000 specific exemption. When Bart died in 2017, his tax base was $2,000,000. Assuming the maximum unified credit is $780,800, what is the credit available when computing Bart's estate tax?
(Essay)
4.7/5 (88)
(88) A special power of appointment exists if the holder can exercise the power in favor of himself or herself, his or her creditors, or the creditors of his or her estate.
(True/False)
4.9/5 (74)
(74) Sasha gives $1,000,000 to her granddaughter. Sasha has used all of her unified credit and is in the 40% marginal gift tax bracket; ignore the annual exclusion and exemption. What is the amount of her tax on this transfer?
(Multiple Choice)
4.8/5 (84)
(84) Which of the following circumstances would cause the gifted property to be included in the donor's estate? I. Donor retains a life estate in the gift property.
II) Donor retains the power to revoke or amend the gift.
III) Donor gives more than $14,000 to one donee in one year.
IV) Donor dies within three years of gifting land.
(Multiple Choice)
4.9/5 (88)
(88) One of the major problems facing executors in managing the estate is
(Multiple Choice)
5.0/5 (91)
(91) The tax base for the federal estate tax is the total of the decedent's taxable estate and post- 1986 taxable gifts if the decedent made gifts in 1981.
(True/False)
4.8/5 (88)
(88) Ted died on May 3. At the time of his death, he owned a beach house valued at $250,000. On June 10, the beach house was completely destroyed by a hurricane and there was no insurance coverage. If the executor elects to use the alternate valuation date, the executor will
(Multiple Choice)
4.8/5 (82)
(82) Guy died this year. His estate includes a closely held business interest valued at $400,000 and other property valued at $675,000. Guy's allowable Sec. 2053 and 2054 deductions total $75,000. Within three years of death, partly in hopes of qualifying his estate for the installment payment allowed under Sec. 6166 treatment, Guy made gifts of listed securities of $350,000 (at 2002 valuations) and paid no gift tax on the gift. Is Guy's estate eligible for Sec. 6166 treatment?
(Essay)
4.9/5 (66)
(66) Following are the fair market values of Wilma's assets at her date of death: 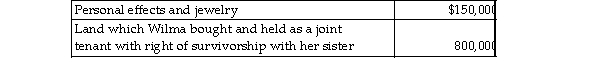 The executor of Wilma's estate did not elect the alternate valuation date. The amount includible in W gross estate is
 (Multiple Choice)
5.0/5 (83)
(83) Which of the following is not a credit for purposes of computing the federal estate tax liability?
(Multiple Choice)
4.8/5 (76)
(76) Outline and briefly describe the estate tax computation, beginning with the gross estate.
(Essay)
4.8/5 (91)
(91) In 2006, Roger gives stock valued at $100,000 to Martha. Roger and Martha are not related. In 2008, Martha uses the stock then valued at $110,000 as partial consideration to acquire realty costing $220,000. Pat (her brother) furnishes the remaining $110,000 of consideration. The realty is titled in the names of Martha and Pat as joint tenants with right of survivorship. This year, Martha dies and Pat survives. The realty is valued at $300,000 at Martha's death. How much, if any, of the realty's value will be included in Martha's estate?
(Multiple Choice)
4.9/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)