



 Chat with AI
Exam 6: Corporate Liquidating Distributions

Exam 1: Tax Research115 Questions
Exam 2: Corporate Formations and Capital Structure207 Questions
Exam 3: The Corporate Income Tax114 Questions
Exam 4: Corporate Nonliquidating Distributions113 Questions
Exam 5: Other Corporate Tax Levies56 Questions
Exam 6: Corporate Liquidating Distributions97 Questions
Exam 7: Corporate Acquisitions and Reorganizations102 Questions
Exam 8: Consolidated Tax Returns87 Questions
Exam 9: Partnership Formation and Operation114 Questions
Exam 10: Special Partnership Issues103 Questions
Exam 11: S Corporations103 Questions
Exam 12: The Gift Tax104 Questions
Exam 13: The Estate Tax107 Questions
Exam 14: Income Taxation of Trusts and Estates101 Questions
Exam 15: Administrative Procedures105 Questions
Exam 16: Tax Deductions and Travel Expenses for Employees and Self-Employed Individuals2 k+ Questions
Select questions type


If a liquidating subsidiary corporation primarily has loss property to distribute, the parent corporation should
(Multiple Choice)
4.9/5  (88)
(88) Charlene and Dennis each own 50% of Brewster Corporation and have owned it for five years. The adjusted bases of their Brewster stock are $80,000 and $40,000 respectively. Brewster Corporation liquidates and distributes $60,000 to Charlene in exchange for her stock. It distributes a parcel of land with a $140,000 FMV which is subject to a $90,000 mortgage to Dennis in exchange for his stock. Dennis assumes the mortgage and als receives $10,000 in cash.
a) What is the character and amount of each shareholder's gain or loss?
b) What is each shareholder's basis in the property received in the liquidation?
(Essay)
4.7/5 (71)
(71) Riverwalk Corporation is liquidated, with Juan receiving $5,000 in money and other property having a $6,000 FMV. Juan's basis in his Riverwalk stock is $8,000. Upon liquidation, Juan must recognize a gain of
(Multiple Choice)
4.9/5 (81)
(81) What event determines when a cash or accrual method of accounting taxpayer reports a liquidating distribution?
(Essay)
4.8/5 (87)
(87) Under what circumstances does a liquidating corporation not recognize a gain or loss when making a distribution?
(Essay)
4.8/5 (77)
(77) Parent Corporation, which operates an electric utility, created a 100%- owned corporation, Subsidiary, that built and managed an office building. Assume the two corporations have filed separate tax returns for a number of years. The utility occupied two floors of the office building, and Subsidiary offered the other ten floors for lease. Only 25% of the total rental space was leased because of the high crime rate in the area surrounding the building. Rental income was insufficient to cover the mortgage payments, and Subsidiary filed for bankruptcy because of the poor prospects. Subsidiary's assets were taken over by the mortgage lender. Parent lost its entire
$500,000 investment. At the time Subsidiary was liquidated, another $100,000 of debts remained unpaid for the general creditors, which included a $35,000 account payable to Parent. What tax issues should Parent and Subsidiary consider with respect to the bankruptcy and liquidation of Subsidiary?
(Essay)
5.0/5 (82)
(82) Jack has a basis of $36,000 in his 1,000 shares of Acorn Corporation stock (a capital asset). The stock was acquired three years ago. He receives the following distributions as part of a plan of liquidation of Acorn Corporation: 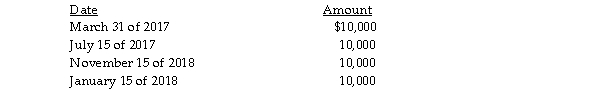 What are the amount and character of the gain or loss that Jack will recognize during 2017? During 2018?
 (Essay)
4.7/5 (86)
(86) Lake Corporation distributes a building used in its business to Sandy in exchange for all of her Lake stock. Sandy's basis in her stock is $30,000 and the property she receives has a $90,000 FMV. As part of the distribution, Sandy assumes a liability associated with the property of $65,000. The property's basis prior to the liquidating distribution was $25,000. What are the tax consequences of the distribution to Sandy? To Lake Corporation?
(Essay)
4.7/5 (83)
(83) Toby made a capital contribution of a pretzel maker having a $2,000 adjusted basis and a $200 FMV to Keke Corporation in exchange for additional stock last year. Later that same year, Keke sold the pretzel maker for $300. This year, Keke adopted a plan of liquidation. Previously, Keke had never used the pretzel maker in connection with the conduct of its trade or business. The sale was reported on Keke's current tax return. What reporting option does Keke Corporation not have because of its plan of liquidation?
(Multiple Choice)
4.8/5 (73)
(73) The stock of Cooper Corporation is 70% owned by Carole and 30% owned by Carole's brother, Chris. During 2017, Chris transferred property (basis of $100,000 and FMV of $120,000) as a contribution to the capital of Cooper. During February 2018, Cooper adopted a plan of liquidation and subsequently made a pro rata distribution of the property back to Carole and Chris. At the time of the liquidation, the property had an FMV of $80,000. What amount of loss can be recognized by Cooper on the distribution of property?
(Multiple Choice)
4.9/5 (88)
(88) Last year, Toby made a capital contribution of a pretzel maker having a $2,000 adjusted basis and a $200 FMV to Keke Corporation in exchange for additional stock. This year, Keke Corporation adopted a plan of liquidation. Prior to the adoption of the liquidation plan, Keke had not used the pretzel maker in connection with the conduct of its trade or business. Which of the following statements is true?
(Multiple Choice)
4.8/5 (85)
(85) A corporation is required to file Form 966 within 30 days after the adoption of a plan of liquidation.
(True/False)
4.9/5 (78)
(78) Lake City Corporation owns all the stock in Columbia Corporation. Pursuant to a plan of complete liquidation, Columbia distributes land having a $500,000 FMV and a $200,000 basis to Lake City. Columbia's gain with respect to the distribution will be
(Multiple Choice)
4.8/5 (88)
(88) In a complete liquidation of a corporation, which of the following is false?
(Multiple Choice)
4.9/5 (73)
(73) During 2017, Track Corporation distributes property to Cindy as part of a complete liquidation. Property included in the distribution is $30,000 in cash, land with a $40,000 adjusted basis and a $60,000 FMV, and a copyright without an ascertainable FMV and having a zero basis. The first payment to Cindy of $8,000 for use of the copyrighted property occurs in 2018. Cindy has a basis in the Track stock of $95,000 immediately preceding the liquidation. The minimum amount of gain that Cindy must recognize is a
(Multiple Choice)
4.9/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)