



 Chat with AI
Exam 13: Jurisdictional Issues in Business Taxation

Exam 1: Taxes and Taxing Jurisdictions90 Questions
Exam 2: Policy Standards for a Good Tax85 Questions
Exam 3: Taxes As Transaction Costs82 Questions
Exam 4: Maxims of Income Tax Planning92 Questions
Exam 5: Tax Research82 Questions
Exam 6: Taxable Income From Business Operations115 Questions
Exam 7: Property Acquisitions and Cost Recovery Deductions116 Questions
Exam 8: Property Dispositions122 Questions
Exam 9: Nontaxable Exchanges105 Questions
Exam 10: Sole Proprietorships, partnerships, llcs, and S Corporations100 Questions
Exam 11: The Corporate Taxpayer95 Questions
Exam 12: The Choice of Business Entity99 Questions
Exam 13: Jurisdictional Issues in Business Taxation111 Questions
Exam 14: The Individual Tax Formula116 Questions
Exam 15: Compensation and Retirement Planning112 Questions
Exam 16: Investment and Personal Financial Planning109 Questions
Exam 17: Tax Consequences of Personal Activities85 Questions
Exam 18: The Tax Compliance Process88 Questions
Select questions type


Luttrix Inc.does business in Nebraska (6% tax rate)and Colorado (3% tax rate).All other factors being equal,Luttrix will reduce state taxes if it constructs a new manufacturing plant in Colorado.Assume apportionment formula modeled after the Uniform Division of Income for Tax Purposes Act (UDITPA).
(True/False)
4.7/5  (93)
(93) Tri-State's,Inc.operates in Arkansas,Oklahoma,and Kansas.Assume that each state has adopted the UDITPA formula.During the corporation's tax year ended December 31,the apportionment data indicated:  Which of the following statements is true?
 (Multiple Choice)
4.9/5 (87)
(87) Kraze,Inc.,a calendar year domestic corporation,owns 50 percent of the stock of Malik,a calendar year specified foreign corporation.Prior to 2018,Malik has accumulated deferred foreign earnings of $40 million and an aggregate foreign cash position of $5.1 million.Assume Malik paid zero foreign tax on its earnings.
a.Calculate Kraze's mandatory inclusion amount for Malik's deferred foreign earnings and its pro rata share of Malik's foreign cash position.
b.Calculate Kraze's incremental tax liability on its mandatory inclusion amount.
c.Determine Kraze's installment payments of the tax liability on its mandatory inclusion amount.Assume such payments begin in 2017.
(Essay)
4.8/5 (86)
(86) Which of the following would qualify as a permanent establishment for income tax treaty purposes?
(Multiple Choice)
5.0/5 (68)
(68) Macon,Inc.,a U.S.corporation,owns stock in four corporations operating overseas.Which of the following will qualify for the 100% dividends-received deduction?
(Multiple Choice)
4.8/5 (91)
(91) Cheney is a controlled foreign corporation with total foreign earnings of $4 million,of which $1.3 million is considered subpart F income.Cheney owns tangible business property with an adjusted tax basis of $6 million.Compute Cheney's global intangible low-taxed income.
(Multiple Choice)
4.9/5 (71)
(71) Which of the following taxes is eligible for the foreign tax credit?
(Multiple Choice)
4.8/5 (58)
(58) Fleming Corporation,a U.S.multinational,has pretax U.S.source income and foreign source income as follows:  Fleming paid $200,000 income tax to Country A.If Fleming takes the foreign tax credit,compute its worldwide tax burden as a percentage of its pretax income.
 (Multiple Choice)
4.9/5 (89)
(89) Harris Corporation's before-tax income was $400,000.It does business entirely in Pennsylvania,which has a 6% corporate income tax.Compute Harris' federal income tax.
(Multiple Choice)
4.7/5 (67)
(67) Sales to foreign customers through a branch office of a U.S.corporation are considered foreign-derived intangible income eligible for a preferential tax rate.
(True/False)
5.0/5 (79)
(79) Under most tax treaties,income attributable to a permanent establishment through which a foreign taxpayer conducts business can be taxed only by the taxpayer's country of residence.
(True/False)
4.9/5 (77)
(77) Crane,Inc.is a domestic corporation with several foreign subsidiaries.This year,Crane has $2.3 million domestic gross receipts and $900,000 allowable deductions.It made deductible related party payments to its foreign affiliates of $650,000.Compute Crane's base erosion and anti-abuse tax liability.
(Multiple Choice)
4.8/5 (93)
(93) Which of the following statements about the foreign tax credit limitation is false?
(Multiple Choice)
4.8/5 (79)
(79) According to Public Law 86-272,the sale of tangible goods to residents of a state is not sufficient to establish nexus in that state.
(True/False)
4.9/5 (75)
(75) The sales factor in the UDITPA state income tax apportionment formula equals out-of-state sales divided by total sales.
(True/False)
4.7/5 (73)
(73) The payroll factor in the UDITPA state income tax apportionment formula always includes executive compensation.
(True/False)
5.0/5 (74)
(74) The federal income tax deduction allowed for state income taxes paid decreases the cost of the state taxes.
(True/False)
4.8/5 (83)
(83) Non-resident firms selling tangible goods to in-state residents can use P.L.86-272 to avoid having income tax nexus in a state.
(True/False)
4.8/5 (73)
(73) Which of the following statements concerning the nexus required for a state to tax income is false?
(Multiple Choice)
4.7/5 (67)
(67) Origami does business in states X and Y.State X uses an equally-weighted three-factor apportionment formula and has a 4 percent state tax rate.State Y uses an apportionment formula that double-weights the sales factor and has a 6 percent tax rate.Origami's taxable income,before apportionment,is $3 million.Its sales,payroll,and property information are as follows.
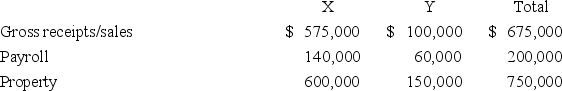 a.Calculate Origami's apportionment factors,income apportioned to each state,and state tax liability.
b.State Y is considering changing its apportionment formula to a single sales factor.Given its current level of activity,would such a change increase or decrease Origami's state income tax burden? Provide calculations to support your conclusion.
a.Calculate Origami's apportionment factors,income apportioned to each state,and state tax liability.
b.State Y is considering changing its apportionment formula to a single sales factor.Given its current level of activity,would such a change increase or decrease Origami's state income tax burden? Provide calculations to support your conclusion. (Essay)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)