



 Chat with AI
Exam 8: Short-Run Costs and Output Decisions

Exam 1: The Scope and Method of Economics241 Questions
Exam 2: The Economic Problem: Scarcity and Choice218 Questions
Exam 3: Demand, Supply, and Market Equilibrium309 Questions
Exam 4: Demand and Supply Applications173 Questions
Exam 5: Elasticity188 Questions
Exam 6: Household Behavior and Consumer Choice272 Questions
Exam 7: The Production Process: the Behavior of Profit-Maximizing Firms287 Questions
Exam 8: Short-Run Costs and Output Decisions386 Questions
Exam 9: Long-Run Costs and Output Decisions363 Questions
Exam 10: Input Demand: the Labor and Land Markets200 Questions
Exam 11: Input Demand: the Capital Market and the Investment Decision218 Questions
Exam 12: General Equilibrium and the Efficiency of Perfect Competition202 Questions
Exam 13: Monopoly and Antitrust Policy394 Questions
Exam 14: Oligopoly219 Questions
Exam 15: Monopolistic Competition235 Questions
Exam 16: Externalities, Public Goods, and Common Resources275 Questions
Exam 17: Uncertainty and Asymmetric Information134 Questions
Exam 18: Income Distribution and Poverty197 Questions
Exam 19: Public Finance: the Economics of Taxation281 Questions
Exam 20: International Trade, Comparative Advantage, and Protectionism287 Questions
Exam 21: Economic Growth in Developing Economies133 Questions
Exam 22: Critical Thinking About Research104 Questions
Select questions type


If the average variable cost of the fifth hat is $50, then the total variable cost of five hats is
(Multiple Choice)
4.8/5  (86)
(86) Joe's Butcher Shop is producing where MR = MC; Joe's Butcher Shop must be
(Multiple Choice)
4.9/5 (71)
(71) The decision by firms of the quantity of output to supply is based on
(Multiple Choice)
4.9/5 (82)
(82) Refer to the short-run information provided in Figure 8.5 below to answer the question(s) that follow
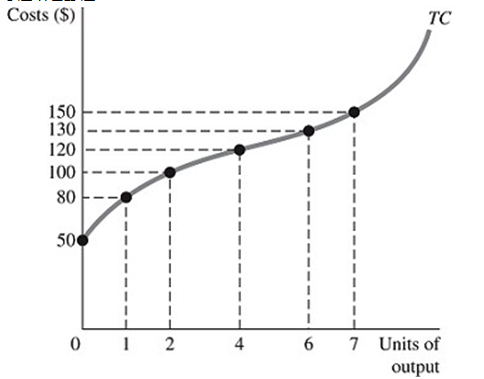 Figure 8.5
-Refer to Figure 8.4. Micro Oven's average fixed costs of producing three units of output are
Figure 8.5
-Refer to Figure 8.4. Micro Oven's average fixed costs of producing three units of output are (Multiple Choice)
4.8/5 (70)
(70) A point on a total variable cost curve shows the ________ variable cost a firm will bear to produce a certain output.
(Multiple Choice)
4.9/5 (72)
(72) Which of the following is the closest example of a perfectly competitive industry?
(Multiple Choice)
4.9/5 (72)
(72) Wheat is produced in a perfectly competitive market. Market demand for wheat increases. This will cause the individual wheat farmer's marginal revenue to ________ and their profit-maximizing level of output to ________.
(Multiple Choice)
4.8/5 (92)
(92) Assume Robbie's Robots operates in a perfectly competitive market producing 3,000 robots per day. At this output level, the selling price is $800 per robot and the marginal cost is $625 per robot. To maximize profits, Robbie's Robots should
(Multiple Choice)
4.8/5 (83)
(83) Refer to the short-run information provided in Figure 8.5 below to answer the question(s) that follow
Figure 8.5
-Refer to Figure 8.5. If four drones are produced, average variable costs are
Figure 8.5
-Refer to Figure 8.5. If four drones are produced, average variable costs are (Multiple Choice)
4.9/5 (62)
(62) If marginal cost is above average total cost, average total cost will
(Multiple Choice)
4.8/5 (72)
(72) For a perfectly competitive firm, when P = MC = ATC, the firm should reduce its output so as to increase its profits.
(True/False)
4.9/5 (63)
(63) If an individual perfectly competitive firm charges a price ________ the industry equilibrium price while competitors charge the equilibrium price, the firm will not sell any of what it produces.
(Multiple Choice)
4.7/5 (65)
(65) The short-run average variable cost curve eventually begins to increase at an increasing rate because of
(Multiple Choice)
5.0/5 (78)
(78) Refer to the information provided in Figure 8.6 below to answer the question(s) that follow. 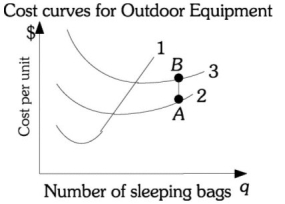 Figure 8.6
-Refer to Figure 8.6. Curve 1 is Outdoor Equipment's
Figure 8.6
-Refer to Figure 8.6. Curve 1 is Outdoor Equipment's (Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)